
Is Merchants Bancorp (MBIN) Undervalued After Strong Q3 Results And An Analyst Upgrade?
Merchants Bancorp (MBIN) is back in focus after reporting third quarter results on October 28, 2026, featuring higher earnings, lower charge offs, and an analyst upgrade that has sharpened investor attention.
Recent trading reflects that story. Merchants Bancorp’s share price has climbed 9.5% over the past month and delivered a 61.5% year to date share price return, while the 1 year total shareholder return of 69.4% points to strong momentum building around the stock.
Capitalize on the momentum around Merchants Bancorp by scanning a curated 35 high quality undervalued stocks that combine strong fundamentals with potential for further rerating.For Merchants Bancorp, that sharp rerating sits at the intersection of stronger reported results and a brighter story investors are telling themselves. How much of this move does the current valuation actually support?
Price-to-Earnings of 8.8x: Is it justified?
On simple valuation math, Merchants Bancorp trades on a P/E of 8.8x, which is being applied to a stock that has delivered a 69.4% 1 year total return and is still 20.0% below the $67 analyst target price.
The P/E ratio compares what investors pay today per share with the earnings that Merchants Bancorp generates per share. For a diversified financial company with $703.4m in revenue and $279.2m in net income, it gives a quick sense of how much the market is willing to pay for each dollar of profit.
Here, that 8.8x multiple sits below several reference points. It is below the estimated fair P/E of 10.7x from the SWS fair ratio framework. It is also below the peer average of 9.5x and well under the broader US Diversified Financial industry on 14.8x. That combination signals the market is assigning a lower earnings multiple to a business that has grown earnings 39.8% over the past year, lifted net profit margins from 33.4% to 39.7%, and is forecast to grow earnings a further 3.85% each year. If sentiment or positioning shifted closer to the fair ratio level, the valuation multiple is one area that could move.
Explore the SWS fair ratio for Merchants Bancorp.
Result: Price-to-Earnings of 8.8x (UNDERVALUED)
Still, that momentum narrative around Merchants Bancorp can crack if credit conditions tighten for multifamily or healthcare borrowers, or if mortgage warehousing volumes retreat.
Find out about the key risks to this Merchants Bancorp narrative.
Another View: What The DCF Says About Merchants Bancorp
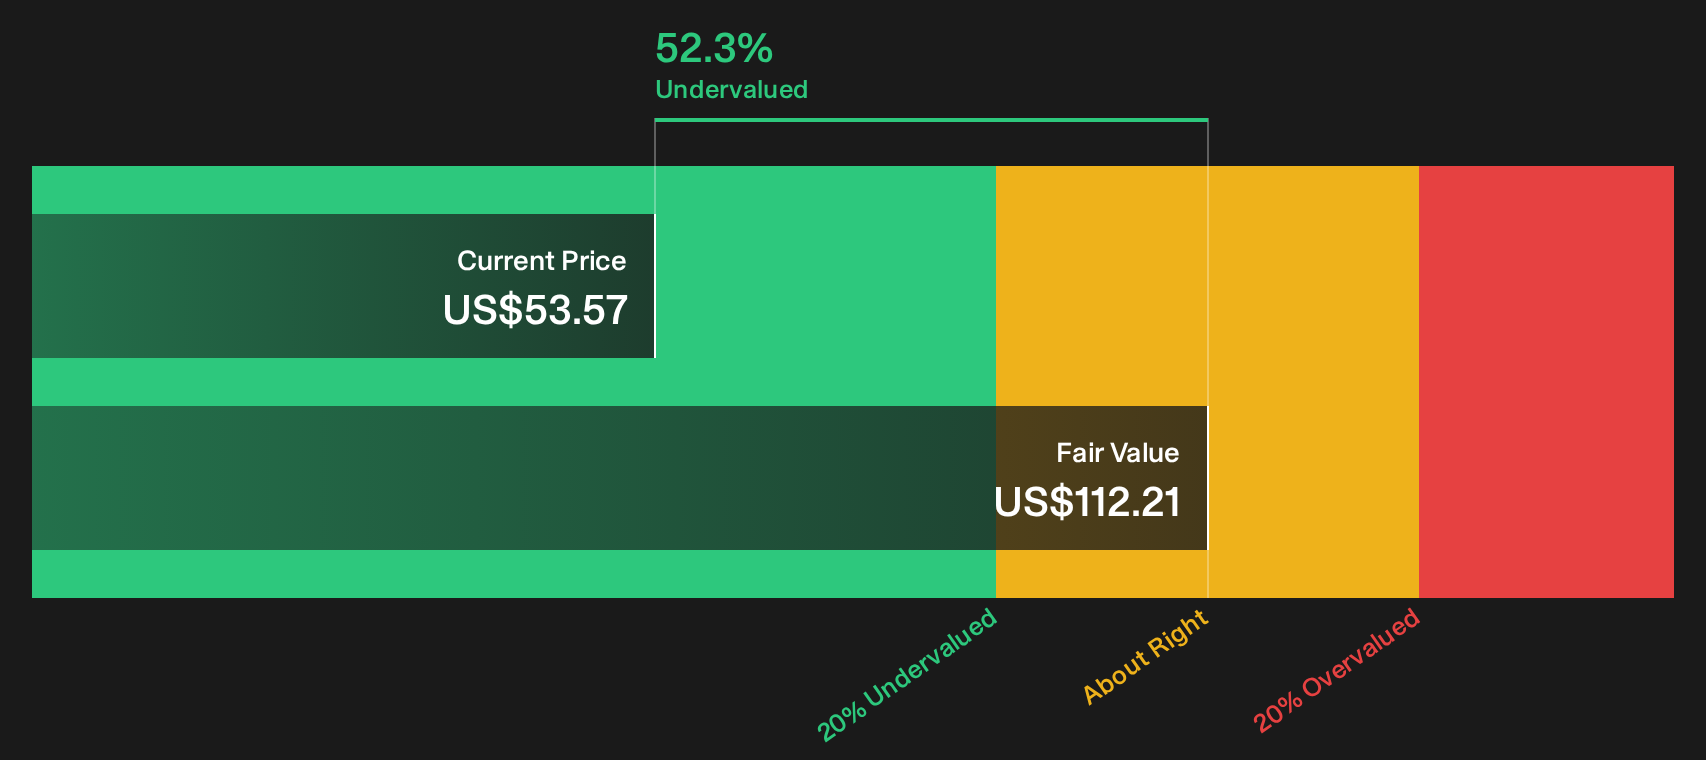
The 8.8x P/E ratio presents Merchants Bancorp as inexpensive, and the SWS DCF model adds another perspective. With the shares at $53.57 and an estimated future cash flow value of $112.21, the stock is described as trading at a 52.3% discount. How comfortable are you relying on that cash flow story?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Merchants Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Merchants Bancorp is clearly upbeat right now, yet the mix of potential upsides and flagged issues deserves your own close read. Act quickly, review the full picture in one place, and weigh both sides of the story through the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Merchants Bancorp?
Do not stop with Merchants Bancorp. Use the Simply Wall Street Screener to uncover fresh opportunities with different risk profiles, sector exposures, and income characteristics.
- Target resilient balance sheets and steady fundamentals by scanning a focused list of solid balance sheet and fundamentals (24 results) that can help you filter out financially fragile businesses.
- Hunt for potential mispricings by reviewing a curated 20 high quality undiscovered gems that highlights quality companies investors may be overlooking right now.
- Build a portfolio tilted toward income by checking a hand picked 5 dividend fortresses that screens for higher yielding stocks with stronger foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com