
3 Insurance Stocks To Watch As D And O Liability Demand Comes Into Focus
The Nvidia scandal has turned a single corporate crisis into a live stress test for everything tied to boardrooms, disclosure and securities litigation. When US$430b in value can vanish in two days, attention quickly shifts to who insures, advises and defends companies when governance risk explodes into headlines. This piece explores how that shock ripples into three stocks exposed to the same news, and why their fortunes may not all move in the same direction.
The stocks covered below are a small sample of listed D&O insurers and securities litigation specialists. The full screen surfaced 22 more businesses with equally detailed governance and legal risk stories that are not broken out here. If you want to identify, compare and analyze potential high conviction exposures around these themes, head straight to the Listed D&O Insurers and Securities-Litigation Specialists screener.
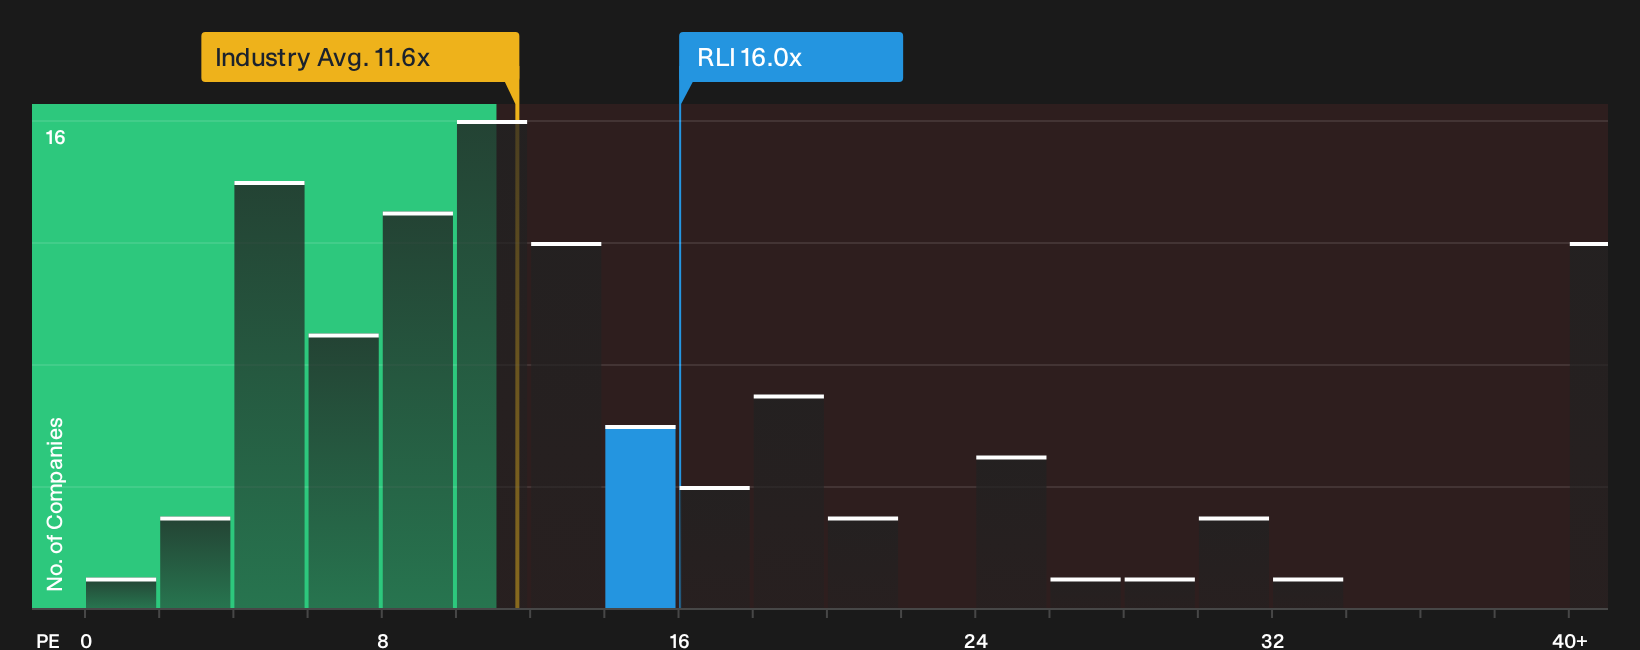
RLI (RLI)
RLI is on this D&O and securities-litigation themed list because its specialty casualty arm writes directors and officers and other executive liability cover, putting it close to the governance risks investors are focused on after the Nvidia headlines.
RLI Corp. is a US specialty insurer focused on commercial property, casualty and surety risks, with a strong foothold in executive and professional liability that links directly to D&O demand. Most revenue comes from casualty at about US$1.0b, followed by property at roughly US$499 million and surety near US$146 million, with extra income from investments and portfolio gains. The business is entirely US based and carries a market value of about US$6.2b.
The analyst consensus Narrative on Simply Wall St captures how a specialist like RLI can benefit from heightened concern around boardroom risk while still facing pressure in some lines.
"The softening of commercial and E&S property markets, with intense competition and rate giveback on hurricane and earthquake risks, is expected to keep pressure on RLI’s ability to grow property premiums while protecting loss ratios."
What matters now is how this specialist responds if a single unseen pressure quietly shifts the balance between pricing power and underwriting discipline.
If that unseen pressure is what you are testing, read the full narrative for RLI to see how pricing, underwriting discipline and governance risk could be decoupling.
W. R. Berkley (WRB)
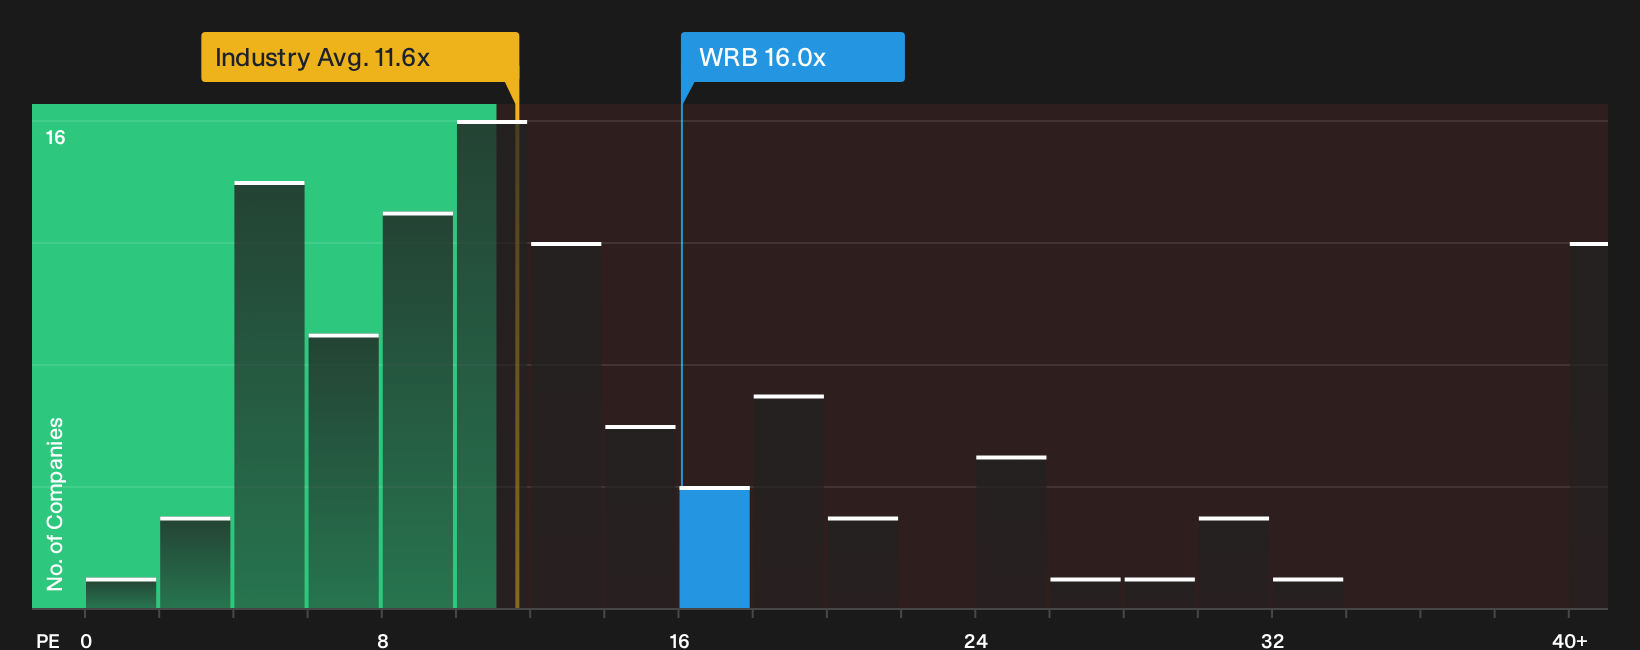
W. R. Berkley is another key governance risk proxy in this screen, with the analyst consensus Narrative on Simply Wall St highlighting how its specialty commercial coverage, including D&O and related executive liability, ties earnings power to how corporate clients handle disclosure shocks and complex legal exposures.
"The expanding complexity of global business and assets is driving demand for specialty insurance solutions. W. R. Berkley is building on this with mid single digit gross and net premium growth in its Insurance segment, alongside current accident year ex cat combined ratios around 89%, which can support revenue and underwriting income."
This raises the question of how that balance might change if a single shift in governance driven claims trends quietly tightens the room for underwriting error.
W. R. Berkley is a US$29.5b commercial insurer and reinsurer, generating about US$12.5b from Insurance and US$1.7b from Reinsurance & Monoline Excess. This makes it a large, diversified D&O aligned carrier squarely exposed to boardroom and securities litigation themes.
That tighter room for error is exactly what the full narrative for W. R. Berkley unpacks, highlighting where accelerating complexity could still mask overlooked upside in W. R. Berkley.
Münchener Rückversicherungs-Gesellschaft in München (XTRA:MUV2)
Münchener Rückversicherungs-Gesellschaft in München matters in this screen because global reinsurers often absorb part of the corporate liability and D&O risks that primary insurers pass on. According to jacques_oe0g9, an investor in the Simply Wall St Community, the recent setup around this stock turns on one simple timing question.
"Main risk: reinsurance pricing is softening (about −2.5% at the January 2026 renewals), and Q3 results land on 12 November."
What happens if a single shift in boardroom related claims pricing quietly reworks how much profit those January renewals can really support?
Münchener Rückversicherungs-Gesellschaft in München is a global reinsurer and insurer that backs corporate liability risks tied to D&O and securities issues, earning about €17.7b from property casualty reinsurance, €13.2b from life and health reinsurance, €15.5b from ERGO Germany, €8.0b from Global Specialty Insurance and €7.1b from ERGO International, with a market value near €71.5b.
If that question is front of mind, the full narrative for Münchener Rückversicherungs-Gesellschaft in München maps how softening pricing, claims trends and capital cycles might be quietly accelerating opportunity for Münchener Rückversicherungs-Gesellschaft in München.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes gain momentum while they are still under the radar for now. Do not get caught watching prices flying without you, act now.
- Scan for early breakouts in smaller names that already generate cash and keep dilution in check using the 41 profitable AI stocks that aren't just burning cash.
- Pressure test your income holdings against a curated pool of high yielders that aim to keep payouts resilient through cycles via the 5 dividend fortresses.
- Track capital flowing into critical grid upgrades with a focused set of infrastructure stocks that could benefit from sustained demand for reliability through the 41 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com