
CBRE Group (CBRE) Reaffirms 2026 Outlook, Is It Still A Bargain?
CBRE Group (CBRE) reaffirmed its 2026 core EPS outlook and highlighted growth in recurring outsourcing services, including data centers and technology-driven offerings, despite ongoing macro and real estate capital markets pressures.
Recent trading has been choppy for CBRE Group, with the share price falling 2.45% on the day and down 15.86% year to date. However, a 3.05% 1 month share price return and a 72.94% 3 year total shareholder return suggest that longer term momentum has been much stronger than the latest pullback implies.
Scan for other commercial real estate plays that pair recurring outsourcing revenues with growth angles similar to CBRE Group by reviewing the list of solid balance sheet and fundamentals (24 results) in one pass.
The pullback in CBRE Group appears sharp compared with a three-year period that treated shareholders far better, which creates a clear tension for investors. Are you seeing a business reset, or simply a shift in sentiment that is moving the price before the numbers catch up?
Most Popular Narrative: 22% Undervalued
The analyst consensus Narrative on Simply Wall St places CBRE Group's fair value at $172 against a last close of $134.79, which points to a 22% discount based on its modeled cash flows and earnings path rather than short term share price swings.
Disciplined capital allocation that prioritises mergers and acquisitions in growth verticals such as critical infrastructure and data centers, funded by nearly US$1.7b of trailing twelve month free cash flow and complemented by close to US$1b of share repurchases year to date by late Q2 2026, creates scope for accretive revenue growth and EPS expansion if acquired platforms scale within CBRE Group’s existing service lines.
See why 16 investors see CBRE Group as 22% undervalued.
Result: Fair Value of $172 (UNDERVALUED)
Still, the story around CBRE Group can change quickly if interest rate moves continue to weigh on deal volumes or if fundraising at its investment management arm remains soft.
Find out about the key risks to this CBRE Group narrative.
Another View: What CBRE Group's P/E Is Really Saying
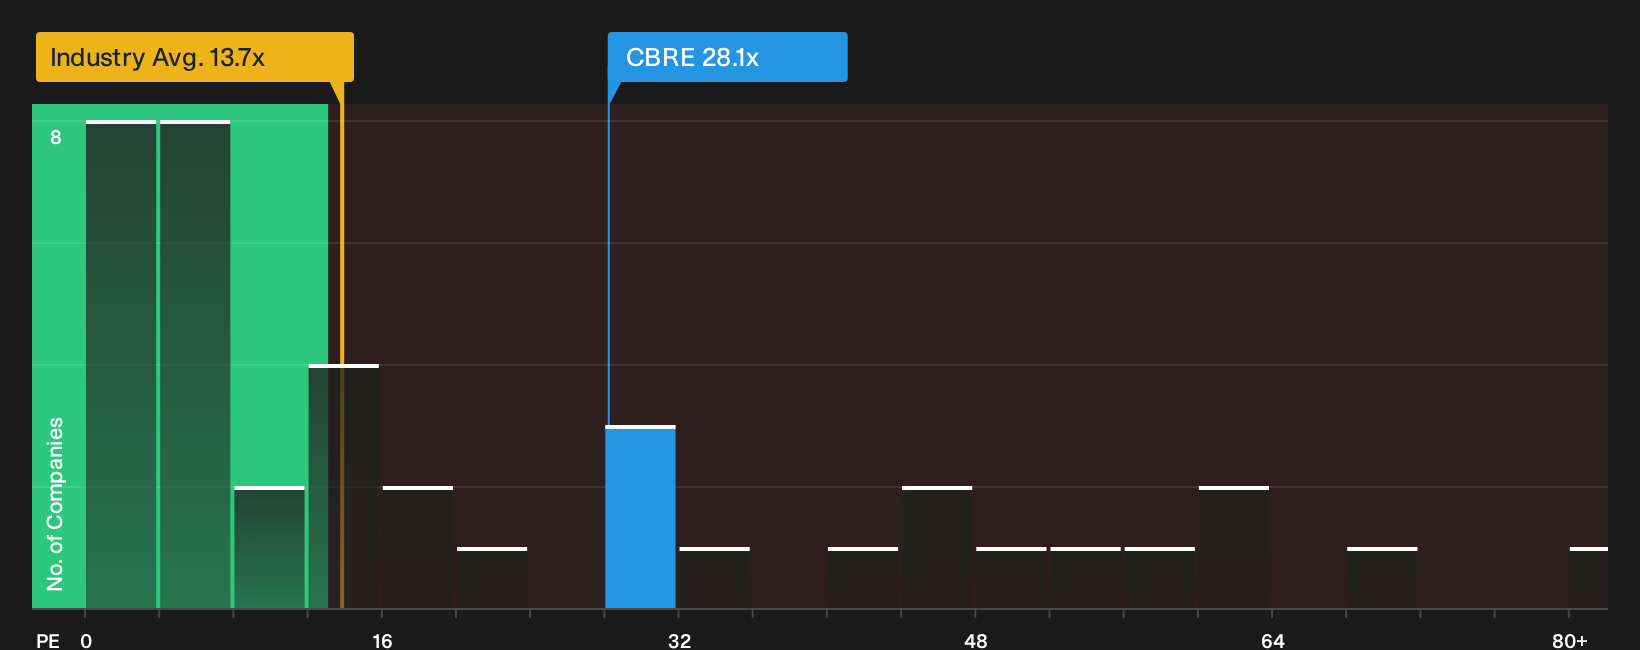
There is a catch. CBRE Group screens as undervalued on fair value estimates, yet the stock trades on a P/E of 28.1x, which is roughly double the US Real Estate industry at 14.1x and still below its own fair ratio of 32.1x. This leaves investors to decide whether that gap signals extra upside or valuation risk.
For a closer look at how that earnings multiple could evolve if sentiment or sector conditions shift, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages so far on CBRE Group's valuation and sentiment make this a good moment to check the underlying data yourself rather than rely on headlines. To balance the upside arguments against the concerns flagged around the business, review the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond CBRE Group?
If CBRE Group has your attention, do not stop here. Fresh watchlist candidates often emerge where quality, value, and resilience quietly line up together.
- Target robust balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) before the next bout of volatility narrows your choices.
- Pinpoint potential value opportunities by running through the 35 high quality undervalued stocks so you are not relying on headlines to surface mispriced businesses.
- Focus on resilience first by reviewing the 30 resilient stocks with low risk scores and keep downside firmly on your radar while you hunt for upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com