
What Herbalife Doubters Got Wrong
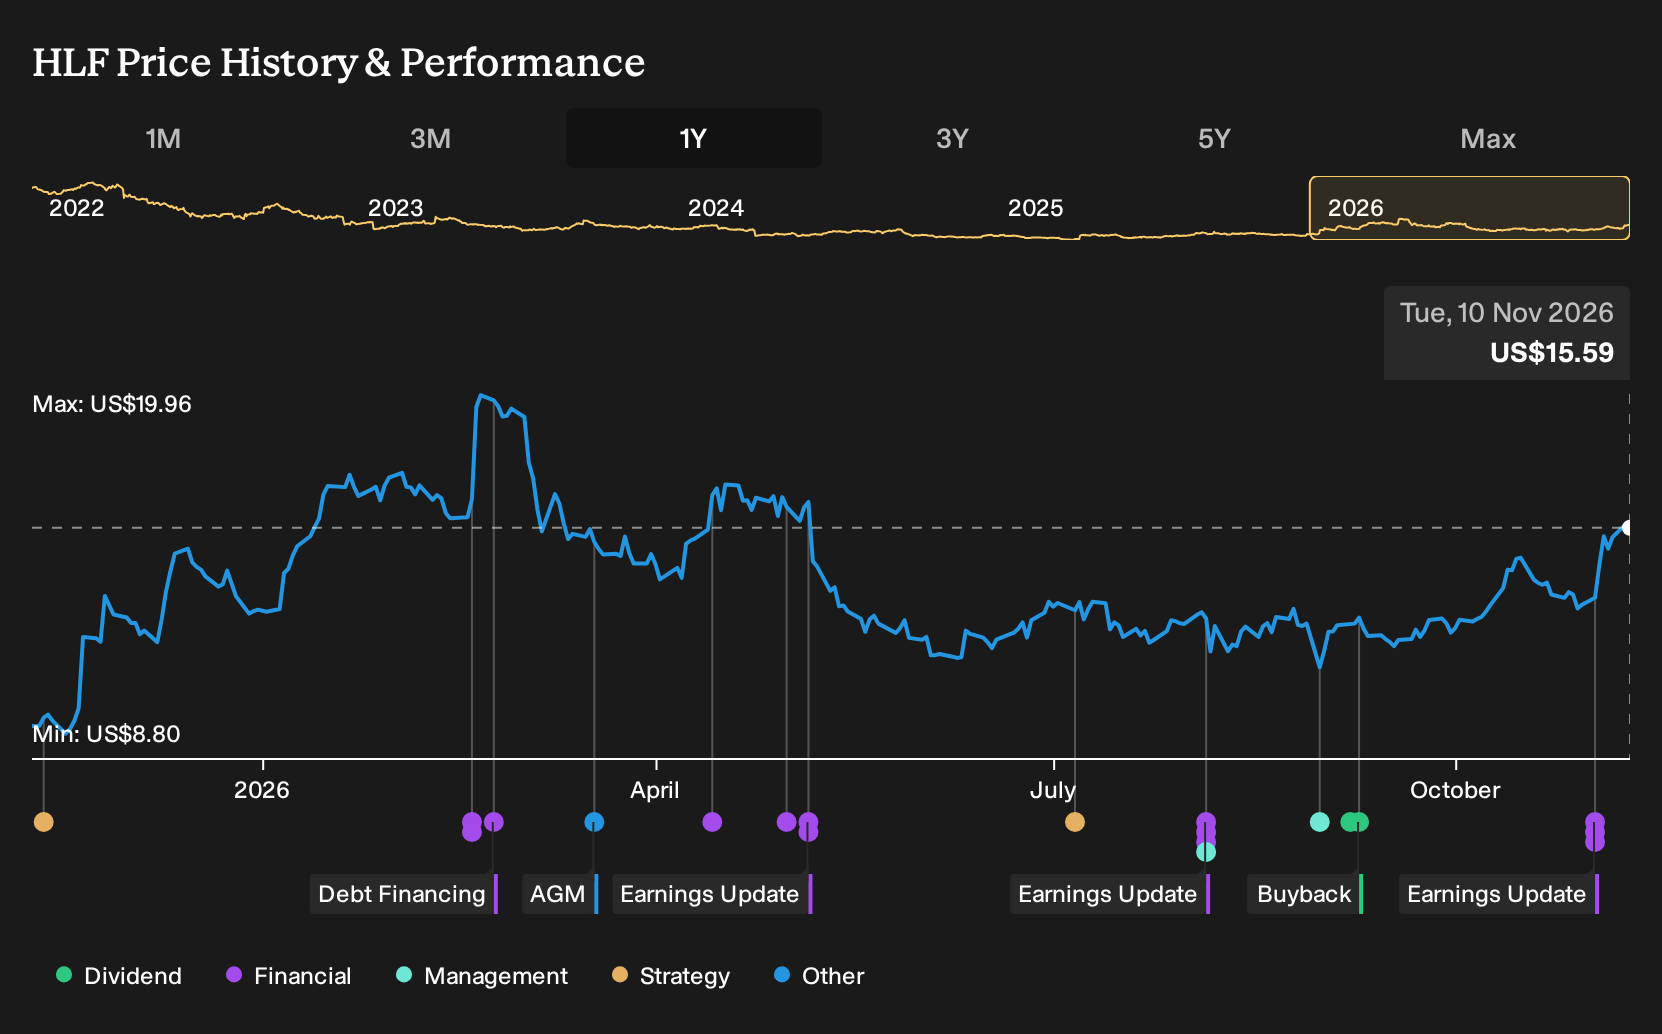
Herbalife’s year turned on very specific moves, such as the US$1.45b refinancing that swapped near term loans for longer dated 7.750% notes due 2033 and cut expected annual cash interest by about US$45m. For Herbalife shareholders, the return over the past year was 72.1%, including dividends. If you had been deciding whether to buy before that refinancing was announced, what exactly did you need to believe about this business model and its digital nutrition pivot?
The easy part of this move is behind Herbalife. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Two Herbalife Stories Investors Had To Hold In Their Heads
The shares cost US$9.05 at the start of the period, so anyone looking at Herbalife then had to decide which future felt more plausible.
The bullish story pointed to a Fair Value of US$11, a price implied by expectations that Pro2col and AI-driven personalization would revive the global distributor base and help recurring digital nutrition sales scale.
The bearish view sat at a Fair Value of US$7, built on concern that tighter multi-level marketing regulation and mounting debt could restrict market access and strain future earnings power.
What The Herbalife Results Actually Tested
Herbalife’s refinancing and digital nutrition pitch met hard numbers when Q3 2026 revenue reached US$1,350.2m versus US$1,273.7m a year earlier, and net income rose to US$58.8m from US$43.2m as net margin moved from 3.4% to 4.4%. That lent weight to the optimistic “revitalisation” story, although softer EBITDA guidance and cash flow pressure kept the cautious case alive.
The real lesson is simple. When a business sells a digital pivot and margin story, you test it against future revenue, net income and net margin lines, not just headline growth narratives or new-product headlines.
What Herbalife’s 72% Run Already Prices In
Herbalife now trades at US$15.59, well above where the bearish analyst Narrative on Simply Wall St places its Fair Value. That Narrative views Fair Value as sitting below the market price.
The same Narrative leans on real product momentum but questions whether execution in India, technology spend and leadership change can sustain margins and cash generation at today’s valuation.
"The primary requirement for success is that Herbalife executes its personalized, data-enabled nutrition and technology programs while managing emerging market mix shifts, India GST headwinds, and leadership transitions without eroding margins or cash generation."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Herbalife And A Different Kind Of Repeat Sale
Herbalife asks you to think about recurring digital nutrition orders. One step away, another business leans on repeat demand too.
Instead of shakes and supplements, it focuses on cleaning, hygiene and household basics. Those goods are used up constantly, then reordered again.
Management there is pushing a broader health and hygiene range into homes and workplaces. The goal is simple: stay present whenever people reach for everyday protection.
Recurring use can also shape how cash comes in and gets redeployed. If refill and repeat volumes remain steady, capital allocation choices start to look different.
That argument has a Narrative and a number behind it. → See the company one Narrative values 22% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com