
Are Wall Street Analysts Predicting KKR Stock Will Climb or Sink?
With a market cap of $88 billion, KKR & Co. Inc. (KKR) is a prominent global investment firm providing alternative asset management, capital markets, and insurance solutions. With a patient and disciplined investment approach, the company seeks to generate attractive returns through strategic investments in private equity, credit, real assets, and insurance solutions. KKR is headquartered in New York City and operates across major financial markets globally.
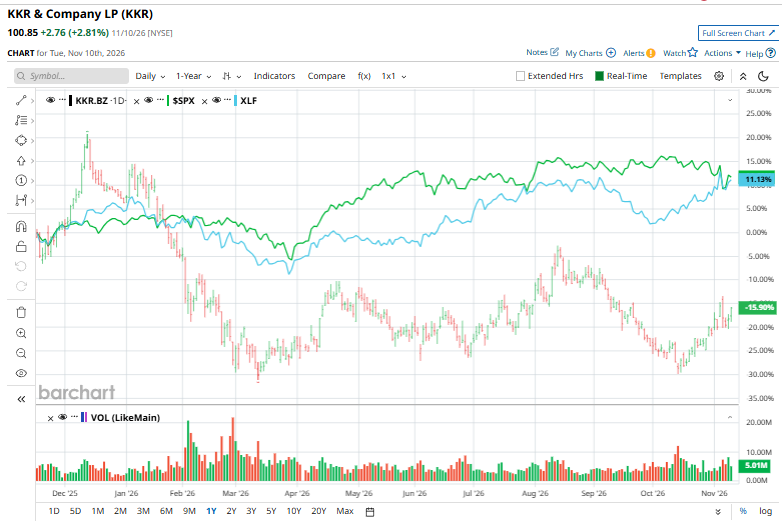
Shares of KKR have lagged behind the broader market over the past 52 weeks. KKR stock has decreased 16% over this time frame, while the broader S&P 500 Index ($SPX) has returned 10.1%. Moreover, shares of the company are down 20.9% on a YTD basis, compared to the SPX’s 9.9% gain.
Focusing more closely, shares of the asset manager have underperformed the State Street Financial Select Sector SPDR ETF’s (XLF) 10% rise over the past 52 weeks and 6.4% YTD return.
KKR shares rose 1.7% after the company reported strong third-quarter fiscal 2026 results on Nov. 9, beating analyst expectations for adjusted earnings and delivering record quarterly earnings across its key operating measures for the second consecutive quarter. While Revenue declined 17.4% year over year to $4.56 billion, adjusted EPS rose 26.2% to $1.78. Its asset management business remained a key earnings driver, while AUM expanded 11% to $804.4 billion, supported by continued fundraising and investment activity.
For the fiscal year ending in December 2026, analysts expect KKR’s EPS to increase 74.2% year-over-year to $7.35. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing on another occasion.
Among the 22 analysts covering the stock, the consensus rating is a “Strong Buy.” That’s based on 14 “Strong Buy” ratings, three “Moderate Buy,” and five “Holds.”
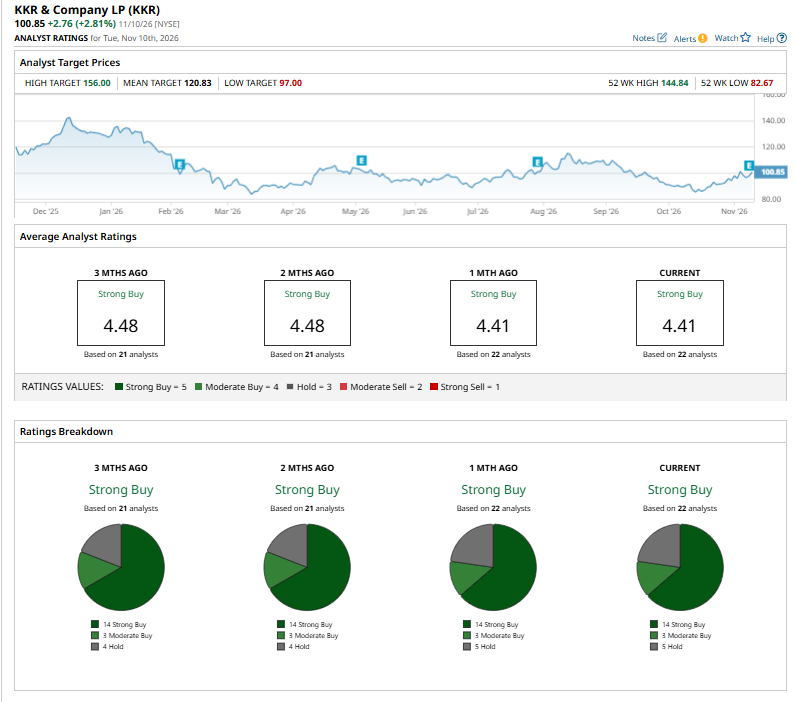
This configuration has remained unchanged over the past three months.
On November 10, Wells Fargo raised its price target on KKR to $105 from $97 while maintaining an “Equal-Weight” rating. The firm slightly increased its 2027 EPS estimate to $7.24 from $7.20, reflecting expected insurance gains and a lower share count, which should offset softer base management fees and moderating transaction fees. Wells Fargo also anticipates a $200 million insurance-segment realization in Q1 2027. However, it trimmed its 2028 EPS estimate to $8.33 from $8.35, citing lower base fees, partially offset by a reduced share count and improved returns on equity in the insurance business.
The mean price target of $120.83 represents a nearly 19.8% premium to KKR’s current price levels. The Street-high price target of $156 suggests a 54.7% potential upside.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.