
Do Wall Street Analysts Like D.R. Horton Stock?
D.R. Horton, Inc. (DHI) operates as a homebuilding company. Valued at $41.9 billion by market cap, the company constructs and sells single-family homes designed primarily for the entry-level and move-up markets. DHI also provides mortgage financing and title agency services to homebuyers.
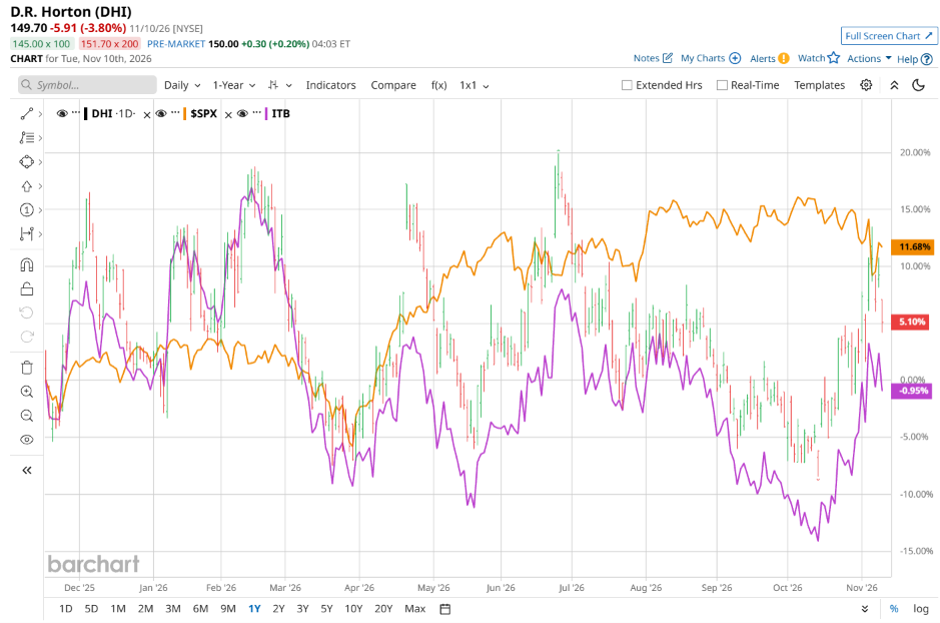
Shares of this leading homebuilder have underperformed the broader market over the past year. DHI has gained 3.6% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. In 2026, DHI stock is up 3.9%, compared to the SPX’s 9.9% rise on a YTD basis.
Narrowing the focus, DHI’s outperformance is apparent compared to the iShares U.S. Home Construction ETF (ITB). The exchange-traded fund has declined about 2.7% over the past year. Moreover, the stock’s single-digit returns on a YTD basis outshine the ETF’s marginal losses over the same time frame.
DHI delivered mixed results as elevated mortgage rates and affordability pressures weighed on demand, causing net sales orders and gross margins to trend below targets. Despite a year-on-year revenue decline that beat expectations, management noted that rising rates and cautious consumer sentiment increased fourth-quarter pressure and cancellation rates. To sustain absorption, the company leveraged community-level pricing adjustments, mortgage rate buydowns, and a strategic shift toward smaller homes and attached products. While near-historic construction cycle times and strong operational discipline preserved capital efficiency, the business faced sequential stick-and-brick cost inflation and a multifamily rental impairment charge. Looking to fiscal 2027, DHI issued wider guidance ranges to account for ongoing demand uncertainty, while remaining positioned to leverage its scale and balance sheet strength to consolidate market share.
On Oct. 29, DHI shares closed up by 2.5% after reporting its Q4 results. Its EPS of $2.67 missed Wall Street expectations of $3.03. The company’s revenue was $9.4 billion, surpassing Wall Street forecasts of $9 billion. DHI expects full-year revenue in the range of $30 billion to $32 billion.
For fiscal 2027, ending in September, analysts expect DHI’s EPS to grow 3.7% to $10.48 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
Among the 23 analysts covering DHI stock, the consensus is a “Hold.” That’s based on five “Strong Buy” ratings, 15 “Holds,” and three “Strong Sells.”
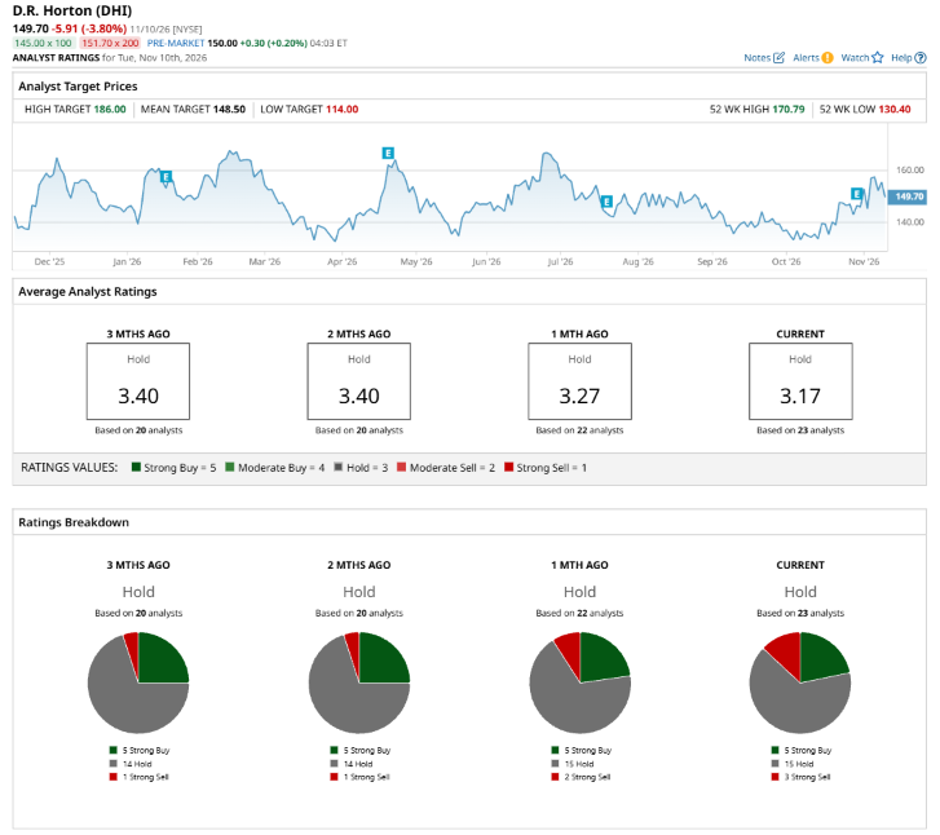
This configuration is less bearish than a month ago, with two analysts suggesting a “Strong Sell.”
On Oct. 30, Jade Rahmani from KBW maintained a “Hold” rating on DHI, with a price target of $150, implying a potential marginal upside from current levels.
While DHI currently trades above its mean price target of $148.50, the Street-high price target of $186 suggests an upside potential of 24.2%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.