
Japan Hotel REIT Investment (TSE:8985) Following Its Dividend Announcement Looks Pricey Despite DCF Support
Japan Hotel REIT Investment (TSE:8985) has put income front and center with an announced annual dividend of ¥5,811 per unit, scheduled for payment on March 19, 2027.
Recent price action has been quietly positive, with Japan Hotel REIT Investment’s share price at ¥85,200 after a 1 month share price return of 7.58% and a 3 year total shareholder return of 42.40%, even though the 1 year total shareholder return has been roughly flat.
Scan income-focused real estate plays moving on dividend news by checking the hand-picked 29 dividend fortresses alongside Japan Hotel REIT Investment.
The recent rally and upcoming ¥5,811 payout put Japan Hotel REIT Investment in a stronger spotlight. After this move, does the balance of income and price risk still lean in favour of new buyers, or not?
Preferred Price-to-Earnings of 19.2x: Is it justified for Japan Hotel REIT Investment?
On valuation, Japan Hotel REIT Investment is carrying a P/E of 19.2x, which positions the ¥85,200 unit price above several reference points and suggests investors are paying a premium versus peers.
The P/E ratio compares the current unit price to earnings per unit. For a REIT focused on hotel assets, it reflects what the market is willing to pay for each yen of profit given its income profile, asset base, and perceived stability.
For Japan Hotel REIT Investment, this premium looks demanding. High quality earnings and a history of earnings growth sit alongside forecasts that call for earnings to decline by an average of 4% per year over the next 3 years. This means the current P/E embeds a relatively optimistic view of future profitability despite those projections.
The comparison with benchmarks is even starker. The 19.2x P/E is higher than the estimated fair P/E of 18.1x, higher than the peer average of 15.8x, and well above the 12.3x average for the global Hotel and Resort REITs industry. As a result, the multiple is rich both versus what the fair ratio suggests the market could move toward and versus similar securities.
Explore the SWS fair ratio for Japan Hotel REIT Investment.
Result: Price-to-Earnings of 19.2x (OVERVALUED)
Still, the annual decline in net income and a value score of 1 signal that Japan Hotel REIT Investment’s premium valuation could come under pressure.
Find out about the key risks to this Japan Hotel REIT Investment narrative.
Another View: What The SWS DCF Model Says About Japan Hotel REIT Investment
The rich 19.2x P/E suggests investors are paying up for Japan Hotel REIT Investment, yet the SWS DCF model points the other way, with an estimated future cash flow value of ¥103,484 per unit versus a market price of ¥85,200. This implies the units trade below that cash flow estimate. Which signal do you give more weight to?
Look into how the SWS DCF model arrives at its fair value.
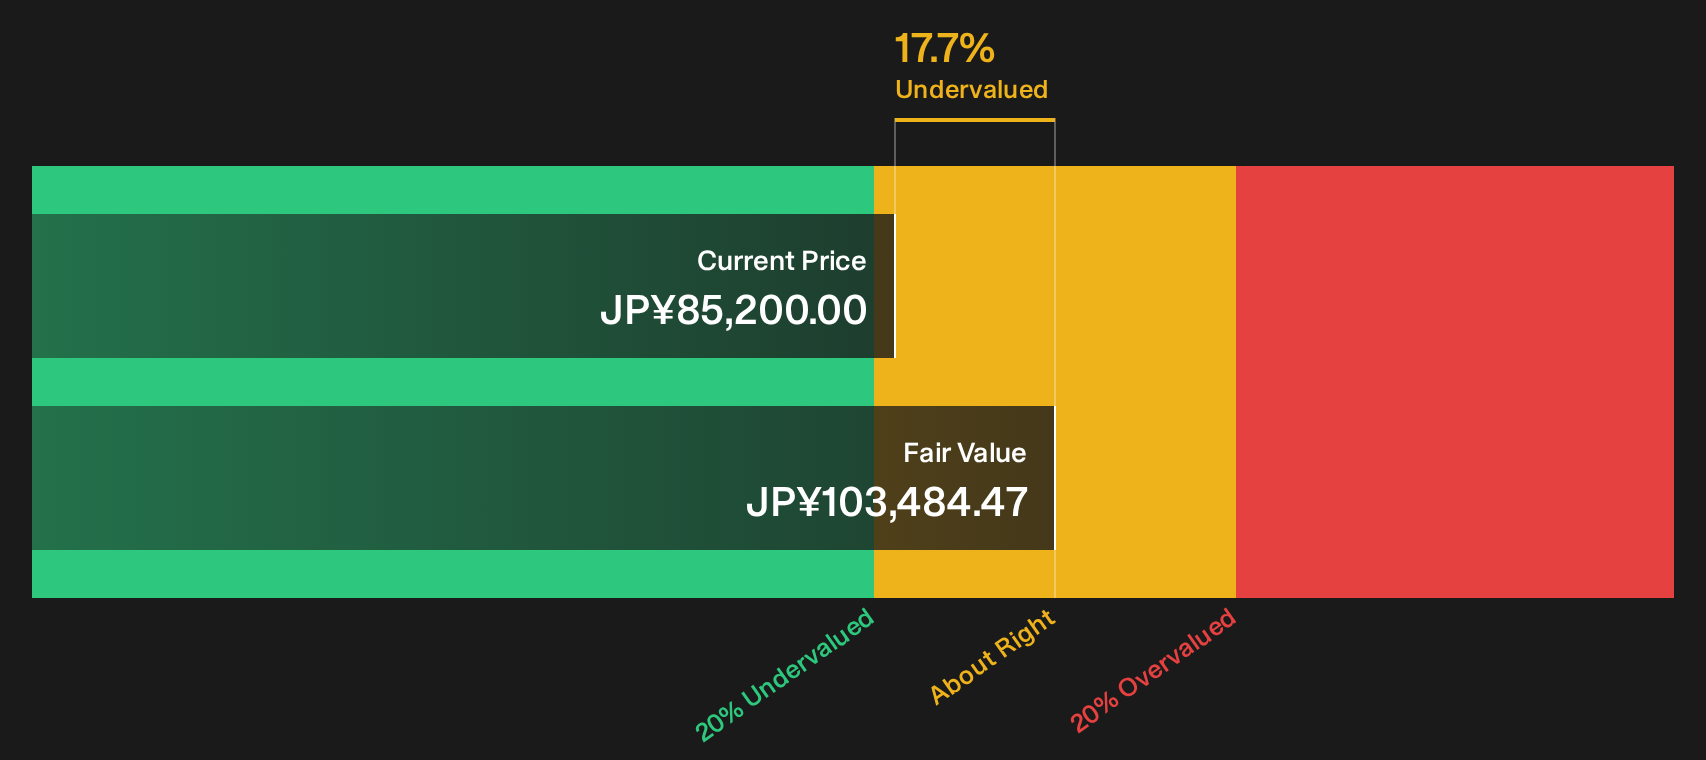
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Hotel REIT Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 23 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Signals on Japan Hotel REIT Investment appear mixed so far, with valuation looking rich but also support from the DCF work. Consider reviewing the full picture promptly and weigh both the potential upside and the flagged issues by checking the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Japan Hotel REIT Investment?
If Japan Hotel REIT Investment has sharpened your focus on valuation and income, do not stop here. Use a few targeted screens to widen your opportunity set intelligently.
- Target potential mispricings by running through a curated pool of companies that combine quality fundamentals with attractive valuations using the 23 high quality undervalued stocks.
- Strengthen your income stream by scanning for dependable payouts and higher yields with the help of the 29 dividend fortresses.
- Dial back risk by filtering for businesses with sturdier finances using a focused list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com