
Why Zhejiang Expressway (SEHK:576) Is Back In The Spotlight
Zhejiang Expressway (SEHK:576) just posted nine-month 2026 earnings that show higher sales at CNY 15,972.35 million, while net income and earnings per share edged lower compared with the same period a year earlier.
The earnings release lands after a mixed price stretch for Zhejiang Expressway, with the share price at HK$6.385 showing a 30 day share price return of 5.28% and a year to date share price decline of 11.20%. At the same time, the 3 year total shareholder return of 50.28% points to stronger longer run performance and suggests recent momentum has been rebuilding after weaker one year total shareholder returns.
Compare the returns profile of Zhejiang Expressway with its peers and identify other steady compounders with a similar mix of earnings resilience and volatility control in the 208 resilient stocks with low risk scores.
Bulls see Zhejiang Expressway’s mix of steady toll roads and securities income, together with a recent share price rebound, as support for value. Bears point to softer earnings per share. Which case does current pricing lean toward?
Preferred P/E of 6.3x for Zhejiang Expressway: Is it justified?
On Simply Wall St’s numbers, Zhejiang Expressway trades on a P/E of 6.3x, while the shares last closed at HK$6.385 and screen as good value against both peers and its own fair ratio.
The P/E multiple compares the current share price with earnings per share. For a toll road and securities operator like Zhejiang Expressway, it is a quick way to see how much investors are paying for each unit of profit, especially when earnings are already established rather than highly speculative.
On this measure, the stock looks inexpensive. The current 6.3x P/E is well below the Asian Infrastructure industry average of 13.2x. This implies the market is pricing Zhejiang Expressway’s earnings at a sizeable discount to sector peers. Against an estimated fair P/E of 10.2x, the gap is also wide, which points to a level the market could potentially move towards if sentiment and fundamentals stay aligned with current expectations.
Explore the SWS fair ratio for Zhejiang Expressway.
Result: Price-to-Earnings of 6.3x (UNDERVALUED)
Still, softer earnings per share and reliance on both toll traffic and securities activity could quickly challenge the idea that Zhejiang Expressway deserves a higher P/E multiple.
Find out about the key risks to this Zhejiang Expressway narrative.
Another view on Zhejiang Expressway’s value
The P/E picture presents Zhejiang Expressway as inexpensive. Simply Wall St’s DCF model goes further and estimates fair value at HK$11.05 per share versus the current HK$6.385 price. That implies a wide gap. Is the discount compensation for risk or an opening for patient capital?
Look into how the SWS DCF model arrives at its fair value.
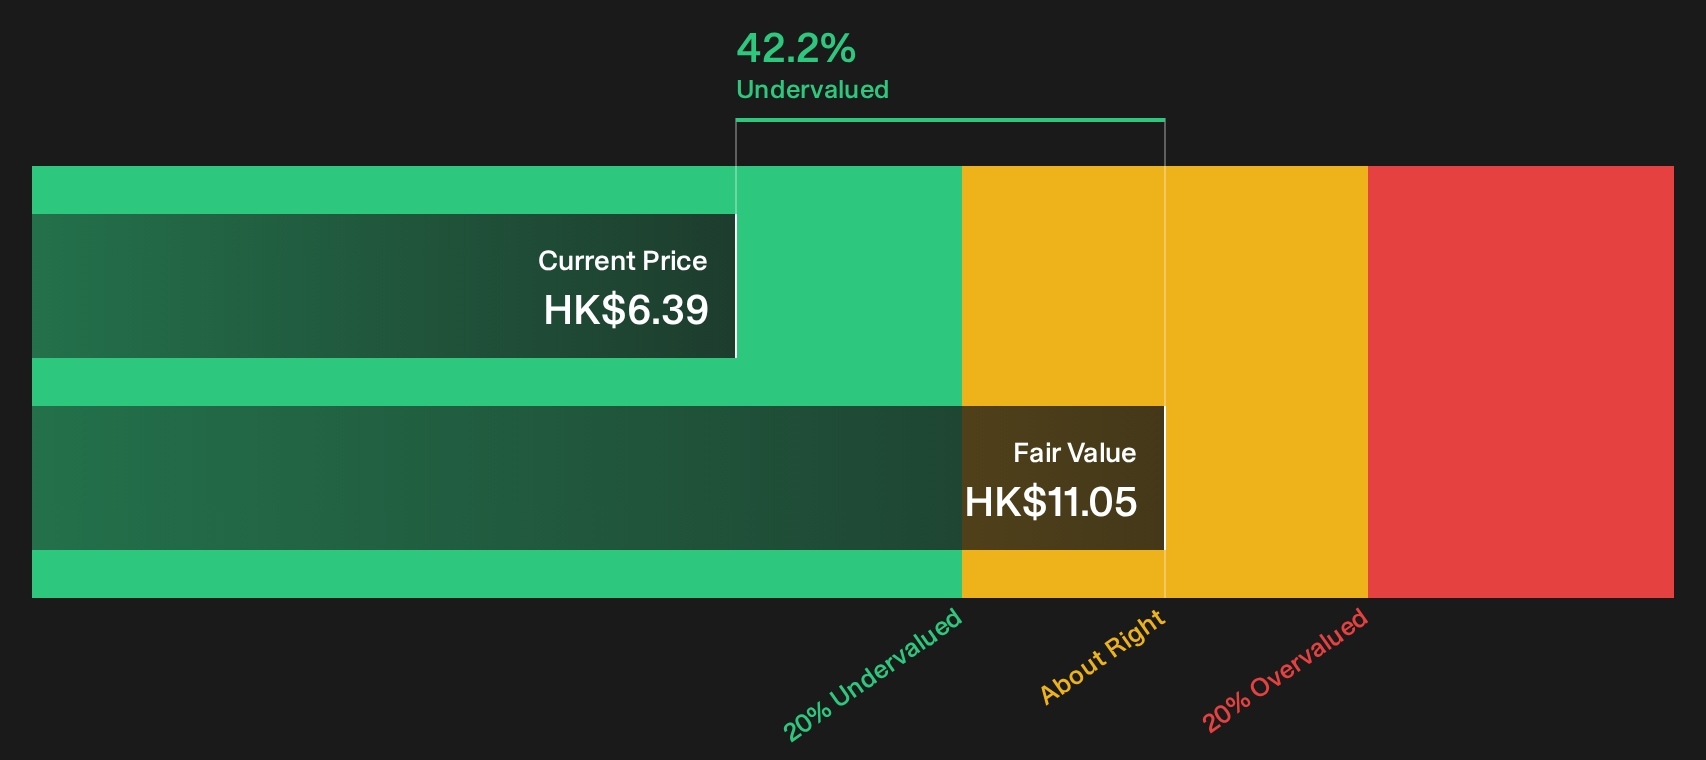
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zhejiang Expressway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 200 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Zhejiang Expressway clearly splits opinion, with softer earnings per share on one side and valuation support plus a long run return cushion on the other. Act quickly, review the figures for yourself and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Zhejiang Expressway?
If Zhejiang Expressway has sharpened your focus on value and risk, do not stop here. The right watchlist gives you options when the market shifts.
- Target high potential turnarounds by scanning for tightly run smaller companies using the 122 elite penny stocks with strong financials.
- Zero in on potential bargains backed by solid fundamentals with the 200 high quality undervalued stocks.
- Prioritise resilience and capital protection by leaning on the list of solid balance sheet and fundamentals (194 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com