
Should Raised Guidance Require Action From Steven Madden (SHOO) Investors?
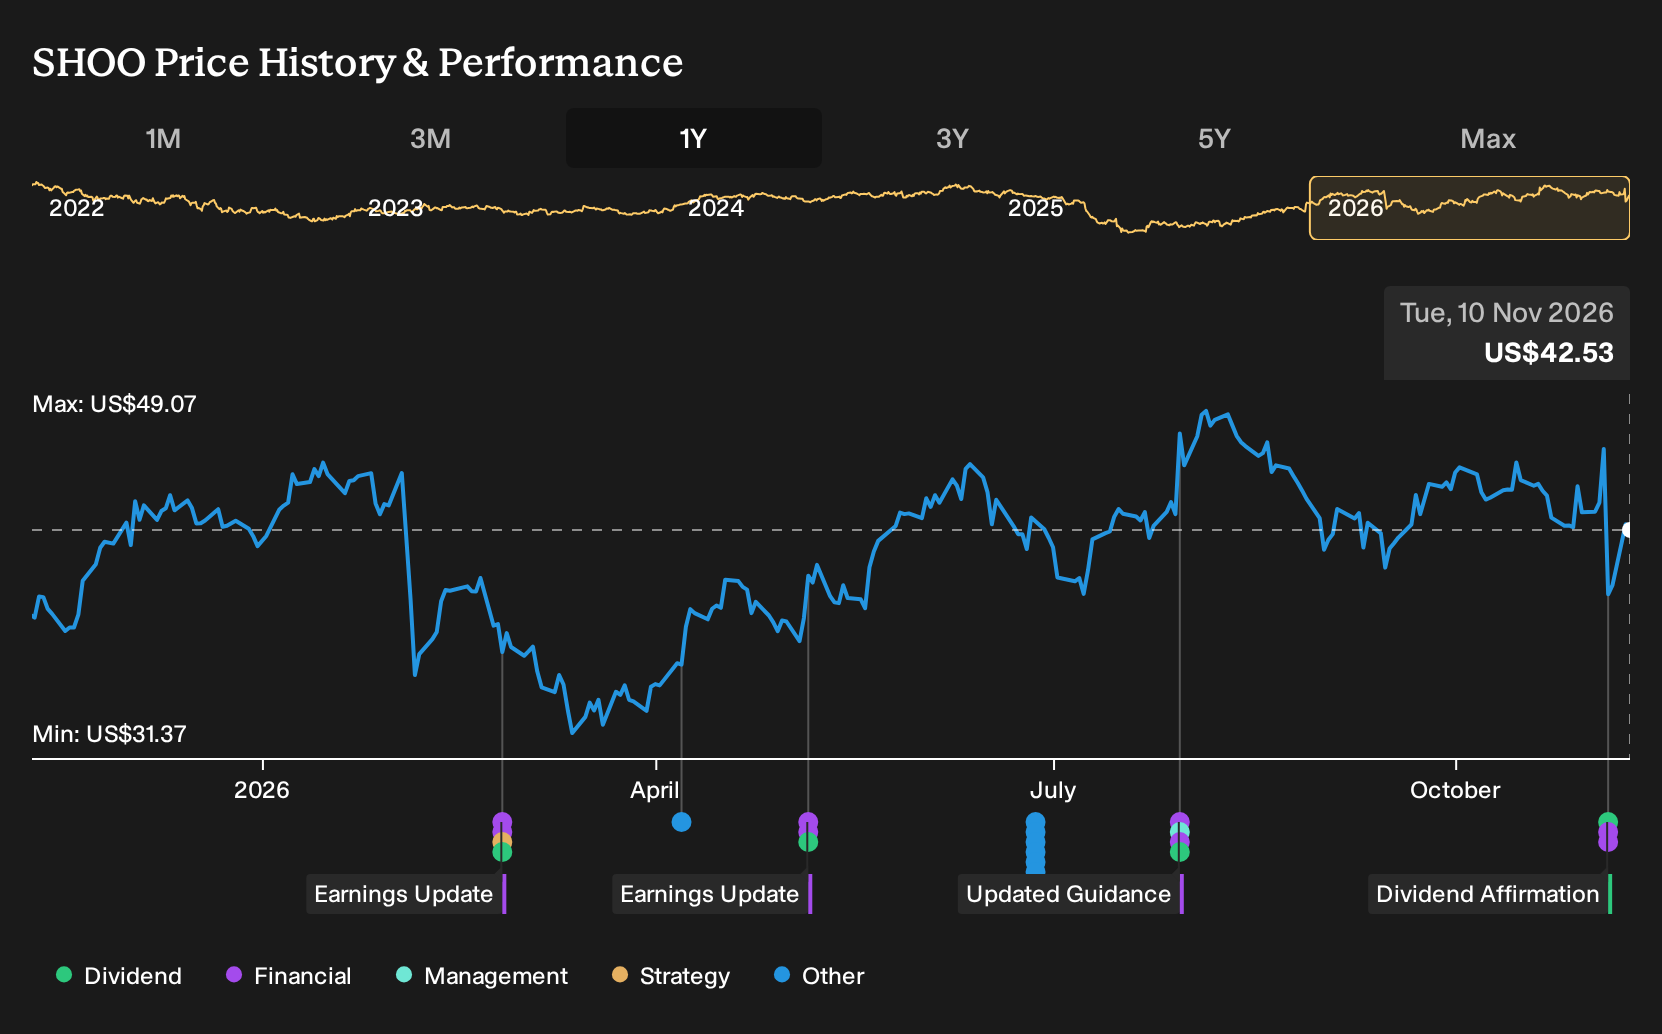
- Steven Madden reported third quarter 2026 revenue of US$772.61 million and net income of US$52.42 million, raised full year 2026 revenue and EPS guidance, and affirmed a quarterly dividend of US$0.21 per share payable in December 2026.
- The latest results highlight strong demand in branded footwear, denim, and handbags. The updated outlook underscores management's focus on earnings quality despite tariff, freight, and private label pressures.
- Investors will now assess how Steven Madden's raised full year 2026 guidance may influence the existing investment narrative around branded growth.
Steven Madden Investment Narrative Recap
To stay comfortable owning Steven Madden, you need to believe the branded engine in footwear, handbags, and denim can keep pulling harder than the private label drag. The raised 2026 revenue and EPS guidance, as summarised in the analyst consensus Narrative on Simply Wall St, supports that branded focus but does not remove tariff or freight uncertainty.
The most immediate catalyst remains operational execution in the higher margin direct to consumer and branded wholesale channels, especially as private label is expected to be weaker. The biggest near term risk is that tariffs or supplier costs move above what guidance assumes, which could pressure margins even if demand stays solid.
The dividend affirmation at US$0.21 per share for December 2026 is the announcement that ties closest to this earnings story. It sits alongside guidance that now calls for 2026 revenue to rise 12% to 13% versus 2025 and EPS of US$2.58 to US$2.63, which describes how management currently presents the business.
For you, that pairing of higher guidance and a maintained payout places more focus on cash generation and consistency. The catalysts around digital direct to consumer growth, Kurt Geiger rollout, and international expansion matter more if Steven Madden can keep funding brand investment and tariffs while still covering that dividend and any buybacks.
Steven Madden's current earnings of US$175.2 million are projected by analysts to reach US$250.2 million by 2029, which implies a revenue path that leads to US$3.5b of sales in that same year, based on an assumed 6.9% yearly increase in revenue and an earnings uplift of about US$75 million from today's level.
Uncover why Steven Madden's fair value points to a 17% potential upside to its current price, a discount that could close faster than many investors expect.
Exploring Other Perspectives
One alternate view places less emphasis on Steven Madden’s raised guidance and dividend and focuses more on free cash flow quality. The most cautious analysts were previously assuming roughly US$3.4b of revenue and US$250.4 million of earnings by 2029, yet assigning only a US$36.1 price target. That gap shows how sharply opinions can differ, so it makes sense to compare several narratives before deciding how this new information might influence your own view.
Explore another Steven Madden fair value estimate, including one estimate that suggests it could be worth just $49.67.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Steven Madden research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Steven Madden. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Steven Madden's overall financial health at a glance.
Looking for more investment ideas beyond Steven Madden?
Once you have a view on Steven Madden, it helps to line it up against a broader watchlist so you can see where risk, income, and balance sheet strength really stack up.
- If resilience matters most to you, focus on companies that pair durable earnings with steadier volatility by starting with a 30 resilient stocks with low risk scores.
- For investors who want strong balance sheets to back up the story, use the Simply Wall St screener to filter a list of solid balance sheet and fundamentals (24 results).
- If you are hunting for underfollowed opportunities with sound fundamentals, expand your search with a 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com