
Is CeriBell (CBLL) Undervalued Following Its Higher 2026 Guidance And Delirium Launch?
CeriBell (CBLL) just raised its full year 2026 revenue outlook to US$115 million to US$117 million, while also rolling out its FDA cleared delirium monitoring solution with Medicare add on reimbursement support.
The revenue guidance upgrade and delirium launch arrive after an eventful stretch for CeriBell, with the stock now trading at US$27.48. The 30 day share price return of 16.29% and year to date gain of 29.01% suggest momentum has been building, while the 1 year total shareholder return of 119.49% shows how strongly recent developments and changing expectations around growth and risk have fed into longer term performance.
Scan beyond CeriBell and compare its momentum and AI driven healthcare theme with a curated group of 36 healthcare AI stocks that are also drawing attention around brain and diagnostics technology.
The question now is whether CeriBell’s sharp re rating mainly reflects sturdier fundamentals after higher guidance and the delirium launch, or whether sentiment has simply raced ahead of what the numbers support.
Most Popular Narrative: 7% Undervalued
CeriBell’s analyst consensus Narrative on Simply Wall St pegs fair value at about $29.57 per share, compared with the recent $27.48 close. This frames the latest move as pricing in less than the full upside that analysts model.
Development of additional AI algorithms for conditions such as delirium and stroke on top of a growing installed base transforms the platform from a single indication tool into a multi indication neuromonitoring system, potentially expanding the addressable market and supporting durable revenue diversification.
See why 2 investors see CeriBell as 7% undervalued.
Result: Fair Value of $29.57 (UNDERVALUED)
Still, the CeriBell story carries clear pressure points if hospital protocol updates slow, or if ongoing losses and spending stretch out the path to cash flow breakeven.
Find out about the key risks to this CeriBell narrative.
Another View: What CeriBell’s Sales Multiple Is Telling You
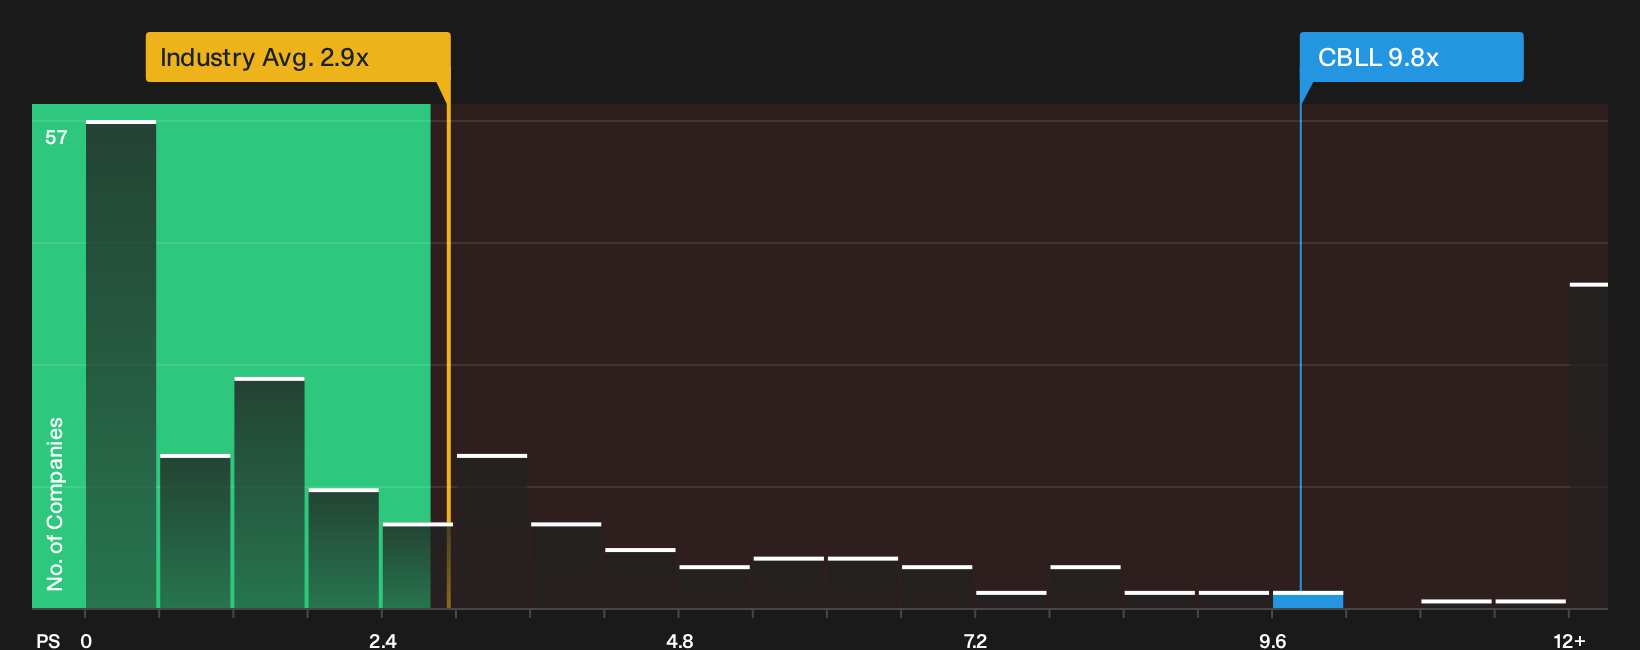
The analyst fair value of $29.57 suggests CeriBell looks modestly undervalued. Its P/S of 9.8x tells a different story. That level is more than 3x the US Medical Equipment industry at 3x and well above the 7.5x fair ratio that Simply Wall St’s model points to.
Paying well ahead of both peers and the fair ratio can work if the growth story keeps meeting expectations. It also raises the risk that any slip in execution, policy support, or hospital budgets could see the valuation compress back toward that 7.5x anchor.
Put simply, the share price currently bakes in a lot of belief in the rapid EEG and delirium opportunity. The open question is whether you think today’s premium multiple is a fair trade off for that growth profile or whether the analyst target already captures most of what you are comfortable assuming.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around CeriBell leaves you on the fence, move quickly to review the underlying data and pressure test your own stance. To weigh both sides in one place, start with the 1 key reward and 2 important warning signs.
Looking for more ideas beyond CeriBell?
CeriBell might be front of mind today, but your next strong idea could sit in a very different corner of the market, so do not stop the search here.
- Target potential mispricing by scanning a curated set of quality companies through the 35 high quality undervalued stocks and compare how their fundamentals stack up.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you focus on sturdier financial footing.
- Spot earlier stage potential by sorting through a 10 elite penny stocks with strong financials that filters for smaller businesses with stronger underlying metrics than the crowd.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com