
What Is Drawing Attention To Constellation Software (TSX:CSU)?
Constellation Software (TSX:CSU) just paired a fresh earnings update with a confirmed dividend, giving investors new numbers to assess both the company’s acquisition driven model and its cash return policy.
Over the past month, Constellation Software’s 13.89% 1 month share price return and 11.24% 3 month share price return point to building momentum at a CA$3,421.12 share price, while a 5.24% 1 year total shareholder return shows more measured progress when dividends are included.
Compare Constellation Software’s acquisition-led model with other vertical market and recurring revenue plays by scanning our curated list of 7 high quality undiscovered gems that might still be flying under the radar.
The sharp move in Constellation Software after its latest results puts a simple fork in the road for investors. Is most of the easy upside already used up, or do the current fundamentals still leave clear room on the table?
Most Popular Narrative: 8.1% Undervalued
Against a CA$3,421.12 share price, the leading narrative on Constellation Software pegs fair value at CA$3,722.17, implying some remaining upside on the DCF work behind that view. According to Aequitas, an investor in the Simply Wall St Community who set out that narrative, the appeal rests far more on capital recycling than headline revenue growth.
The real value driver is not organic growth but the combination of sticky, stable underlying businesses and disciplined capital reinvestment at high returns. Following founder Mark Leonard's departure and a roughly 50% pullback from highs, this offers an entry into a proven model at a meaningfully reduced price.
See why 16 investors see Constellation Software as 8% undervalued.
Result: Fair Value of CA$3,722.17 (UNDERVALUED)
Still, two pressure points could trip up that undervaluation story: leadership change under Mark Miller with a shorter capital allocation record, and rising acquisition prices compressing future returns.
Find out about the key risks to this Constellation Software narrative.
Another View: Constellation Software Looks Expensive On Earnings
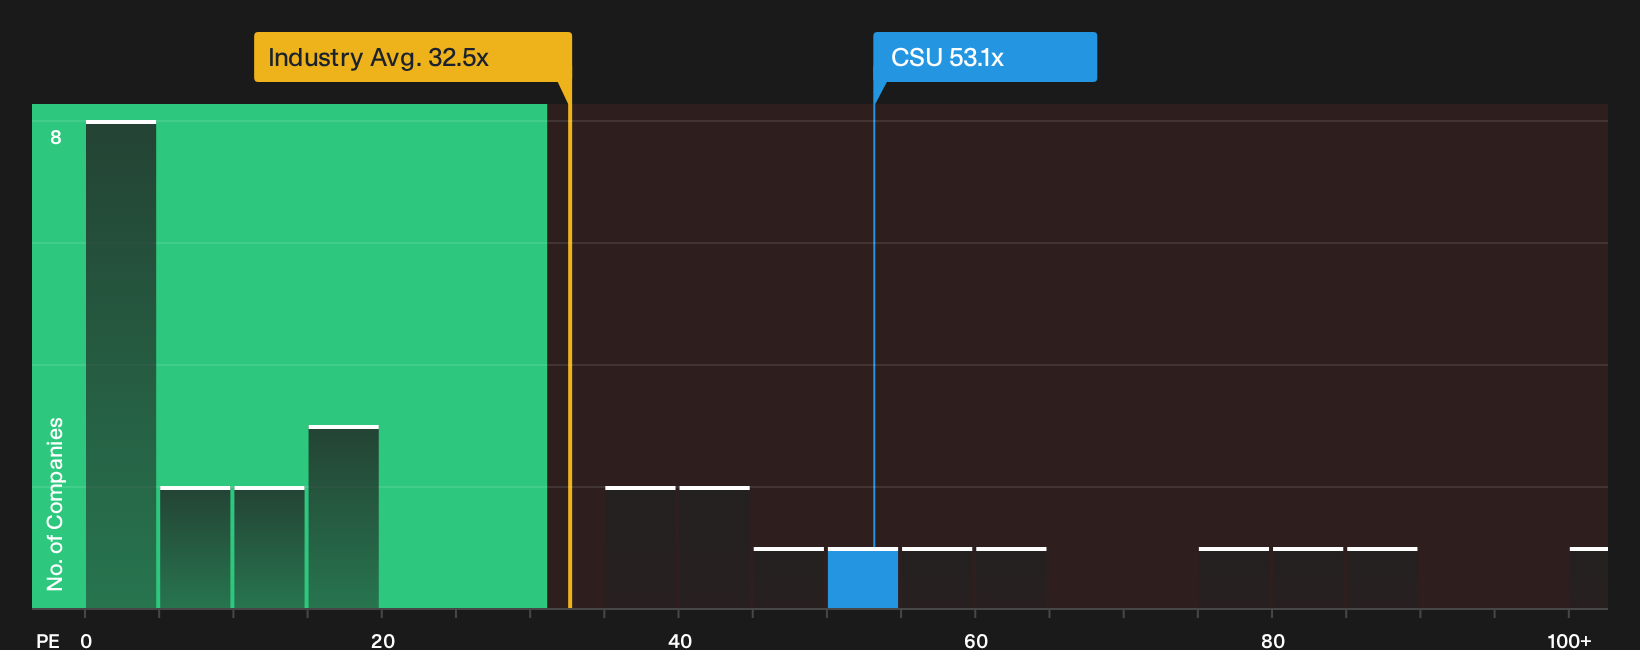
On cash flows, the SWS DCF model flags Constellation Software as materially undervalued at a CA$3,421.12 share price. On earnings, the picture flips. The stock trades on a 53.1x P/E, well above the 32.5x North American software average, the 42.5x peer group, and the 35.8x fair ratio the market could move towards. That gap raises a simple question for investors: Is the DCF right about future cash generation, or is the current P/E telling you to demand a wider margin of safety?
For a deeper look at how this earnings based view stacks up against other approaches, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and fundamentals are exactly when you should inspect the numbers yourself and decide how Constellation Software really stacks up. Move quickly, weigh the concerns and potential upside in context, and ground your own view in the 4 key rewards and 2 important warning signs.
Looking for more Constellation Software sized ideas?
If Constellation Software has sharpened your focus on quality, do not stop here. Broader idea flow helps you stress test every decision before committing capital.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (5 results) that keeps financial strength front and centre.
- Hunt for mispriced quality by reviewing a 5 high quality undervalued stocks that filters for companies where fundamentals and market pricing appear out of sync.
- Lock in income focused opportunities by using a 3 dividend fortresses built around higher yield payouts with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com