
Western Digital (WDC) Stock Looks Undervalued Even After A 7x Run
Western Digital has delivered a huge multi‑year share price run, yet the recent pullback and fresh headlines now put a simple question in front of investors: Is the current valuation still supported by what the business is earning?
- Over the past 3 years the stock has gained roughly 7x, which puts a lot of weight on the idea that its profit engine can keep backing up that kind of move.
- Calls from some US lawmakers to slow AI data center build outs, plus a shareholder investigation into potential fiduciary issues, could influence how investors think about future storage demand, earnings durability and the risk premium they apply to Western Digital's cash generation.
- There is a second opinion on Western Digital worth weighing. See what analysts think Western Digital's shares could be worth.
The stock's next move may depend on whether Western Digital's current earnings are strong and reliable enough to justify where the shares trade today.
If sharp earnings-driven moves in Western Digital have your attention, you might want a side-by-side view of other AI infrastructure stocks using the 53 AI infrastructure stocks.
Is Western Digital a Bargain on Earnings?
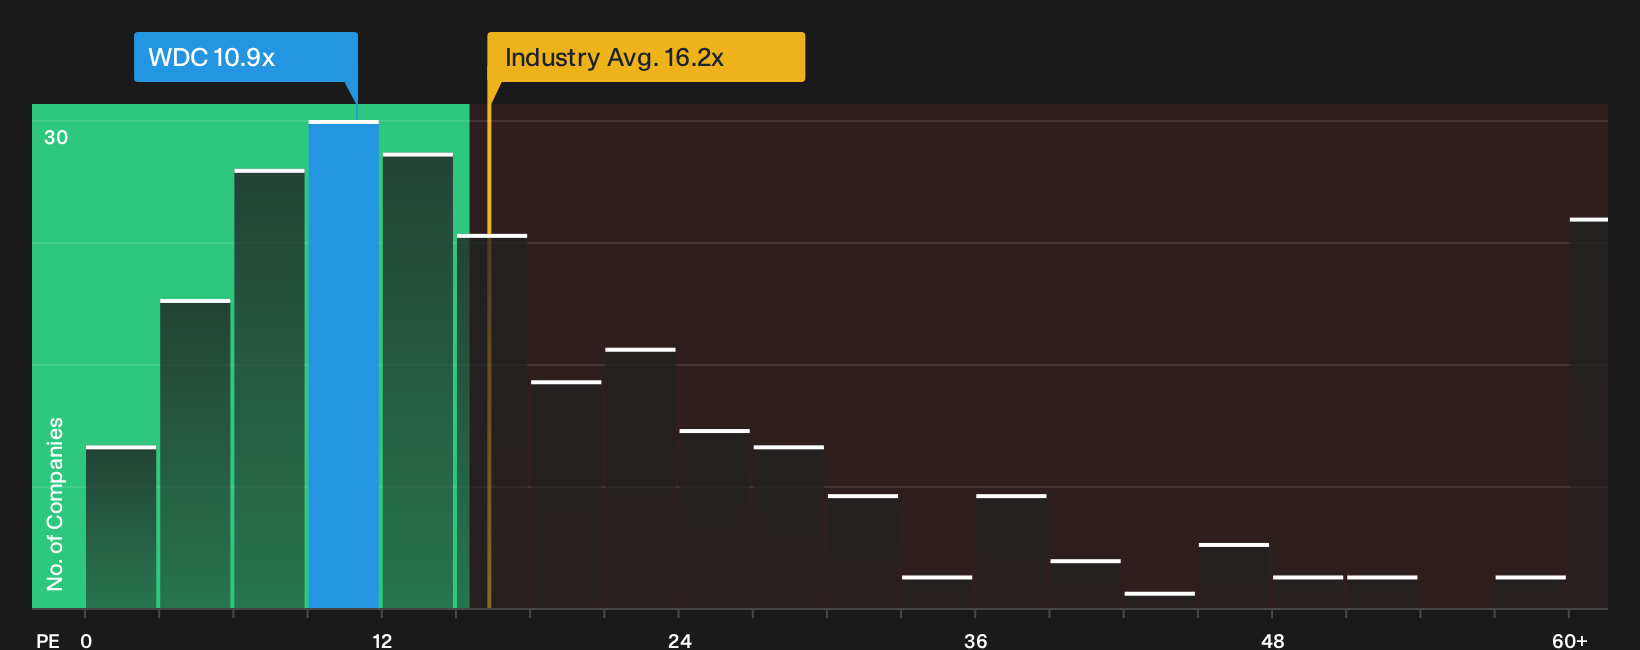
The P/E ratio fits Western Digital because earnings still drive how investors frame the value of its storage and AI oriented cash flows. On this measure, the stock trades at about 10.9x earnings, which is well below the wider tech sector on roughly 16.2x and beneath the peer group closer to 18.7x. That gap suggests the market is pricing Western Digital at a discount to both its immediate rivals and the broader industry, even after a strong multi year share price move.
On a more tailored view that blends growth expectations, profitability, size and risk, the multiple that would typically line up with Western Digital screens higher than where the shares change hands today. Because the recent AI data center slowdown headlines have hit sentiment hard, yet the P/E still sits below those benchmarks, the current tag implies investors are demanding a wider margin of safety around future earnings. Explore the numbers behind Western Digital's P/E valuation.
The Western Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Western Digital's valuation puzzle leaves off by laying out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or less than today, and they sit on the Community page. Instead of stopping at a single multiple or model output, these scenarios spell out the future that number relies on so you can see over time whether reality still matches the original assumption.
One of the top community narratives on Western Digital: 12% undervalued
According to mitchell_lawler, an investor in the Simply Wall St Community, Western Digital now reflects a pure play on AI driven storage demand.
"After separating its flash business in early 2025, WDC is now a focused hard disk drive maker, and demand for those drives has swung from structurally declining to structurally short…"
Discover why this Narrative puts Western Digital at 12% undervalued.
One more Western Digital factor that could change the whole picture
Western Digital’s price tag tells only part of the story, because the people steering the storage franchise and the way their incentives are wired can heavily influence how that story plays out. See who runs Western Digital and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com