
MMM Stock Climbed to an 8.5-Year High on a $7.35 Billion Forever Chemicals Settlement. The Overhang Could Finally Be Lifting.
The fight over "forever chemicals" has turned into one of the costliest legal battles in U.S. corporate history. PFAS have been linked to liver damage, immune system problems, and certain cancers. Lawsuits over them have already led to more than $1 billion in settlements from companies including DuPont de Nemours (DD), Chemours (CC), and Corteva (CTVA).
3M (MMM) is now trying to put a big part of its own PFAS problem to rest. The company announced a pre-tax $7.35 billion settlement commitment spread over nine years to resolve firefighting-foam personal-injury claims. Shares jumped to an 8.5-year high on November 4 after the deal, showing that investors are relieved to finally have a number to work with, even though billions in payments are still ahead.
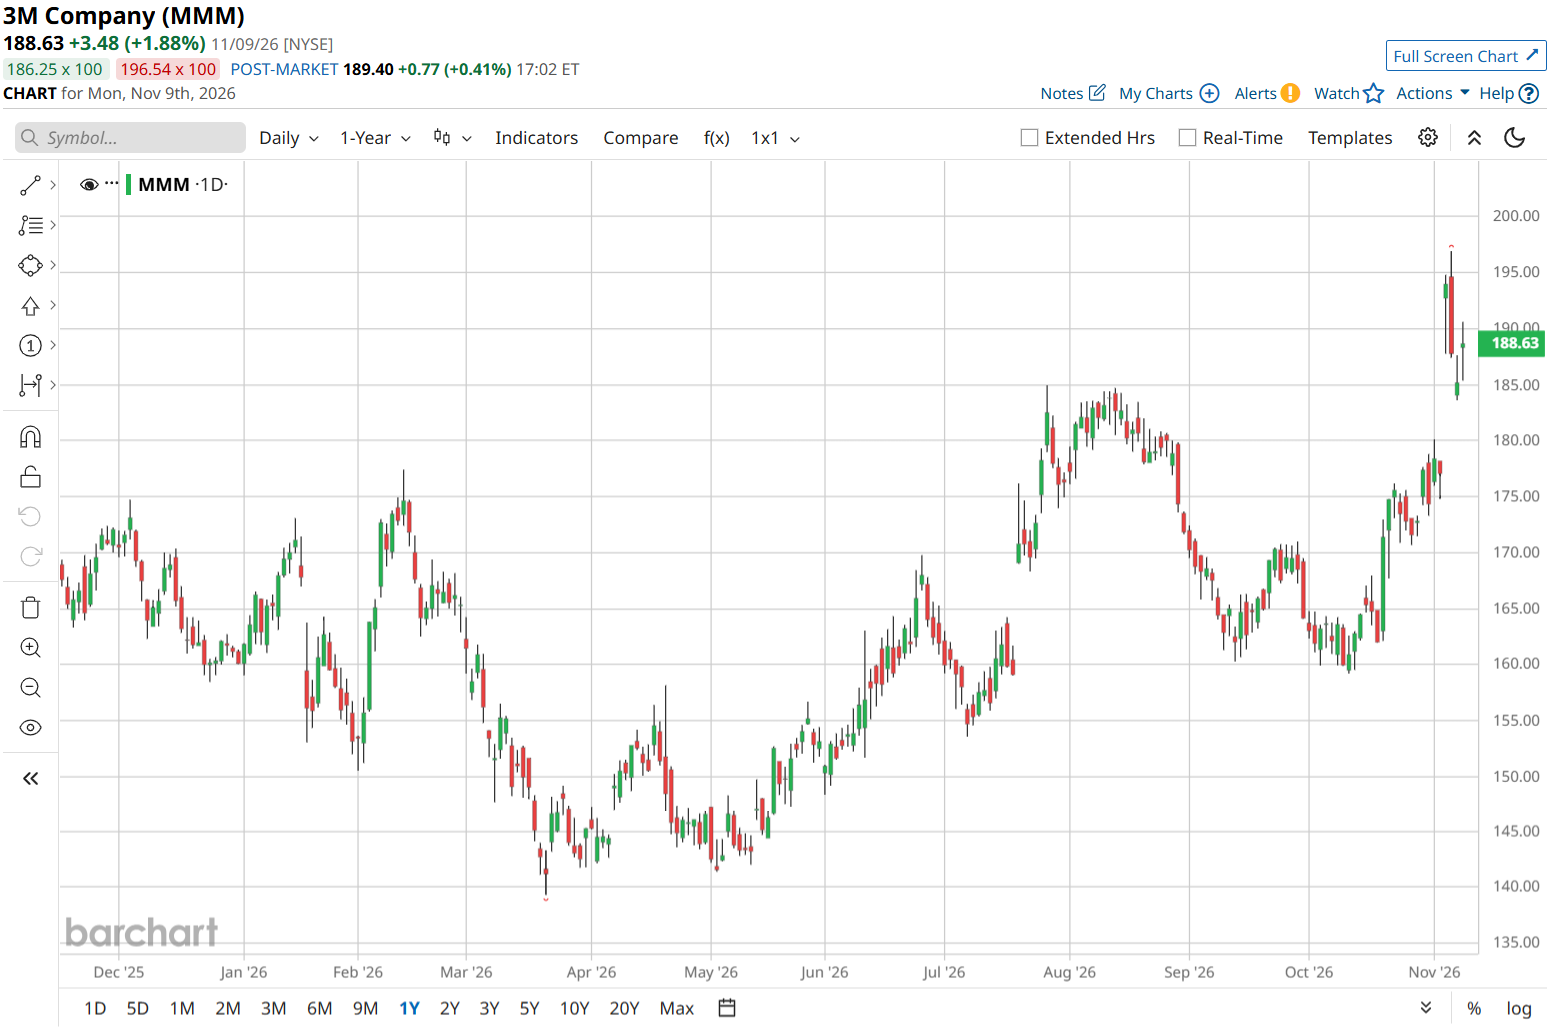
A huge payout sending a stock to a multiyear high seems odd at first. But when uncertainty has hung over a company for years, even a large figure can feel like good news instead of a penalty. Is this the moment 3M’s legal overhang finally starts to lift? Let’s take a closer look.
How Far Does the Settlement Go?
3M (MMM) has settled a large part of its PFAS litigation, but not all of it. Announced on Nov. 3, the deal covers personal-injury claims linked to aqueous film-forming foam, or AFFF, used to fight fires. It addresses about 99% of current personal-injury claims inside and outside the consolidated federal case, with an estimated 115,000 to 120,000 plaintiffs eligible to participate.
This adds to earlier settlements. 3M had already agreed to pay more than $10 billion to U.S. public drinking water systems and another $450 million to New Jersey over natural resource contamination claims.
The latest agreement commits $7.35 billion over nine years, worth $5.8 billion in today’s dollars. Payments start at $50 million in 2026, with nothing due in 2027, then rise to more than $1 billion annually from 2028 through 2033. About 20% is due in the final two years, through 2034. 3M will book a $5.8 billion pre-tax charge in Q4 2026, exclude it from adjusted results, and leave its 2026 guidance unchanged.
For investors, the relief is having a clearer bill and payment schedule. But the deal still depends on enough plaintiffs joining, and future claims or legal challenges could complicate matters. A $680 million reserve for remaining and future personal-injury claims is included in the total commitment, not added on top. 3M admits no liability and can continue fighting the lawsuits if key settlement conditions are not met.
The Business Behind the Breakout
3M has more than settlement news supporting its rally. Third-quarter GAAP sales rose 1% to $6.6 billion, while adjusted organic sales grew 3.3%. Adjusted operating margin reached 26.2%, and adjusted EPS of $2.50 beat the $2.39 estimate. Adjusted free cash flow was about $1.2 billion, helping fund investment, dividends, and buybacks. Management also raised full-year adjusted EPS guidance to $9.10-$9.15.
AI data centers could provide another source of growth. On Oct. 21, Amazon Web Services, part of Amazon (AMZN), announced plans to use more of 3M's Expanded Beam Optical technology across its data centers. The expanded relationship includes a warrant allowing Amazon to buy up to 3.2 million MMM shares, tied to $6 billion in cumulative sales over seven years.
To help meet demand, 3M plans to buy approximately 4.7% of Genius Electronic Optical, and use its manufacturing capacity. This follows July’s partnership with Microsoft (MSFT), the first announced major cloud provider to adopt the technology for its Azure data centers.
Analysts Assess What Comes Next
3M is expected to report its next results on Jan. 19, 2027. For the quarter ending December 2026, analysts expect adjusted EPS of $2.05, up 12.02% from $1.83 a year earlier. Full-year estimates tell a similar story. Analysts project fiscal 2026 EPS of $9.14, up 13.40% from $8.06.
Several firms raised their price targets after the settlement. Goldman Sachs (GS) kept its “Buy” rating and lifted its target to $225, implying about 19.8% upside at the time. UBS (UBS) went further with a $230 target, noting that the agreement covers roughly 99% of current claims and costs less than many investors expected.
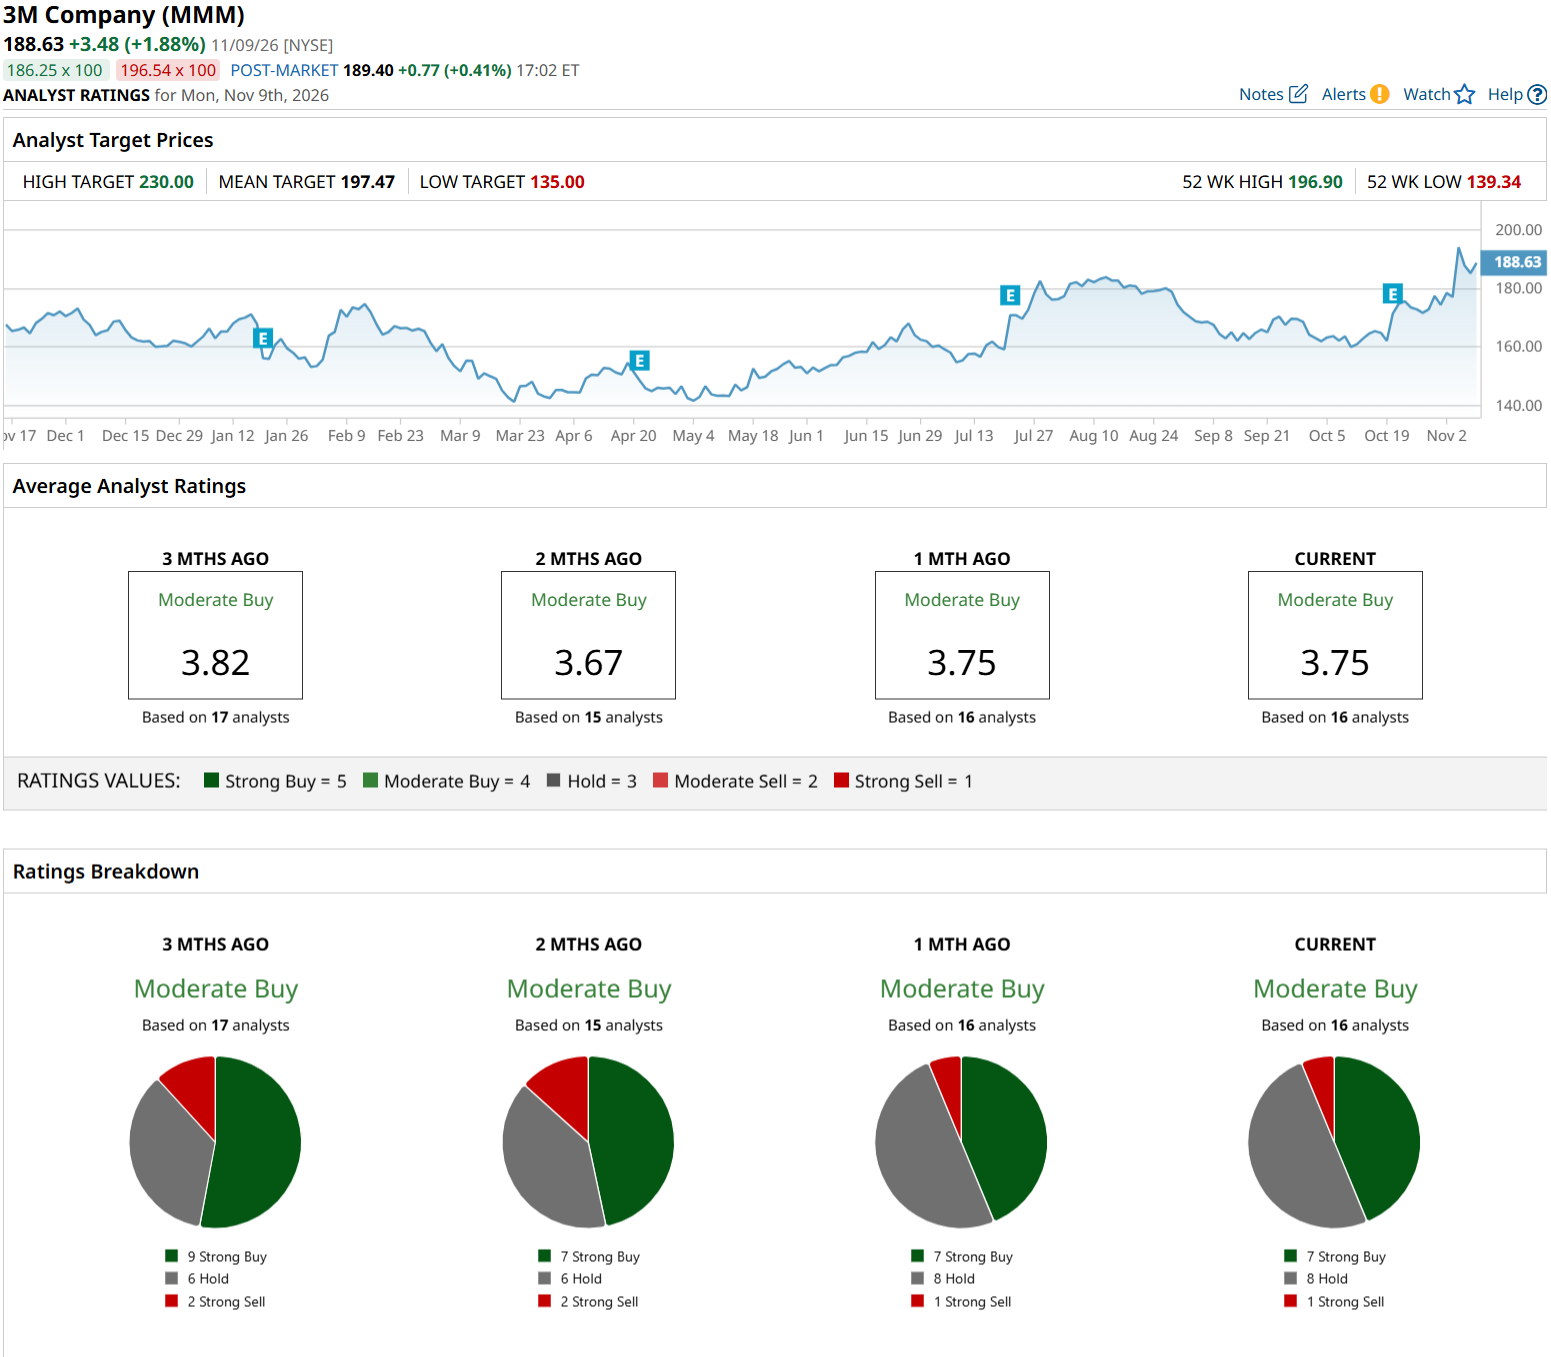
The broader Street is more cautious. Of 16 analysts surveyed, MMM has a consensus “Moderate Buy” rating and an average price target of $197.47. Against current price levels, that points to just 4.69% upside.
Conclusion
The overhang is finally lifting, but it has not disappeared. The $7.35 billion agreement turns 3M’s biggest personal-injury PFAS threat into a defined cost, addresses most current claims, and gives investors a payment schedule they can actually model. That is why the market treated a massive payout as relief rather than punishment. With earnings, cash flow, and data-center demand improving, shares are most likely to keep grinding higher, though at a slower pace after the settlement pop. The easy relief rally has happened. From here, 3M’s next move depends less on lawyers and more on whether it can deliver the earnings growth analysts now expect.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.