
US Stock Market Today: S&P 500 Futures Firm On Hot CPI Fed Repricing
The Morning Bull - US Market Morning Update Wednesday, Nov, 11 2026
US stocks look set for a cautious open with a slight positive tilt, as investors digest October inflation that came in firmer than expected. The single focus today is how this hotter CPI print resets Federal Reserve expectations.
Headline CPI rose 0.4% month on month in October, while core inflation registered 0.3%. Both readings exceeded forecasts of 0.3% and 0.2%. The missing annual core figure leaves the longer term trend less clear, so markets are leaning heavily on these monthly signals.
Stubborn monthly core inflation points to sticky price pressures, which can keep borrowing costs higher for longer and pressure equity valuations. Rate sensitive corners of the market tend to feel this first, as discount rates on future cash flows move up.
The unresolved question is whether upcoming producer price data and jobless claims confirm this sticky inflation story or instead hint at cooling beneath the surface. That balance between renewed tightening risk and a softer growth pulse will be an important driver for the next leg in US markets.
Stocks to Watch Before the Opening Bell
Amphenol (APH)
Record Q3 2026 sales of US$10.2b and a book to bill ratio of 1.19 keep attention on Amphenol this morning. Management plans about US$1.6b of acquisitions, including AdvancedPCB, Humanetics Sensors, and Dexgreen. Investors can watch how integration costs, tax accruals, and deal execution track against full year sales guidance of US$36.9b to US$37.1b.
Zoetis (ZTS)
Zoetis just received a USDA license for Cytopoint Plus, a long acting monoclonal antibody that targets allergic itch in dogs for up to 75 days. The treatment broadens the company’s dermatology range and could influence vet prescribing habits. Watch how quickly clinics adopt the product and whether longer dosing intervals support steadier demand patterns.
CoreWeave (CRWV)
CoreWeave launched CoreWeave Database, a managed PostgreSQL service that runs inside its Kubernetes clusters to support AI applications. Keeping data next to AI compute aims to cut latency and overhead for production workloads. The new product highlights how AI infrastructure players are working to offer a fuller stack, from raw compute through to data handling.
Top Movers
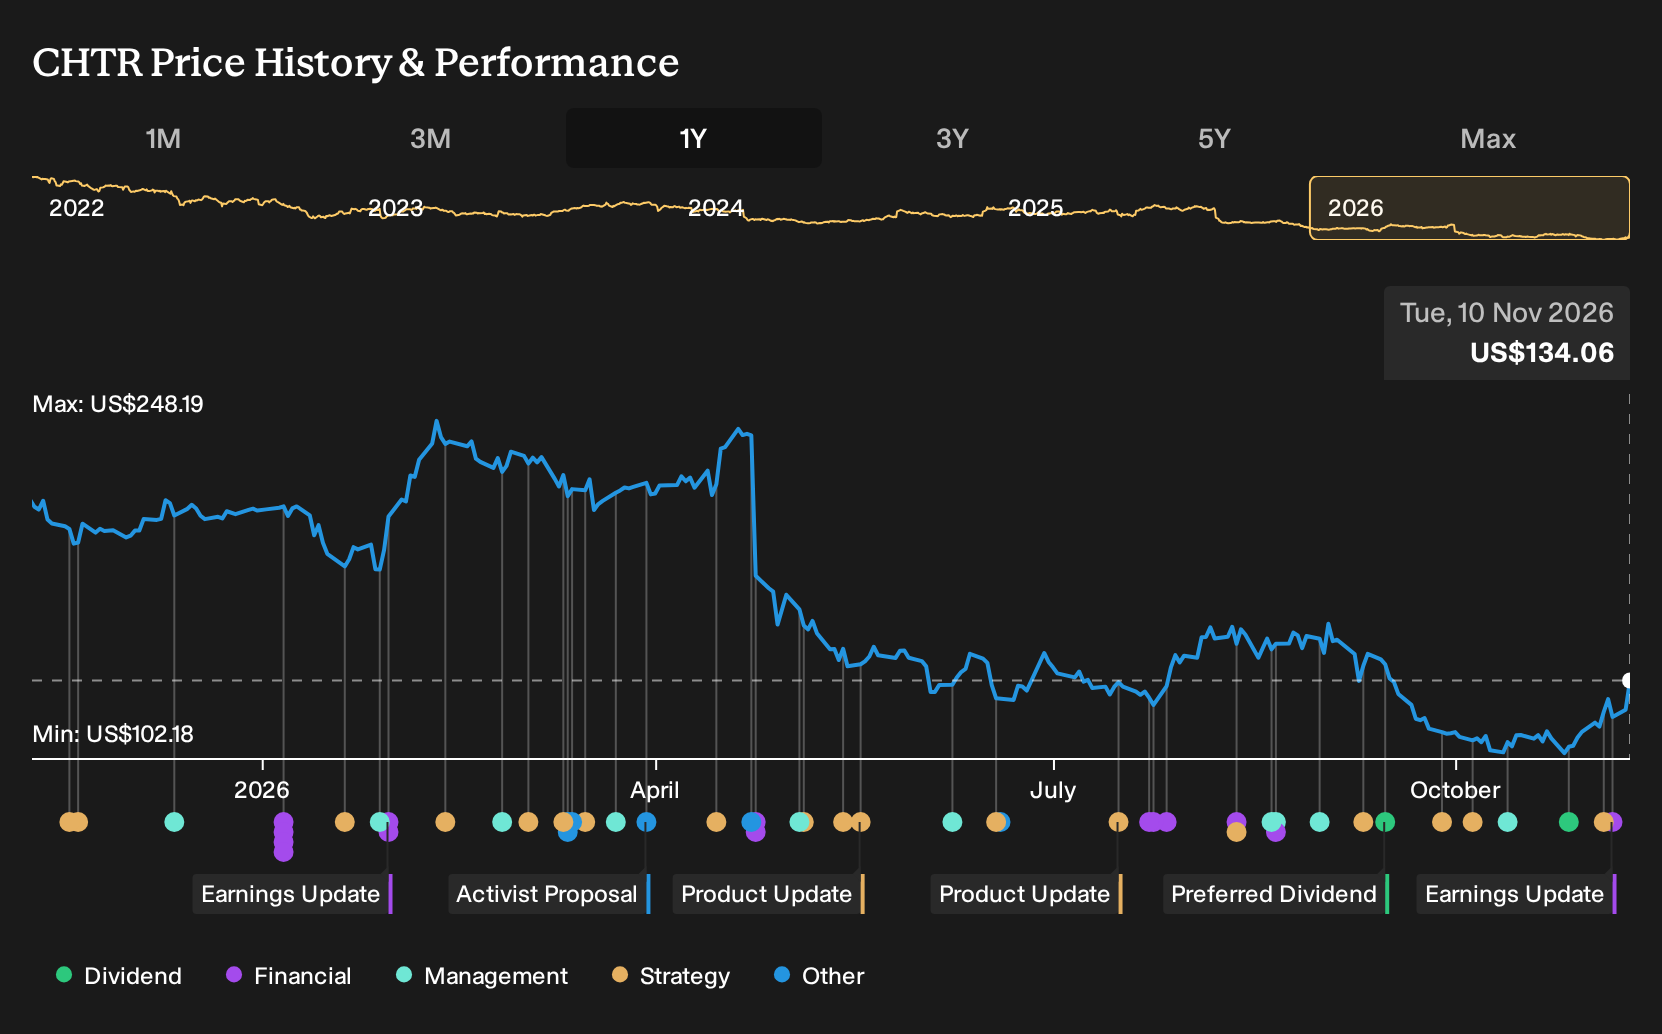
- Charter Communications (CHTR) surged 10.61% after launching up to US$1.5b in note tenders and debt buybacks.
- Take-Two Interactive Software (TTWO) jumped 8.31% as management highlighted unprecedented Grand Theft Auto VI preorders and reiterated fiscal 2027 bookings guidance.
- Rocket Lab (RKLB) climbed 6.54% on record Q3 revenue, a US$3.6b backlog, and fresh Neutron launch contract momentum.
Top Losers
- Skydance (SKYD) declined 7.59% after fresh cost cut plans, leadership changes at DC Studios, and new video game layoffs.
- Moderna (MRNA) declined 6.75%.
- AngloGold Ashanti (AU) declined 5.56%.

On The Radar
Over the next few sessions, US trading revolves around how fresh inflation, housing data, energy inventories, and a packed earnings slate from Disney, Home Depot, and NVIDIA line up with yesterday’s hotter CPI print.
- US Initial Jobless Claims, Thu 12 Nov. Claims are forecast at 191K versus 189K previously, and a figure meaningfully below that would underline a still tight labour backdrop that can keep wage pressures and policy rate expectations elevated.
- US Existing Home Sales, Thu 12 Nov. October sales are projected around 4.0m versus 3.99m in September, and any clear drop from that bar would highlight how 7.3% mortgage rates are weighing on housing turnover and related sectors.
- US PPI and Core PPI, Fri 13 Nov. Producer prices are expected at 0.4% headline and 0.3% core after 1.3% and 0.7%. Readings above those marks would reinforce the message of sticky input costs backing up this week’s stronger CPI.
- US Retail Sales, Tue 17 Nov. October headline spending is forecast to rise 0.6% with the control group at 0.1%. Weaker prints would point to consumers becoming more cautious just as holiday ordering ramps up across retailers and suppliers.
- The Walt Disney Company (DIS), Tue 17 Nov. Q4 2026 results arrive pre market. The focus sits on revenue from streaming and parks alongside any guidance that shapes expectations for content spending against a higher rate backdrop.
- Home Depot (HD), Tue 17 Nov. Q3 2027 numbers at 9:00 AM US Eastern Standard Time will put comparable sales and any commentary on big ticket home projects in the spotlight for read through to US housing related spending.
- NVIDIA (NVDA), Tue 17 Nov. Q3 2027 earnings at 1:20 PM Pacific Standard Time centre on data centre revenue and forward guidance, which together frame how AI chip demand interacts with tighter financial conditions after this week’s CPI surprise.
- US FOMC Minutes, Wed 18 Nov. The release will show how broadly concern over inflation like October’s 0.4% headline and 0.3% core was shared inside the committee, which matters for expectations on how long current borrowing costs may be maintained.
Sector & Industry Watch
Tech: AI headlines, rates still bite
Tech is softer over the past week even though year to date and 12 month returns are still positive. Hotter October CPI keeps pressure on the idea of higher for longer interest rates, which hits sectors where a lot of the value is in profits far out in time.
If you own broad US tech ETFs, pay attention to upcoming Fed speeches and Friday’s PPI, because any tougher language on inflation can keep funding costs elevated for cloud, data centres and AI build outs.
Semiconductors: AI chips, policy and profit squeeze
Semiconductors have declined over the last 7 days and 30 days even though the 1 year and year to date numbers are still ahead of the US Market. Nvidia export headlines, bipartisan AI chip bills and new product news from AMD, Micron and others mean these stocks now move on Washington as much as on phone or PC demand.
If your portfolio leans into chipmakers, Thursday’s US Initial Jobless Claims are the near term trigger to watch because any sign of a still tight jobs market can keep yield expectations firm, which usually weighs on high P/E, cyclical hardware names.
Energy & Oil and Gas: Strong year, short term reset
Energy and Oil and Gas are up strongly over the past 12 months but have retreated over the last week and month. Recent US crude inventory builds, softer oil prices and fresh earnings from ExxonMobil, HF Sinclair and others put focus back on commodity balances and how cautious boards are on new spending.
If you hold producers or midstream stocks, tomorrow’s EIA crude and gasoline inventory data is the key catalyst because any sharp move in stockpiles can quickly feed into pump prices, inflation expectations and how investors compare Energy with more rate sensitive sectors.
Real Estate: REITs leaning on rate pause hopes
Real Estate has risen over the last 7 and 30 days and is ahead of the US Market year to date and over 12 months. Activism and deal news at Independence Realty Trust, new credit lines at Regency Centers and green bond issuance from Equinix show boards working to manage debt and refinancing risk while borrowing costs stay high.
If you own REITs or housing exposed funds, tomorrow’s US Existing Home Sales and today’s MBA 30 Year Mortgage Rate print matter because resale activity and mortgage costs together influence cap rates, property values and how confident management feels about current dividend levels.
Healthcare & Pharmaceuticals & Biotech: Drug pipelines support defensives
Healthcare and Pharmaceuticals & Biotech have both gained over the past week and show strong 12 month returns. Positive trial and approval headlines from Johnson & Johnson, Eli Lilly, Zoetis and a long list of smaller biotechs keep attention on pipelines and cash flows that do not move in lockstep with monthly growth data.
If you tilt toward pharma or biotech ETFs, Friday’s US PPI and any detail on medical cost components are worth tracking because they can influence reimbursement debates, insurer margins and how investors weigh Healthcare against other defensive options like Utilities and Consumer Staples.
How To Find Stocks That Fit Your Strategy
With mortgage rates around 7.3% and housing related stocks back in focus, you can line up potential candidates by starting with this list of list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com