
What Saia Holders Bought Into
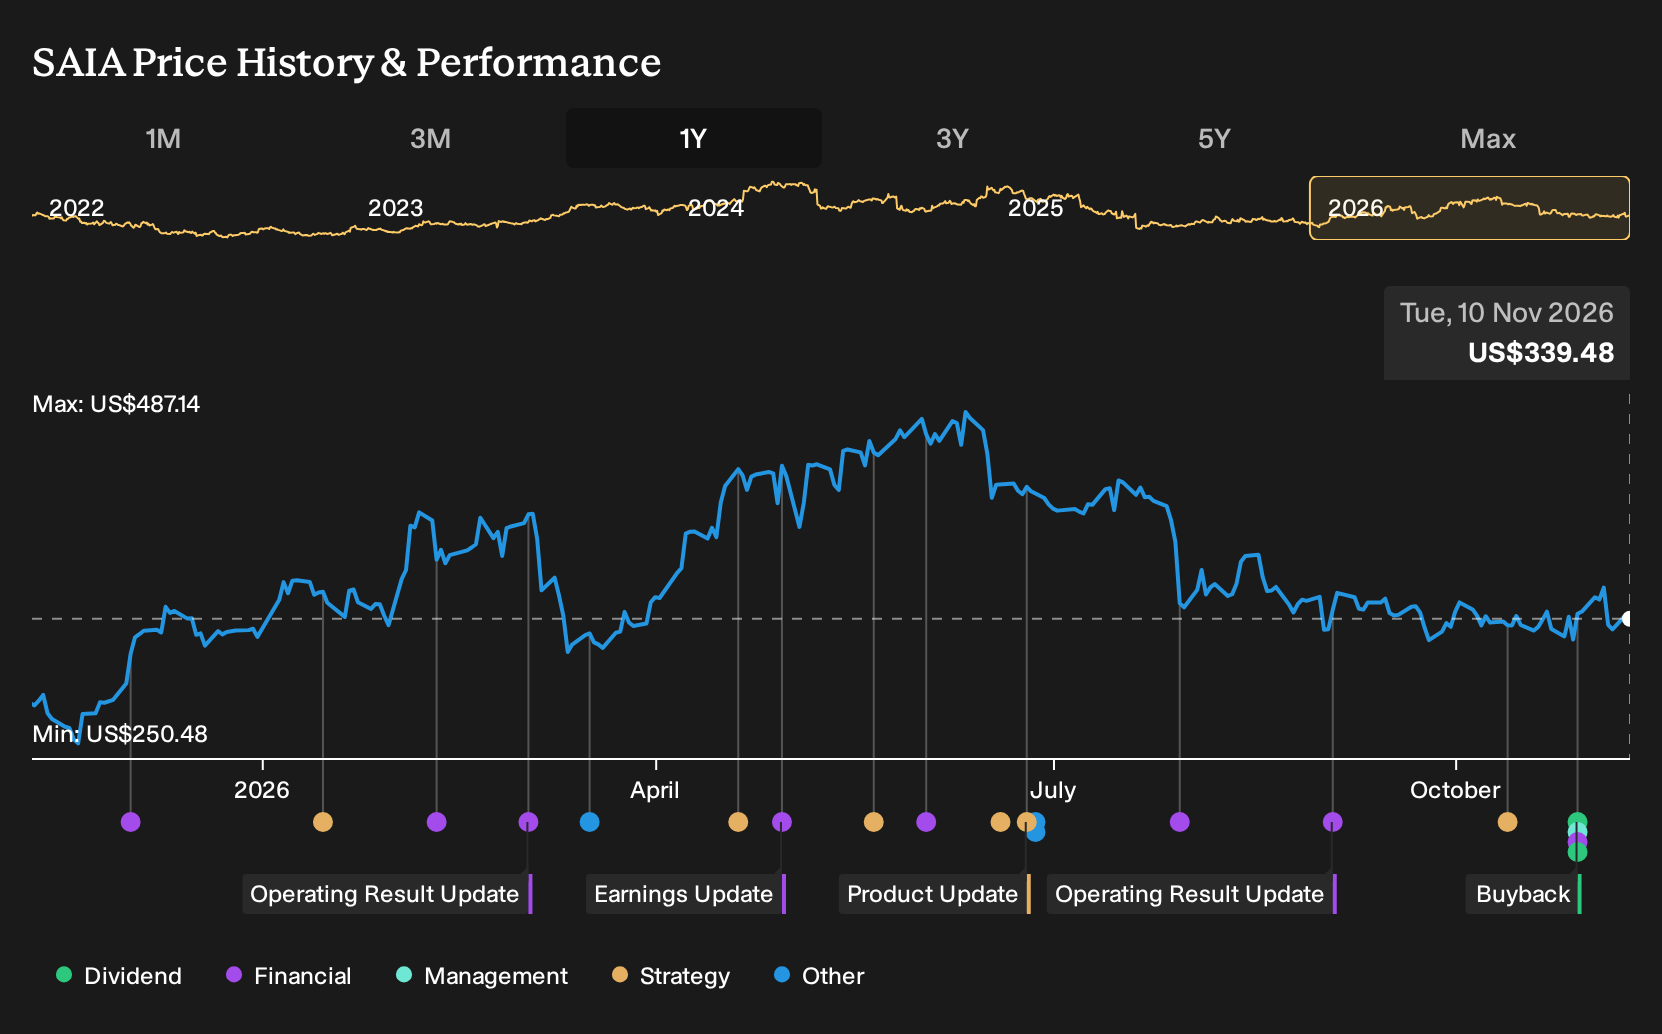
If Saia was on your watchlist rather than in your portfolio, the result may feel like a miss. For Saia shareholders, the return over the past year was 20.8%, including dividends. That outcome raises a sharper question. Back on 10 November 2025, when analysts were debating whether cost controls and an expanding terminal network could support higher margins even with softer freight volumes, what signals might have helped you judge whether that margin story would actually stick?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Saia. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Two Saia Stories Investors Had To Weigh
Saia shares cost US$277 at the start of the period, and investors were essentially choosing between a margin expansion story and a capacity risk story.
The bullish narrative saw fair value at US$338, or 22% above the start price. This view was built on the idea that an expanding terminal network and logistics technology would support higher margins and revenue growth.
The bearish case put fair value at US$250, or 10% below the start price. This perspective focused on e-commerce automation, regulatory pressure, and capital-intensive fleet upgrades as potential threats to Saia's utilisation and profitability.
What The Results Changed For The Saia Margin Story
Record Q3 2026 revenue of US$982.5m, helped by network expansion and a 7.1% rate increase, leaned toward the bullish Saia case that argued terminals and technology could support higher margins. However, net margin slipped from 10.3% in Q3 2025 to 9.3% alongside higher expansion and wage costs. The evidence cut both ways.
The hinge assumption was that cost efficiencies would more than offset growth spending. When judging another carrier, track whether margin moves in the same direction as revenue once big capital projects start to scale.
What Saia's Recent Run Already Prices In
Saia shares are about US$339 after a 20.8% gain over the past year, and the bearish analyst Narrative on Simply Wall St now places its Fair Value below that market level.
The Narrative centres on whether higher fuel, wage, and purchased transportation costs allow Saia’s expanded network to earn enough operating ratio and free cash flow improvement to justify heavy reinvestment.
"Although Saia is reporting record revenue and improving operating ratio from its enlarged network, the sharp 47.3% rise in purchased transportation expense and shift to 15.4% of linehaul miles handled externally risk embedding a higher structural cost base that could restrain future operating margin and earnings progression if volumes soften or rail pricing tightens further."
One Narrative disagrees with today's price. → See where this Narrative says Saia should trade
Looking Past Saia’s Trucks
Saia shows how physical freight networks can turn pricing power into cash.
But before a shipment reaches any terminal, someone still chooses a carrier.
That choice increasingly runs through software that matches loads with available capacity.
One freight marketplace already manages that matchmaking at broad scale, setting prices and routing without owning trucks.
If more freight buying shifts into that kind of platform, the margin story changes, and power may tilt toward whoever owns the freight marketplace.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 66% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com