
Is Hugo Boss (XTRA:BOSS) Undervalued On Its Q3 2026 Results?
Hugo Boss (XTRA:BOSS) has just posted third quarter 2026 results, reporting sales of €946 million and net income of €48 million. These figures may influence how investors reassess the stock.
The latest quarterly figures land against a mixed performance backdrop for Hugo Boss. The share price is at €38.41, with a year to date share price return of 5.81% and a 1-year total shareholder return of 4.63%. Over 3 years, the total shareholder return has declined 30.44%, which points to some recent momentum but a weaker longer-term record as investors reassess both earnings resilience and perceived risk around the story.
Scan how Hugo Boss compares with other fashion and consumer names that have recently come under earnings pressure by reviewing our curated list of 201 high quality undervalued stocks.
Hugo Boss now looks like a solid, global brand whose recent earnings wobble has reset expectations. The real question is whether the current €38.41 share price already reflects that tension between quality and caution.
Most Popular Narrative: 4.3% Undervalued
On the analyst consensus Narrative on Simply Wall St, Hugo Boss carries a fair value of €40.12 against the latest €38.41 close, which frames the stock as modestly undervalued while putting earnings quality at the center of the thesis.
Structural improvement in gross margin and cash generation, shown by Q1 2026 gross margin of 62.5% and Q2 2026 gross margin of 64.9% alongside double digit inventory reductions and positive free cash flow before leases, supports the idea that further sourcing and markdown efficiencies can feed into future net margin and earnings resilience.
See why 40 investors see Hugo Boss as 4% undervalued.
Result: Fair Value of €40.12 (UNDERVALUED)
Still, the thesis around Hugo Boss can break if shrinking store space and weaker HUGO brand sales continue to pressure overall revenue and EBIT progress.
Find out about the key risks to this Hugo Boss narrative.
Another View: Hugo Boss Through The P/E Lens
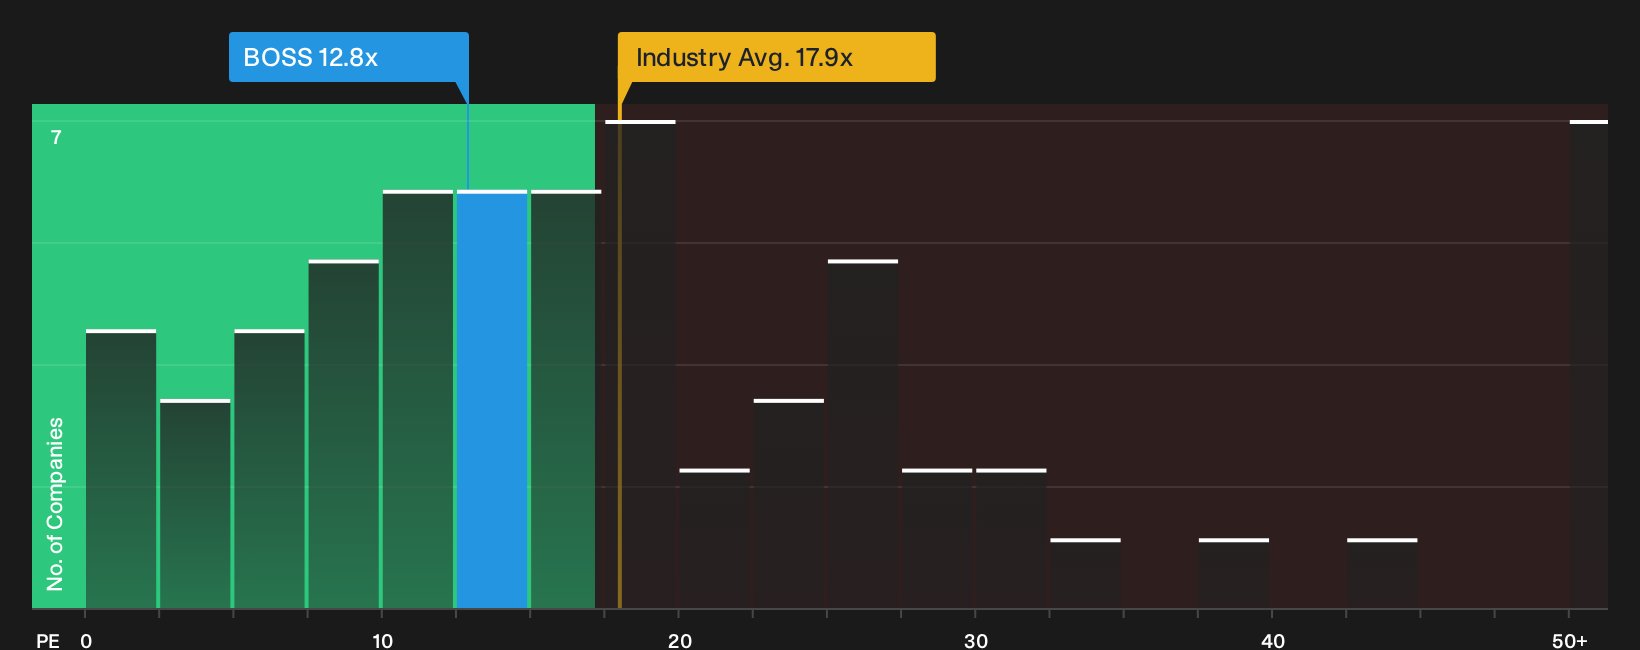
On a simple earnings multiple, Hugo Boss trades on a P/E of 12.8x. That is slightly higher than the 12.7x peer average, above a fair ratio of 8.6x, yet well below the 18x European luxury group level. The mix hints at valuation risk locally and potential opportunity versus the wider sector. Which side matters more for you?
To see how that earnings multiple stacks up against the underlying numbers, and what it could mean if the market moved closer to the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Hugo Boss is mixed, so treat this as a prompt to move quickly, review the numbers yourself and decide what feels reasonable for your risk profile. If you want a quick shortcut before forming your own stance, start by checking the 2 key rewards
Looking for more investment ideas beyond Hugo Boss?
If Hugo Boss has you rethinking your watchlist, now is the moment to widen your lens and look for other opportunities before the crowd catches on.
- Spot potential value candidates early by scanning the market with the 201 high quality undervalued stocks, which highlights companies trading below their implied worth.
- Strengthen your income stream by reviewing the 221 dividend fortresses, which focuses on higher yielding businesses with a history of making regular payouts.
- Dial down portfolio risk by filtering for the 208 resilient stocks with low risk scores, which emphasizes resilient balance sheets and more stable financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com