
Does Raised Revenue Guidance Change The Bull Case For Enpro Stock (NPO)?
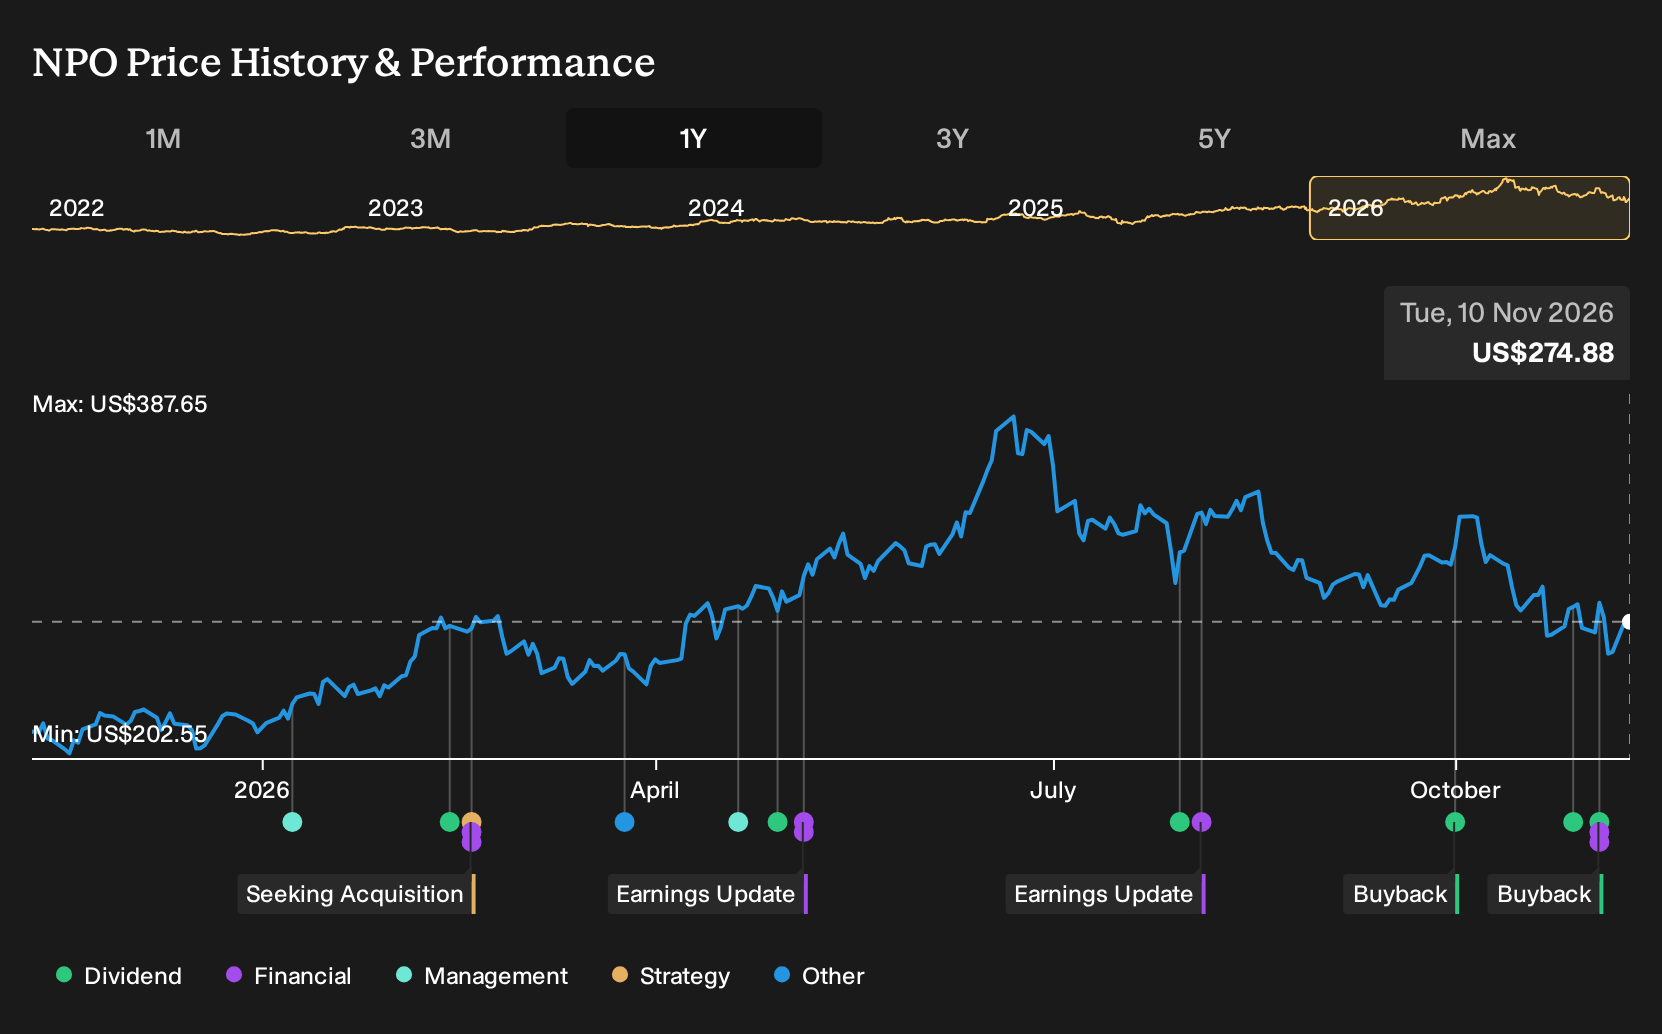
- Enpro Inc. reported third quarter 2026 sales of US$350.8 million and net income of US$40.3 million, with higher basic and diluted earnings per share from continuing operations than in the prior year period. The company also issued full year 2026 revenue guidance of US$1.33 billion to US$1.34 billion.
- The new US$50 million share repurchase authorization running through October 2028, alongside an affirmed US$0.32 quarterly dividend, highlights management’s ongoing focus on returning capital while funding Enpro’s operations and growth priorities.
- We will now look at how Enpro’s investment narrative could be influenced by this stronger quarterly profitability and higher 2026 outlook.
See how Enpro’s latest earnings, guidance, and capital returns compare with peers by reviewing a curated set of 35 high quality undervalued stocks that also pair profitability with disciplined balance sheets.
Enpro Investment Narrative Recap
To own Enpro, you need to believe the current semiconductor and mission critical sealing focus can keep translating into durable earnings and cash generation. The analyst consensus Narrative on Simply Wall St leans on the Advanced Surface Technologies and Sealing segments doing the heavy lifting. The latest quarter, with higher sales and net income, supports that operating story in the near term.
The main near term swing factor remains semiconductor and AI related capital spending, which influences AST orders and margins. The biggest risk is that this spending cools relative to current expectations. Recent guidance and profitability do not remove that exposure, although they give management more room to fund capacity, remediation and acquisitions.
The most relevant update here is Enpro’s raised 2026 revenue guidance to US$1.33b to US$1.34b, framed as 16% to 17% growth compared with the prior 14% to 16% range. That tighter, higher band matters because the analyst consensus Narrative on Simply Wall St already leans on Enpro converting semiconductor demand and acquisitions into higher segment margins.
When a business edges guidance up after reporting nine month sales of US$992.6 million and net income of US$94.8 million, execution risk around capacity ramps and backlog conversion comes into sharper focus. Any stumble in AST projects, environmental cash outflows, or Sealing margin pressure could make it harder to stay within that revenue range and keep earnings tracking analyst expectations.
Enpro's current analyst narrative is based on forecast revenues of about US$1.6b and earnings of US$278.0 million by 2029. These figures are derived from revenue growth assumptions of 9.2% per year and an increase in profit from US$44.1 million today to that higher earnings level, which represents roughly a sixfold increase in earnings power.
Discover how Enpro's fair value indicates a 42% potential upside to its current price, a discount that could narrow quickly as investor sentiment changes.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$319 to US$389 per share, so even this small sample shows wide disagreement on Enpro’s potential. You are weighing that against fresh earnings, higher 2026 guidance, and a new buyback plan. All of these factors could reshape how future community views evolve.
Explore another Enpro fair value estimate, including one that suggests it could be worth just $319.37.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Enpro research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enpro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enpro's overall financial health at a glance.
Looking For More Investment Ideas Beyond Enpro?
Once you have a view on Enpro, it can help to scan a wider set of opportunities so you can compare quality, valuation, and risk across different businesses.
- For investors hunting for income with staying power, review a 5 dividend fortresses that focuses on companies pairing higher yields with resilient payout profiles.
- If capital preservation sits high on your priority list, take a look at a 30 resilient stocks with low risk scores that screens for businesses with more resilient risk scores.
- When you want financially sound operators with room to grow, use a 20 high quality undiscovered gems that surfaces lesser known companies backed by stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com