
How Investors Are Reacting To NCR Atleos Stock After Earnings And Retail ATM Launch
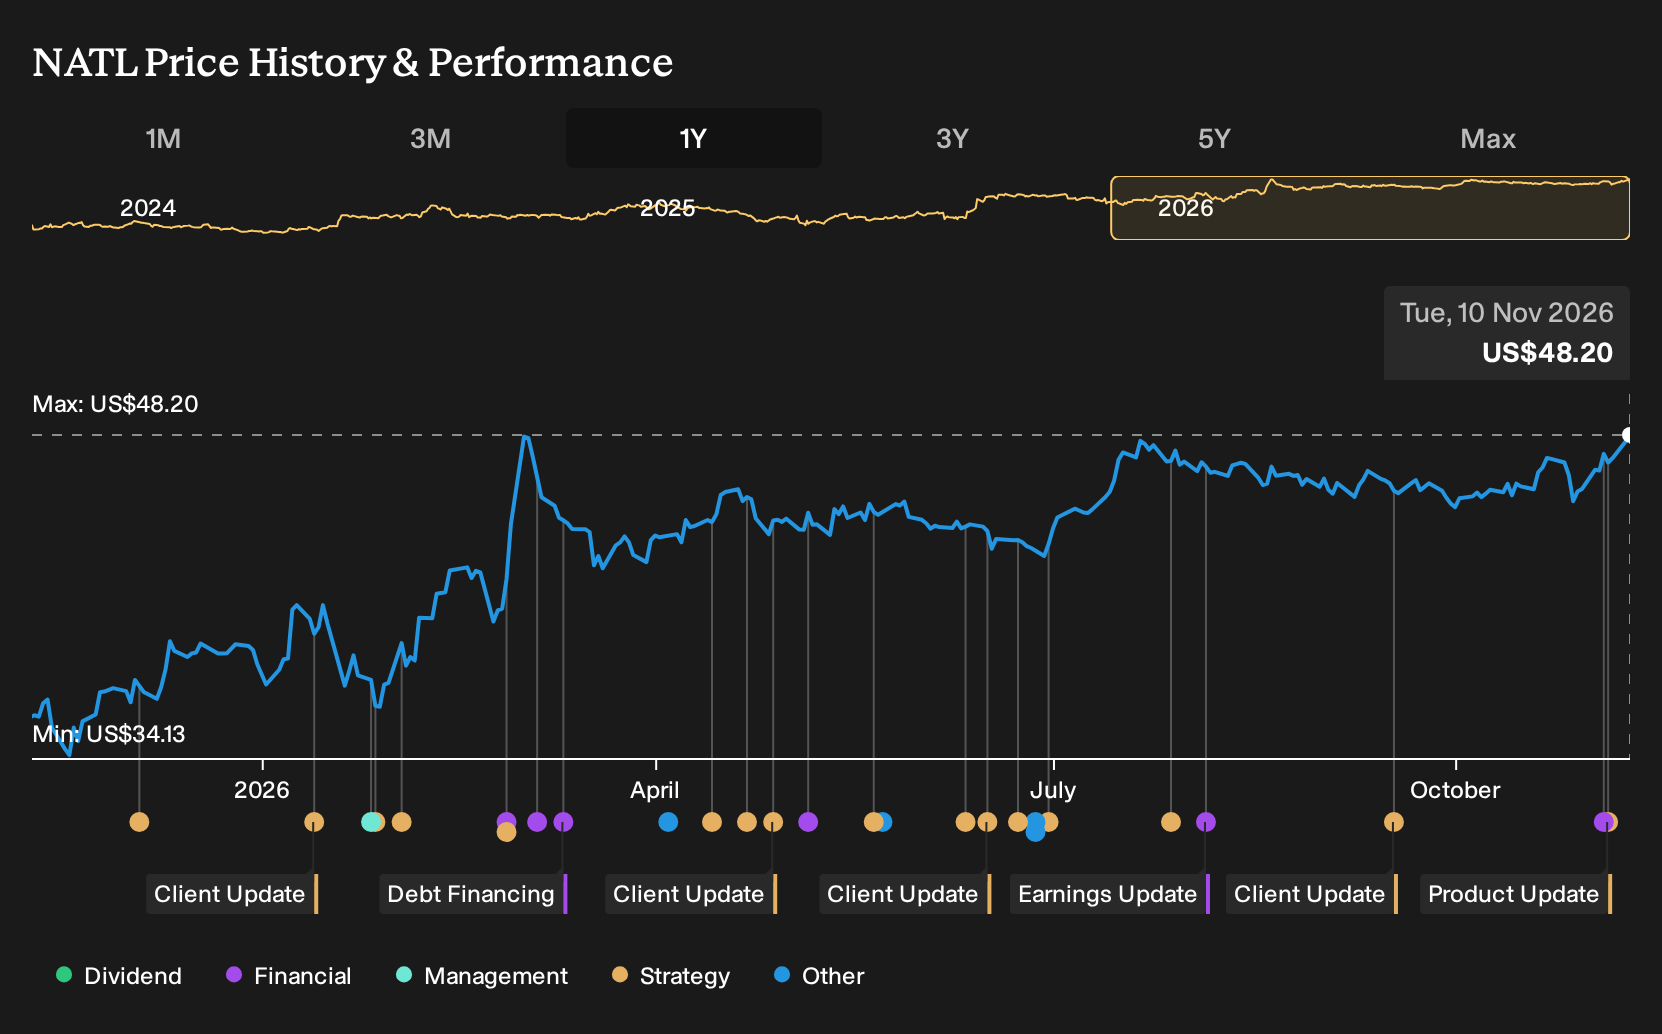
- NCR Atleos reported third quarter 2026 revenue of US$1,099 million with net income of US$97 million, alongside nine-month net income of US$184 million, and introduced AllTM, a multi-function ATM offering cash handling, deposits, bill payment and cardless transactions for US retailers.
- The AllTM launch positions NCR Atleos to use in-store ATMs as a tool for foot traffic and labor-efficient cash management, linking its hardware to ongoing service demand inside retail locations.
- This article reviews how NCR Atleos' reported earnings and the AllTM rollout could influence the existing investment narrative around cash management.
NCR Atleos Investment Narrative Recap
To own NCR Atleos, you need to believe that cash access and in-person financial transactions remain important enough for retailers and banks to keep investing in ATMs, and that services tied to that infrastructure can support earnings. The analyst consensus narrative on Simply Wall St emphasizes recurring revenue and margin expansion, with the hardware refresh cycle identified as a key short-term swing factor.
Recent Q3 results, with US$97 million in net income on US$1,099 million of revenue, support a story of improving profitability, although interest coverage remains a flagged risk. The biggest near-term operational risk is still reliance on physical cash usage while carrying meaningful debt, so the AllTM launch is helpful but not a decisive catalyst on its own.
The AllTM announcement is a clear link between NCR Atleos and in-store financial services for US retailers. It extends the ATM into deposits, bill payment and cardless transactions. This ties into the cash management and ATM-as-a-service themes analysts already focus on, including higher services attachment and recurring transaction revenue.
For catalysts, AllTM matters because it moves NCR Atleos deeper into retailer workflows rather than only serving bank branch traffic. That aligns with the analyst emphasis on outsourced, integrated cash management as a potential driver of earnings, but it also concentrates execution risk around product rollout, retailer adoption and competition from fintechs and large technology providers targeting similar store-level payment flows.
NCR Atleos' current analyst storyline points to revenues of US$5.0b and earnings of US$552.4 million by 2029, based on 3.9% yearly top line growth and an earnings increase of about US$382 million from US$170.0 million today.
Discover why NCR Atleos' fair value suggests a 4% potential upside compared to its current price before the market fully reflects this discount.
Exploring Other Perspectives
One alternate angle on NCR Atleos focuses on cost pressure rather than new products like AllTM. The most cautious analysts worry that extra vault cash and tariff costs, pegged around US$9 million and US$25 million to US$30 million a year, could squeeze future earnings even if revenue reaches about US$5.1b and US$713.8 million of profit by 2029. Those projections, set before this announcement, indicate a much tougher path than the consensus view. Use them as a reminder that reasonable people can read the same data quite differently and that this new product launch may eventually shift both the bullish and bearish stories.
Explore 2 other NCR Atleos fair value estimates, including one that suggests as much as 54% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NCR Atleos research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NCR Atleos. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCR Atleos' overall financial health at a glance.
Looking for more NCR Atleos sized investment ideas?
If the NCR Atleos story has you thinking about where to look next, widen your lens with a few focused stock lists built to surface very different types of opportunities.
- For investors hunting for future standouts that still fly under the radar, start with 20 high quality undiscovered gems that already show solid fundamentals.
- If capital preservation matters as much as upside, filter for stability using our 30 resilient stocks with low risk scores and see which businesses score well on resilience.
- Income focused investors can prioritize reliability by scanning a curated set of 5 dividend fortresses that aim to combine meaningful yield with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com