
3 China Infrastructure Stocks Retail Investors Are Watching As Rate Support Holds
China’s central bank has just sketched out a friendlier backdrop for domestic demand and infrastructure, and that turns a dry policy statement into a live question for your portfolio. When borrowing costs stay low and authorities lean into supporting the real economy, some stocks linked to spending and construction may gain fresh attention while others risk being left behind. This article walks through three Chinese-listed companies exposed to that policy story and explains why each could matter for your next move.
The three stocks covered next are only a sample of what this theme touches, and the full screen surfaced 22 more Chinese Domestic Demand & Infrastructure Beneficiaries with equally compelling stories that are not included here. To go straight to the broader opportunity set, analyze and compare potential high conviction ideas using the Chinese Domestic Demand & Infrastructure Beneficiaries screener.
L&K Engineering (Suzhou)Ltd (SHSE:603929)
Overview: L&K Engineering (Suzhou)Ltd delivers specialized engineering, procurement, construction and clean room services for high tech and healthcare infrastructure across China.
Market Cap: CN¥20.0b
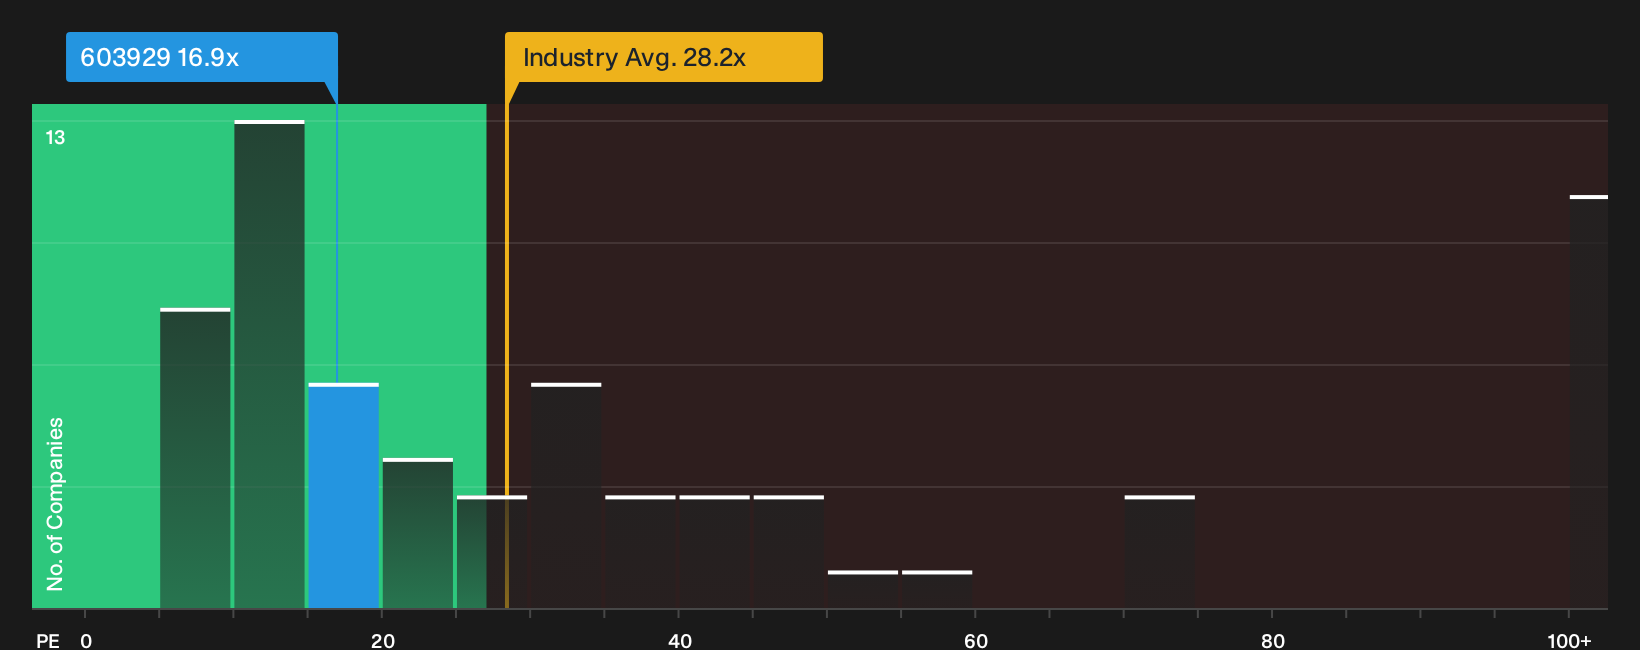
L&K Engineering (Suzhou)Ltd sits close to the heart of China’s domestic build out story, from semiconductor fabs to hospitals and commercial projects. The stock pairs that policy linked engineering exposure with a relatively low P/E against construction peers and strong recent earnings and margin progress. This leaves a lot depending on how one unseen pressure in its external funding model plays out.
That unresolved funding pressure is exactly why many investors are pulling up the 4 key rewards and 1 important warning sign to see whether current pricing reflects the full risk reward trade off.
Guangdong Mingyang ElectricLtd (SZSE:301291)
Overview: Guangdong Mingyang ElectricLtd supplies power transmission, distribution, and control equipment that links directly into China’s grid, energy, and infrastructure build out.
Market Cap: CN¥11.7b
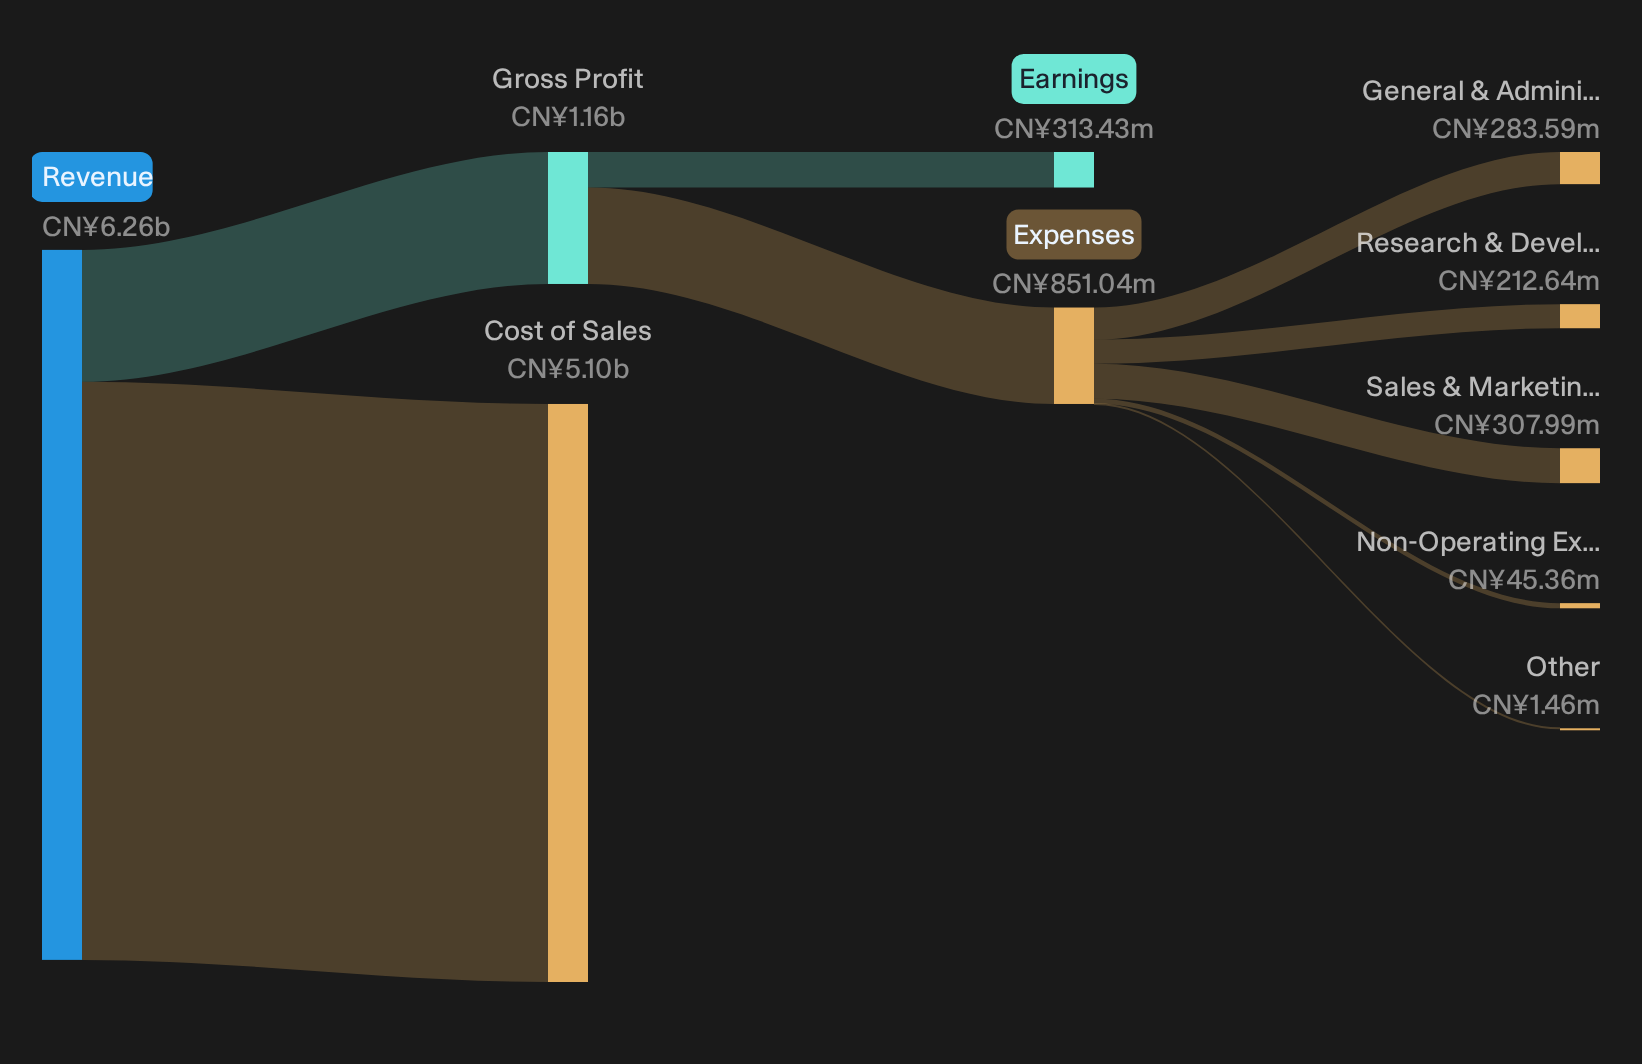
Guangdong Mingyang ElectricLtd provides exposure to China’s power infrastructure theme, with equipment used in grids, data centers, transport, and onshore and offshore energy projects as policy support leans into utilities and industrial investment. Forecast double digit earnings and revenue growth meet recent earnings pressure, and a lot now rests on how one pressure on profitability resolves.
That earnings pressure is the crux, so dig into the 2 key rewards and 2 important warning signs to see whether Guangdong Mingyang ElectricLtd’s growth story outweighs the margin hit.
Beijing Sifang AutomationLtd (SHSE:601126)
Overview: Beijing Sifang AutomationLtd builds protection, control, and automation systems that keep power grids, substations, and large energy projects running reliably.
Market Cap: CN¥25.8b
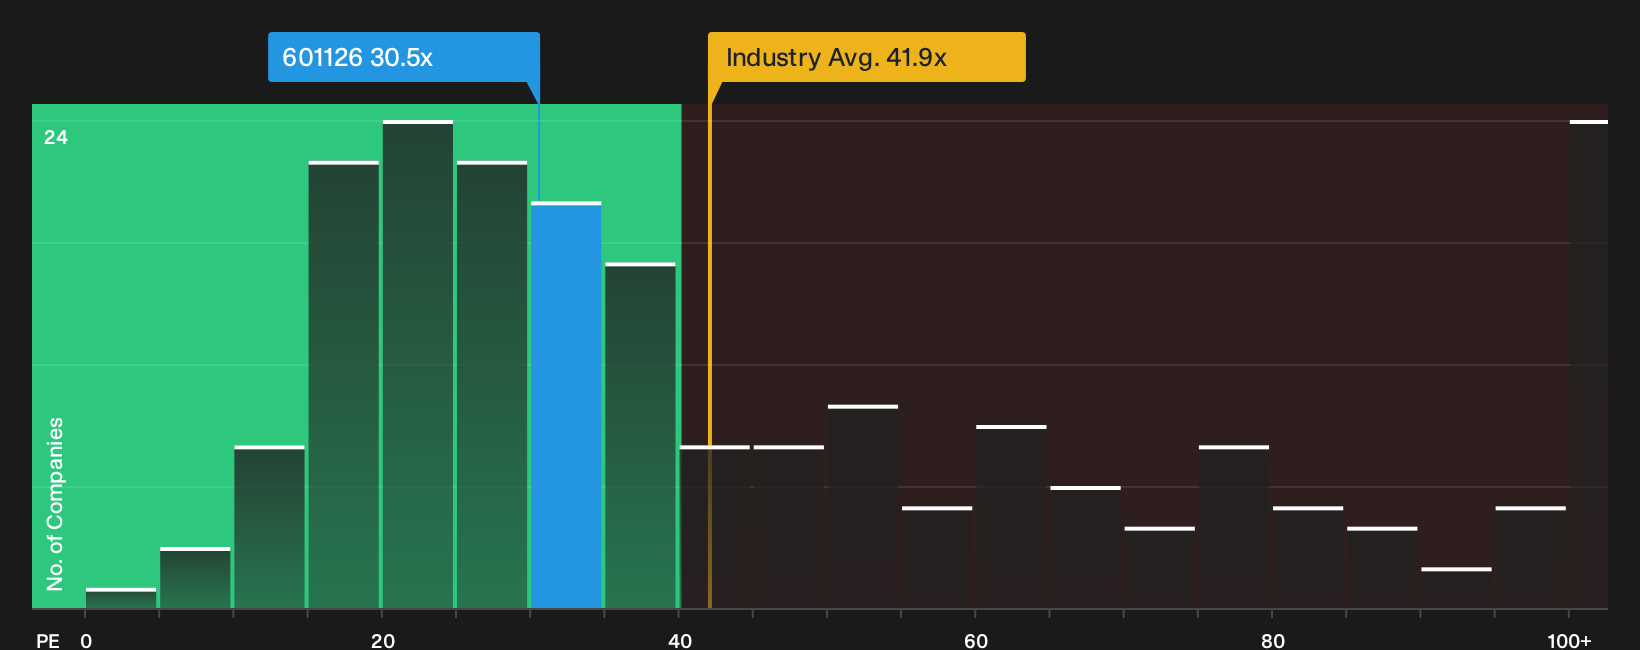
Beijing Sifang AutomationLtd is directly involved in China’s infrastructure upgrade efforts, with power grid automation products used in transmission, distribution, and renewable projects as policymakers keep financing conditions supportive. Forecast revenue and earnings growth tied to infrastructure capital expenditure, a P/E below the broader electrical industry, and inclusion in major indices make it a stock to watch. This is particularly relevant in light of how one unseen pressure in its funding and cash generation mix develops.
With that funding and cash generation question hanging in the background, review the 3 key rewards and 2 important warning signs (1 is major!) to see whether Beijing Sifang AutomationLtd’s valuation is masking the real story.
Curious About Alternative Market Paths
Fresh themes can move before headlines catch up, and the best breakout stories often fly under the radar for now. Scan them while it matters and get in early.
- Spot under-the-radar quality by scanning a curated 201 high quality undervalued stocks before the crowd catches pricing momentum and tightens the window for a clean entry.
- Turn curiosity about automation into action by running the 89 robotics and automation stocks and see which operators might participate in the next capex wave rather than risk dropping behind.
- Track the build out of digital assets infrastructure using the 21 cryptocurrency and blockchain stocks so potential leaders are on your radar before liquidity and attention increase.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com