
Hitachi (TSE:6501), What Is Behind The Fresh Attention Today?
Hitachi guidance and dividend moves come into focus
Hitachi (TSE:6501) has been in the spotlight after raising its fiscal 2026 earnings guidance, lifting its interim dividend, and releasing half year results. This combination directly affects expectations for shareholder returns.
Recent trading tells a mixed story. Hitachi shares have climbed 1.95% on a one day basis and edged higher over the past week, yet the 30 day share price return is down 12.52% and year to date the share price has slipped 2.15%. The three year total shareholder return of 156.08% and five year total shareholder return of 269.68% still point to strong longer run gains, suggesting momentum has cooled recently even as investors react to the upgraded guidance and higher interim dividend.
Scan how other industrial and infrastructure players are reacting to guidance shifts and dividend changes by checking our hand picked 41 power grid technology and infrastructure stocks alongside Hitachi.
Hitachi has raised guidance and lifted its interim payout, yet the share price has slipped over the past month. Does that setup argue for stepping in now, or waiting for a cheaper entry later?
Most Popular Narrative: 25% Undervalued
Hitachi closed at ¥4,959, while the analyst consensus Narrative on Simply Wall St pegs fair value at ¥6,600 using a 5.42% discount rate, implying meaningful upside according to that framework.
Persistent, robust demand for power grid upgrades and renewable energy integration, notably in Europe and North America, is driving substantial growth in Hitachi's Energy sector, and continued investment in electrification and grid modernization is expected to support revenue and margin expansion in upcoming years.
See why 23 investors see Hitachi as 25% undervalued.
Result: Fair Value of ¥6,600 (UNDERVALUED)
Still, the thesis around Hitachi can weaken if the enlarged Energy capex fails to earn adequate returns, or if geopolitical and data rules disrupt large grid and digital projects.
Find out about the key risks to this Hitachi narrative.
Another View: Hitachi Through The P/E Lens
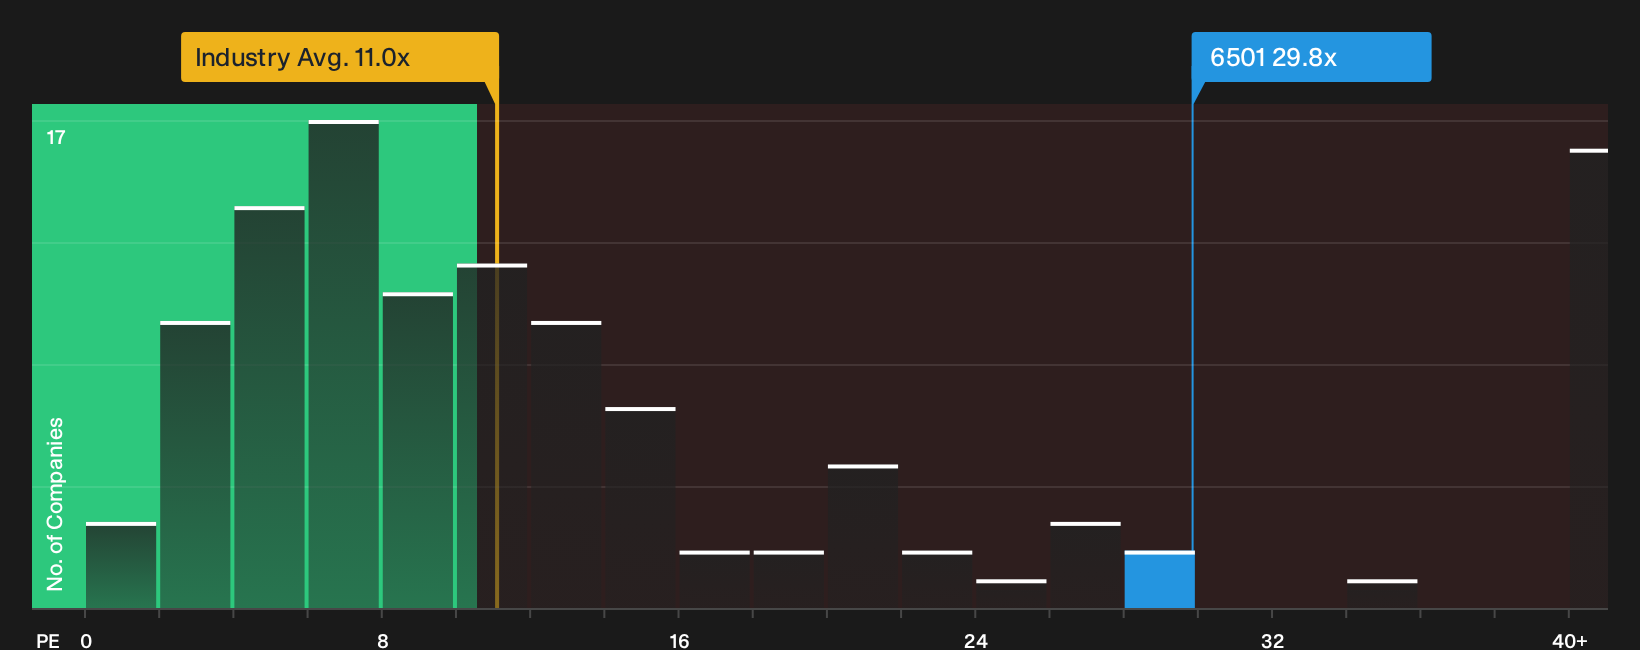
Most of the bullish narrative around Hitachi leans on discounted cash flow and analyst targets. The simple P/E check tells a tougher story. The shares trade on 29.8x earnings versus 11x for the wider Asian Industrials group and a fair ratio estimate of 29.7x, which points to very little valuation cushion if expectations slip.
That premium might reflect confidence in Hitachi's Energy and digital mix, or it could mean the bar is set high just as execution and capex risks grow more complex. How comfortable are you paying up at this stage of the cycle?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Hitachi is mixed, with valuation upside on one side and richer P/E signals on the other, so move quickly and stress test the numbers yourself. To see what optimistic investors are focusing on, go straight to the breakdown of 3 key rewards
Looking for more ideas beyond Hitachi?
Do not stop at one stock when a broader watchlist can help you spot patterns, compare quality, and pressure test every thesis against real alternatives.
- Target potential mispricings early and scan a curated 23 high quality undervalued stocks that filters for quality alongside compressed valuations.
- Lock in income-focused opportunities and review a focused 29 dividend fortresses that highlights higher yielding payouts with supporting fundamentals.
- Prioritise resilience first and walk through a 19 resilient stocks with low risk scores that concentrates on companies with sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com