
Morgan Sindall Group And 2 Other British Undervalued Stocks
Hotter than expected US inflation has kept rate hike worries alive and reminded investors how valuable steady cash generation can be when borrowing costs stay high. British companies that throw off solid cash yet trade below their estimated worth can offer a rare combination of resilience and value. This article picks out three of the most interesting UK stocks where discounted cash flow analysis flags a potential pricing gap.
The three UK stocks covered next are only a sample, drawn from a wider basket of businesses where discounted cash flow work flags a potential gap between cash potential and current share price, and the full screen surfaced 20 more companies with equally compelling stories that are not listed here. To go straight to the source and identify, filter and analyze your own highest conviction ideas from that wider universe, head into the Undervalued Stocks Based On Cash Flows screener.
Morgan Sindall Group (LSE:MGNS)
Overview: Morgan Sindall Group is a UK construction and regeneration specialist focused on partnership housing, mixed-use developments, infrastructure and property services.
Operations: Morgan Sindall Group generated about £1.9b from Fit Out, £920.6 million from Infrastructure and £845.3 million from Partnership Housing, almost entirely in the UK.
Market Cap: £2.1b
Morgan Sindall Group matters for a cash flow focused screen because its long-term regeneration and housing partnerships give unusual visibility on future income, and the analyst consensus Narrative on Simply Wall St outlines how that pipeline could translate into value if execution stays on track.
"Continued expansion of Morgan Sindall Group’s long-term regeneration and housing partnerships, including secured and preferred-bidder pipelines on multi-decade schemes and a housing pipeline of about 55,000 homes, can convert the existing visible workload into future revenue and earnings as schemes move from planning into build phases."
What happens if one pressure on future returns moves differently to what the current cash flow models quietly assume?
If that risk-reward tradeoff matters to you, read the full narrative for Morgan Sindall Group to see where cash generation, capital intensity and cycle sensitivity may be decoupling.
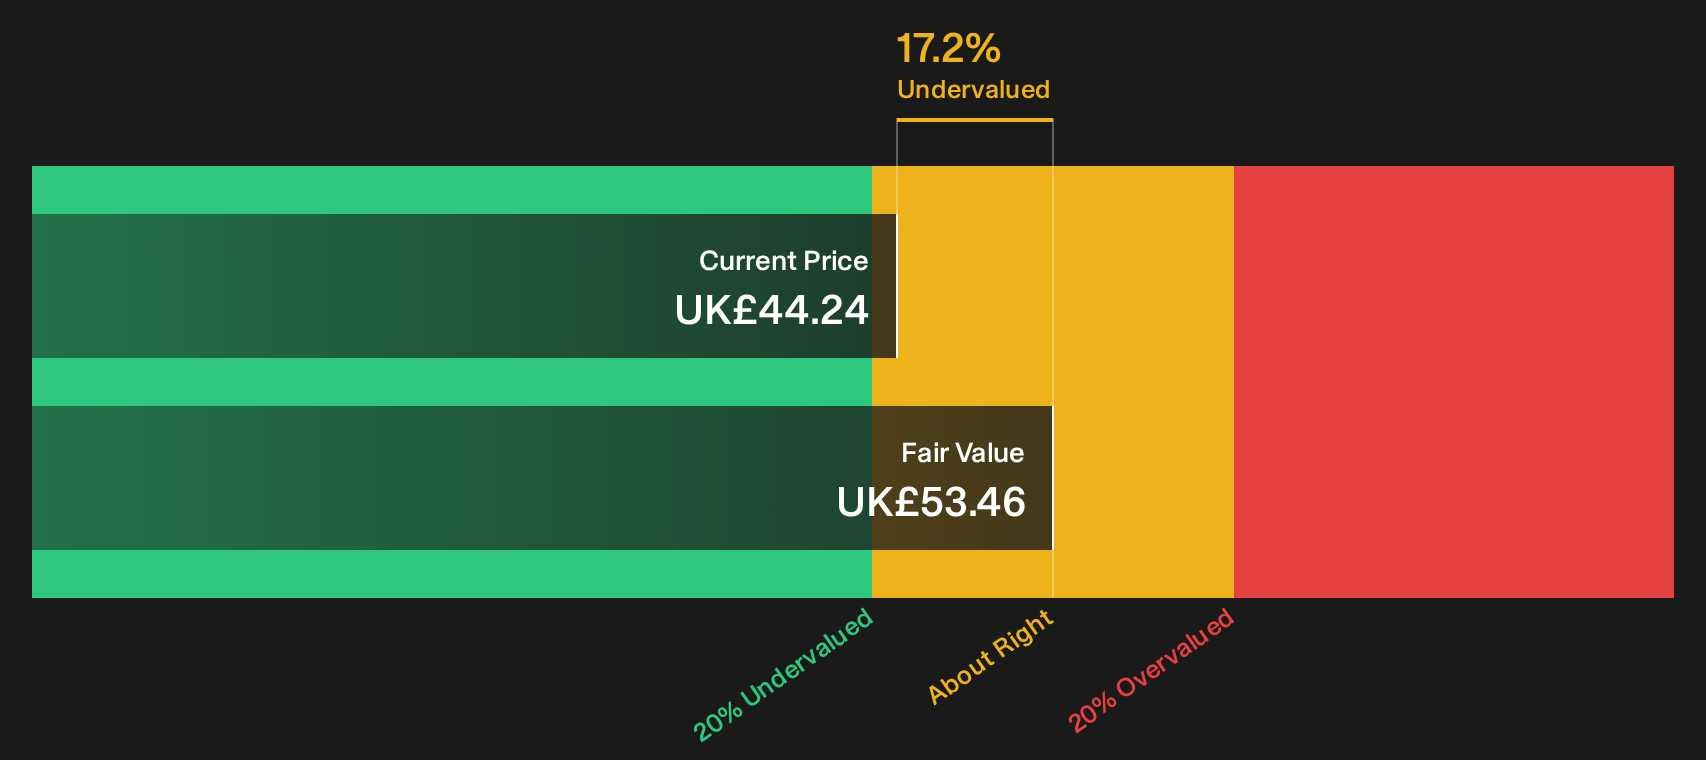
Shell (LSE:SHEL)
Overview: Shell is a global energy and petrochemical group whose downstream refining, marketing and chemicals operations generate substantial cash that fits the undervalued cash flow screener theme.
Operations: Shell produces revenue mainly from Marketing at about US$146.2b and Chemicals and Products at roughly US$142.9b, with Integrated Gas and Upstream together adding around US$100.8b.
Market Cap: £206.3b
For the Undervalued Stocks Based On Cash Flows screen, Shell matters because its refining, retail fuels and chemicals operations generate sizable, relatively steady cash earnings that Composite_Research, an investor in the Simply Wall St Community, argues the market is not fully recognizing in long term models.
"With an LNG portfolio exceeding 60 million tons and unparalleled trading capabilities, Shell is the company that benefits most from the volatility in the global gas market."
What happens to that cash flow story if one quiet shift in demand and pricing power plays out differently to current expectations?
If that shift matters for your portfolio, read the full narrative for Shell to see how Shell’s cash engine could be amplified or quietly constrained.
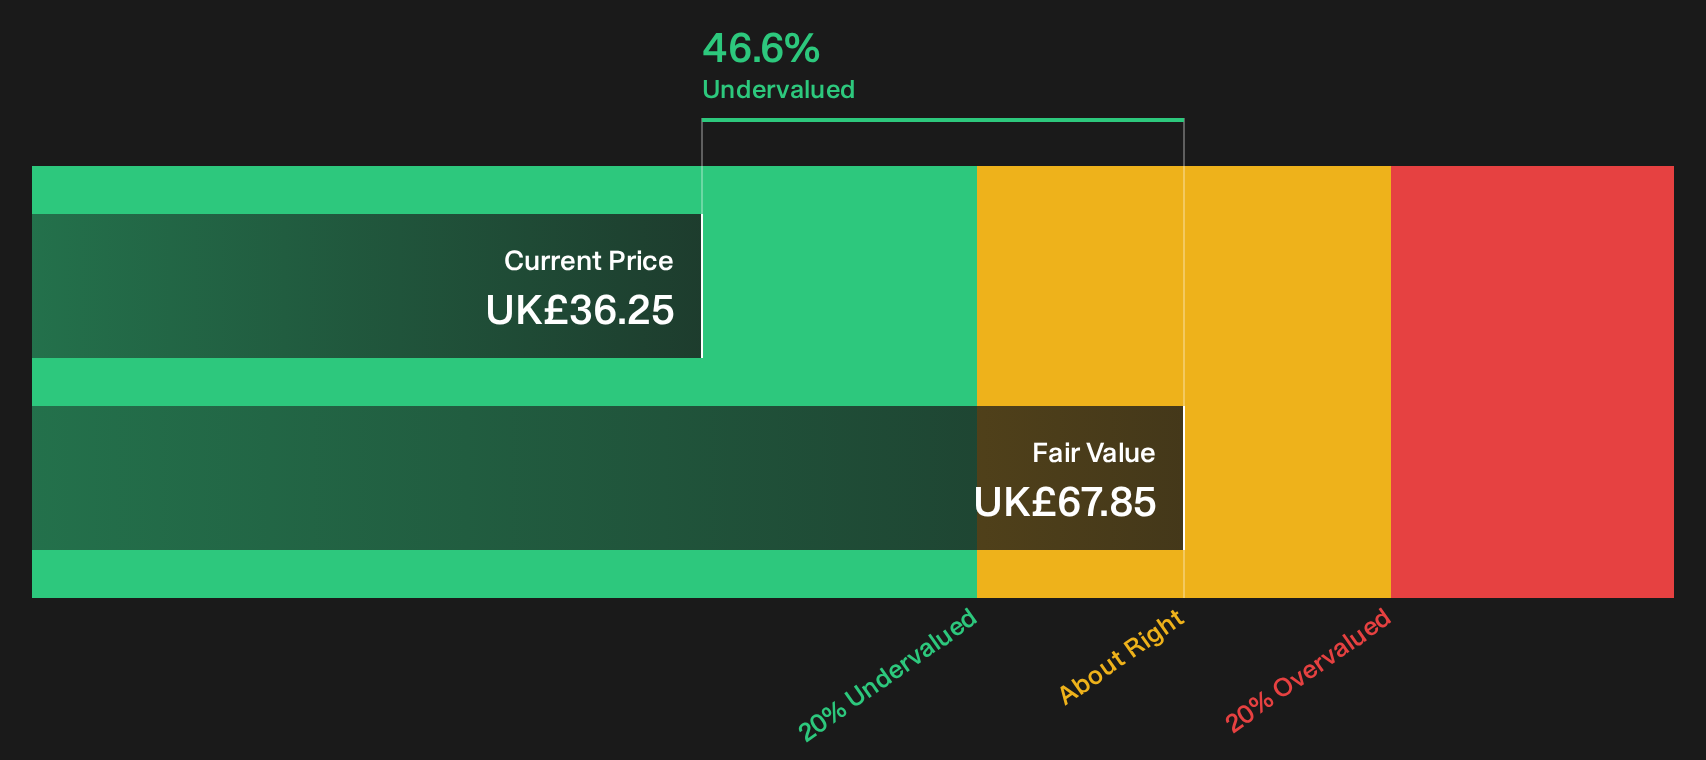
BAE Systems (LSE:BA.)
Overview: BAE Systems is a global defense and aerospace contractor supplying combat aircraft, warships, armored vehicles, munitions, electronics and cyber services under long-term government programs.
Operations: BAE Systems generates most revenue from Electronic Systems at £7.8b, Air at £7.7b and Platforms & Services at £5.3b across primarily US and UK contracts.
Market Cap: £54.4b
BAE Systems matters for an undervalued cash flow screen because the analyst consensus Narrative on Simply Wall St links its contract-heavy defense programs to a long runway of government-backed income that underpins discounted cash flow valuation work.
"The company's order backlog reached £84b with total backlog plus incumbent program positions of around £260b, which equals about 8x annual sales and points to multi year support for revenue and earnings."
The real swing factor is how one capacity and margin assumption inside those programs holds up once expansion, digitalisation and mix shifts are fully tested.
That hinge point is exactly what the full narrative for BAE Systems pulls apart, showing where capacity, pricing and cash generation could be quietly accelerating or stalling in the period ahead.
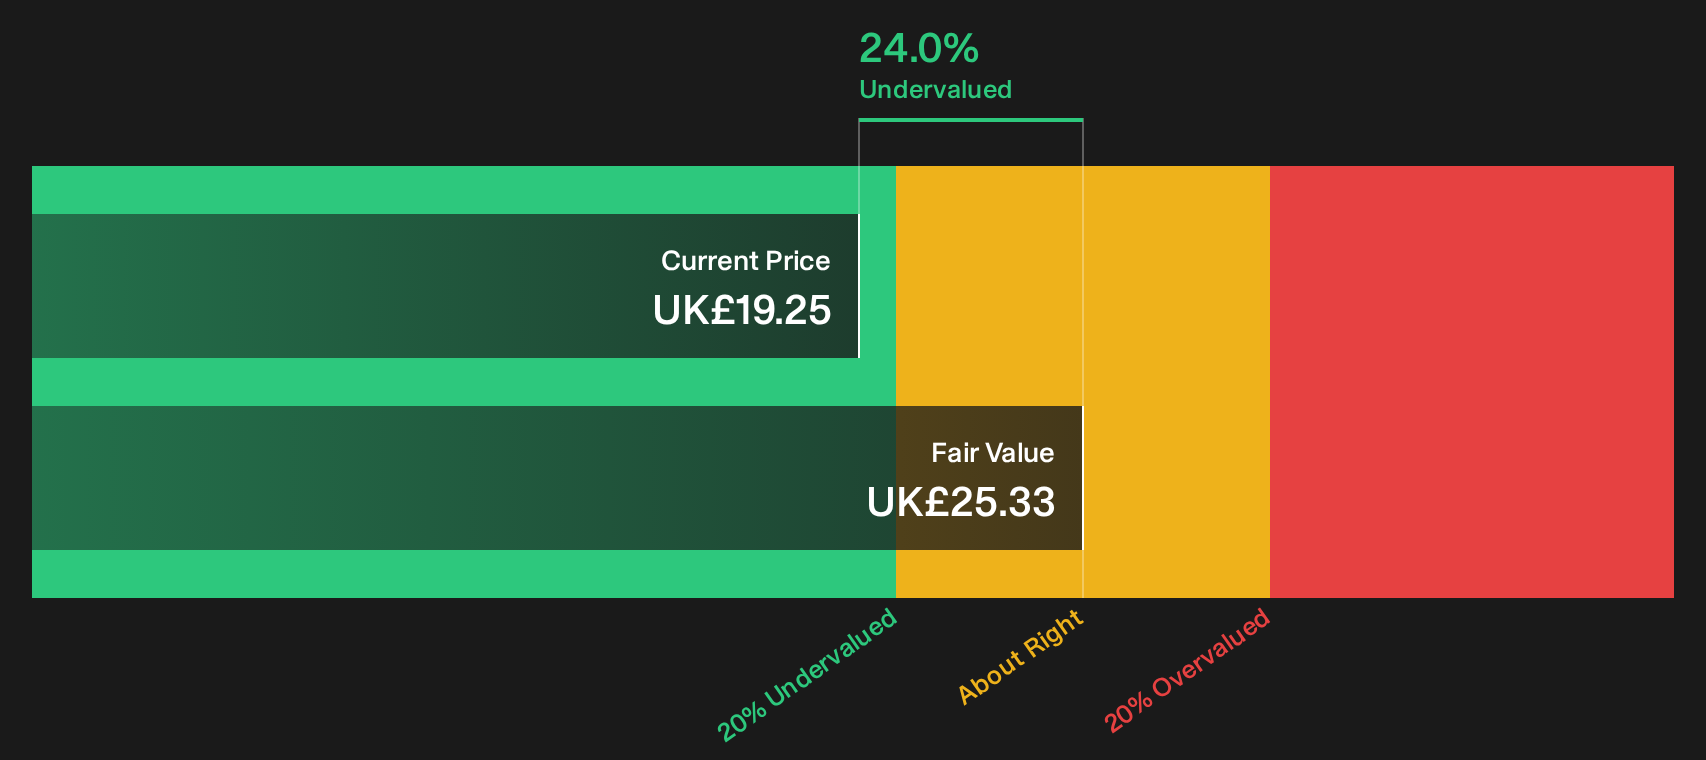
Seeking Fresh Alternatives Before They Fly
Fresh opportunities often move first, then momentum hits and the best entries get crowded. Review the next wave of ideas while it matters and consider acting early.
- Identify income-focused companies designed to keep paying out and scan a curated mix of reliable payers using the 6 dividend fortresses.
- Track early movers in artificial intelligence and filter a focused set of cash-generating opportunities with the 41 profitable AI stocks that aren't just burning cash.
- Look for companies with durable balance sheets before momentum turns toward them and review a refined list of solid balance sheet and fundamentals (9 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com