
What Everforth (EFOR)'s Lower Earnings Outlook Means For Shareholders
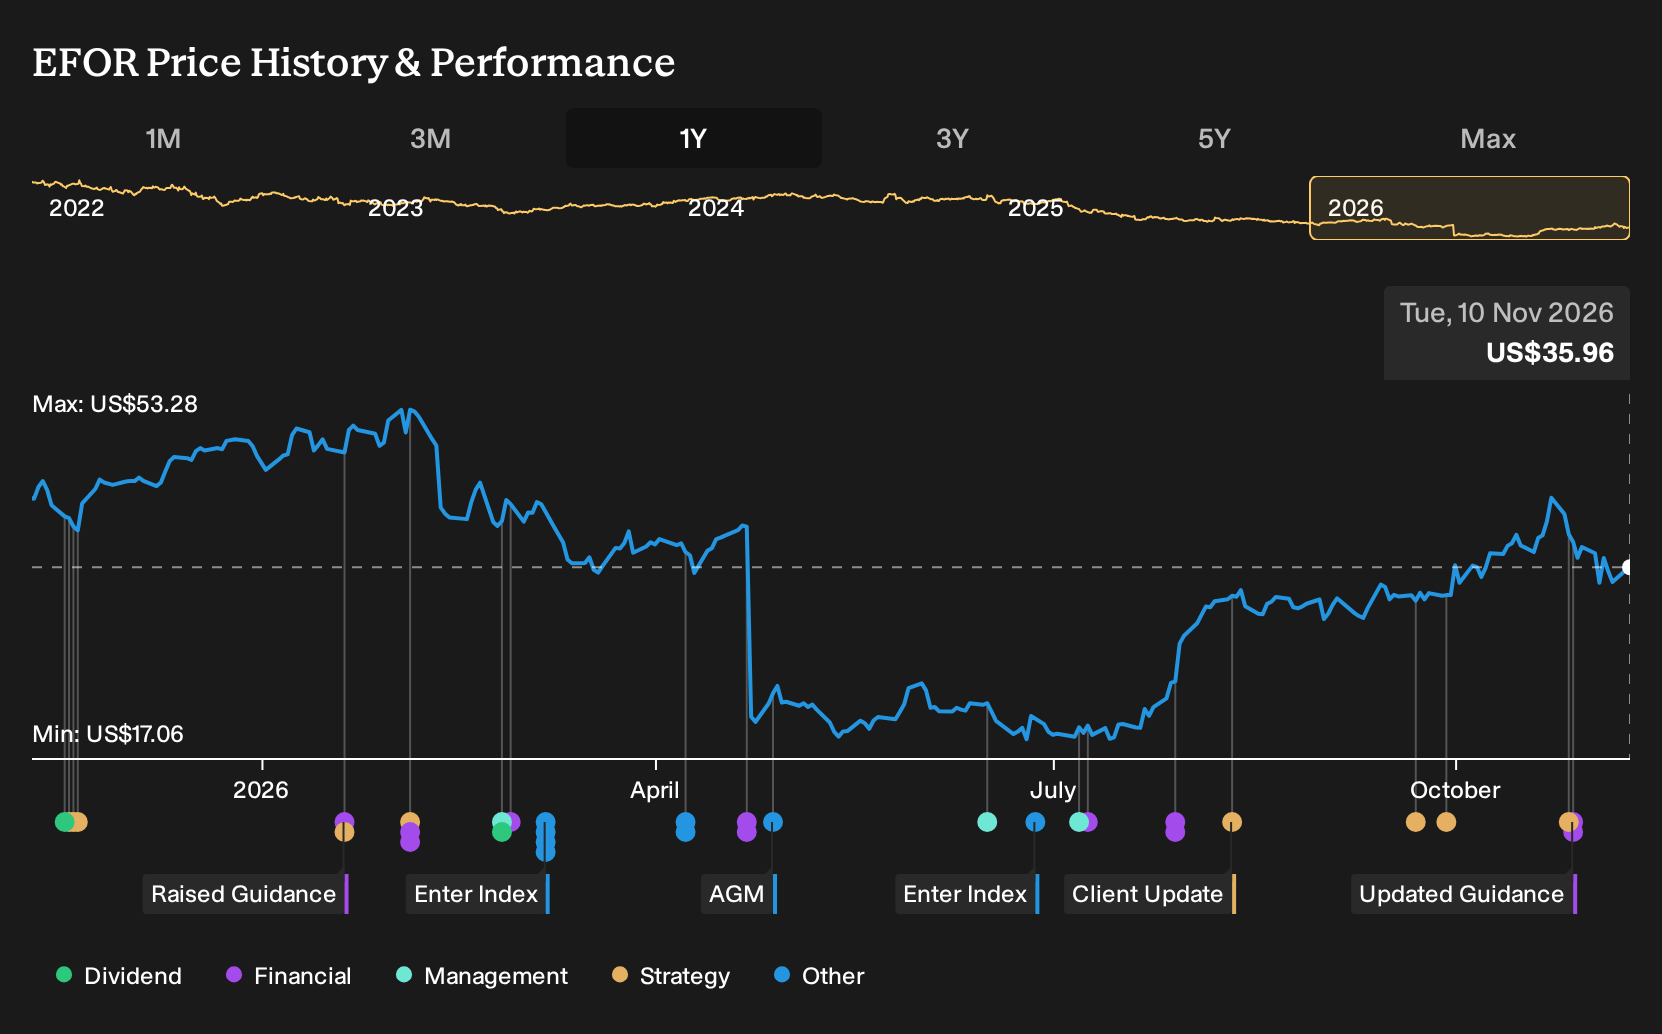
- Everforth, Inc. reported third quarter 2026 sales of US$1,031.4 million with net income of US$23.1 million and diluted EPS of US$0.56, alongside fourth quarter guidance that points to revenues of US$965.0 million to US$995.0 million and net income of US$17.9 million to US$25.5 million.
- The business showed only a small change in year to date sales compared with the prior period, while net income and earnings per share were much lower. This suggests cost pressures or mix issues are weighing more heavily on profitability than on demand.
- The focus now turns to how Everforth's softer earnings guidance interacts with its AI and consulting led investment narrative and margin goals.
Broaden your watchlist by comparing Everforth with a curated group of 20 high quality undiscovered gems that may be flying under the radar after recent earnings resets.
Everforth Investment Narrative Recap
To own Everforth, you need to believe its AI, cloud and cybersecurity consulting focus and federal backlog can offset weaker profitability. The analyst consensus Narrative on Simply Wall St leans on higher margin consulting work, ecosystem partnerships and internal cost programs to support better earnings quality over time, even after a year where profit margins and net income moved lower.
The fresh earnings report and cautious fourth quarter outlook keep the near term story centered on execution. The main near term catalyst is whether healthier commercial trends and federal awards convert into steadier revenue and margin improvement. The biggest risk is that cost pressure persists, leaving debt coverage by operating cash flow tight.
The most relevant update here is Everforth's fourth quarter 2026 outlook. Management guided to revenues of US$965.0 million to US$995.0 million and net income of US$17.9 million to US$25.5 million, with earnings per diluted share of US$0.43 to US$0.62. That range sits against nine month sales that barely moved while profits fell sharply.
For you, the question is whether this guidance period marks a trough in earnings or a reset to a structurally lower profitability level. It ties directly into catalysts like federal AI contracts, consulting mix and structural cost savings. If those drivers do not lift margins, the existing risks around low profit margins and weaker cash coverage of debt remain front of mind.
Everforth's narrative projects US$4.4b revenue and US$188.4 million earnings by 2029. This implies 3.0% yearly revenue growth and an earnings increase of US$120.4 million from US$68.0 million today.
Discover why Everforth's fair value indicates a 7% potential upside to its current price before that discount can close.
Exploring Other Perspectives
Some of the most optimistic analysts frame Everforth’s AI platforms like TotalSight as the real swing factor, not just consulting bookings. Before this earnings miss, the bullish camp was modelling revenue to reach about US$4.4b and earnings of roughly US$222.4 million by 2029. You can treat this as one end of a wide opinion spectrum that may shift after these results.
Explore another Everforth fair value estimate, including one that suggests up to 86% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Everforth research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Everforth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everforth's overall financial health at a glance.
Looking For More Ideas Beyond Everforth?
Once you have a view on Everforth, it can help to pressure test that thinking by lining it up against other businesses that fit different risk and return profiles. The Simply Wall St Screener lets you move from a single ticker to a bench of candidates that match the kind of balance sheet strength, valuation, or growth profile you want to focus on next.
- If capital preservation sits high on your list, start with companies that score well on resilience using a 30 resilient stocks with low risk scores that filters for sturdier fundamentals.
- Income focused investors can zero in on payout strength by scanning through 5 dividend fortresses that combine higher yields with robust underlying businesses.
- For those hunting for potential future leaders before the crowd catches on, widen the search to a 20 high quality undiscovered gems that surface quality fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com