
uniQure (QURE) Stock May Already Look Pricey Following FDA Priority Review
uniQure has delivered a very large 3 year share price gain, yet the recent pullback and fresh clinical milestones raise a simple question for investors who care about fundamentals. Is the current US$22.71 price tag still in step with what the biotech's book value can justify today?
- Over the past 3 years the stock has climbed about 241.2%, which puts a lot more weight on whether the balance sheet now supports that move.
- The FDA priority review for AMT-130 and uniQure's early work on commercial preparation can shift expectations for future profitability and capital needs, both of which matter when you compare the share price with the assets on its books.
- There is a second opinion on uniQure worth weighing. See what analysts think uniQure's shares could be worth.
The issue now is whether uniQure's current market value lines up with its book value when set against the industry average.
If you are weighing whether uniQure's 3 year gain still lines up with its fundamentals, it can help to compare it with companies in our 35 high quality undervalued stocks
Is uniQure Getting Expensive on Book Value?
P/B is a cleanest starting point for uniQure because, for a business with losses and early-stage products, the balance sheet often tells you more than earnings do.
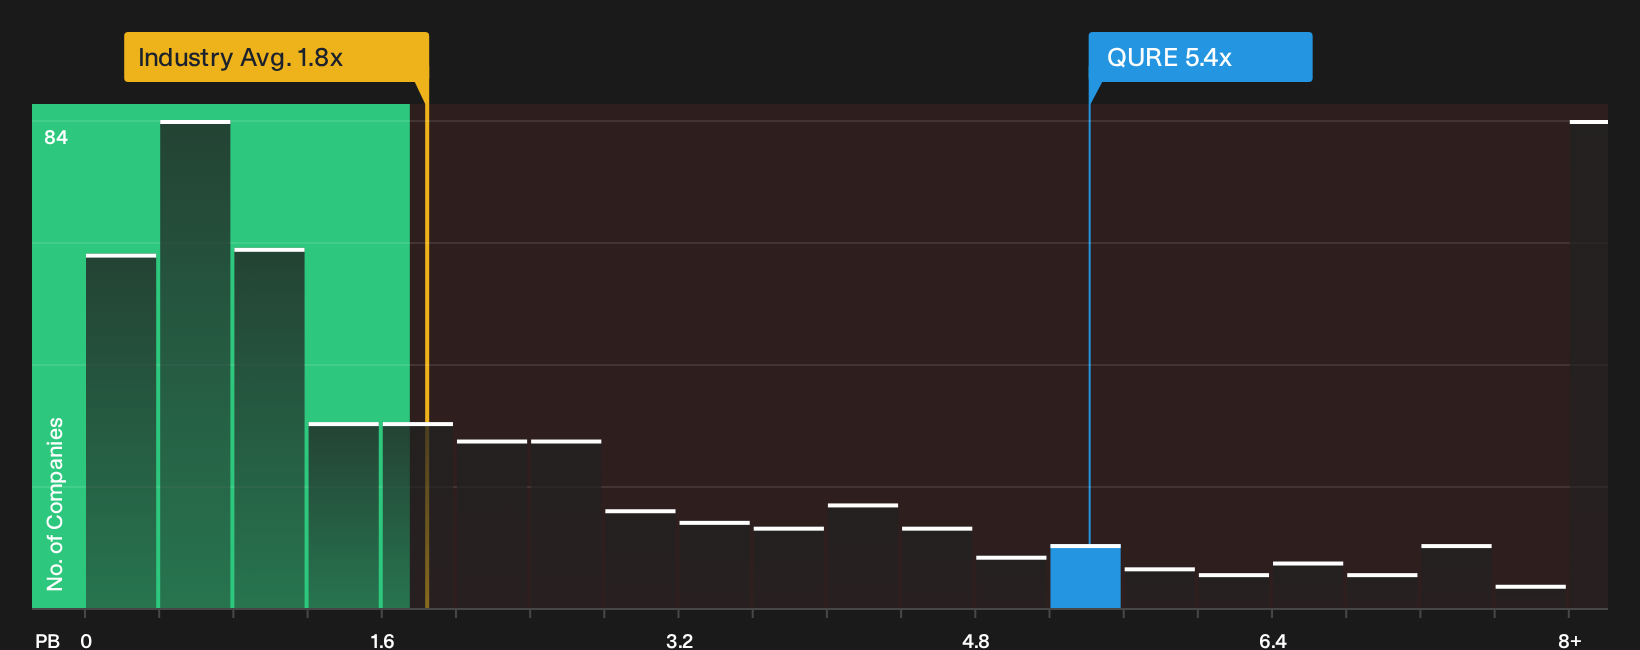
At roughly 5.4x book value, uniQure trades at a higher P/B than the broader Biotechs group, which sits near 1.8x. That gap suggests investors are paying a premium over the typical asset backing seen in the sector, even though the company is still reporting negative free cash flow.
The peer group referenced in this model is around 11.9x P/B, so uniQure comes in below that subset but still screens overvalued against the wider industry yardstick. Because AMT-130 has FDA priority review and a 2027 decision date, the current multiple implies the market is already assigning meaningful value to that pipeline potential rather than to existing equity alone. Explore the numbers behind uniQure's P/B valuation.
The uniQure Narrative: What Would Justify Today's Price?
Narratives pick up where the P/B puzzle for uniQure leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully higher or lower than today. Each one treats uniQure's estimated worth as a thesis about the business that you can revisit over time, and they appear on Simply Wall St's Community page for readers who want that ongoing lens.
One of the top narratives on uniQure: 62% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The numbers imply that the current share price assigns limited value to AMT-130’s potential Huntington’s disease franchise and to uniQure’s broader gene therapy pipeline…"
Discover why this Narrative puts uniQure at 62% undervalued.
The uniQure story still has one unanswered question
Valuation only tells part of uniQure's story, and the research now flags specific risk checks that could change how you weigh everything discussed so far. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com