
Banco Comercial Português (ENXTLS:BCP) Shares Just Climbed, So What Is Driving Attention?
Banco Comercial Português (ENXTLS:BCP) just posted nine month earnings that showed net income of €873.7 million and basic earnings per share of €0.057, both above the figures reported a year earlier.
The earnings release appears to have acted as a fresh catalyst, with Banco Comercial Português trading at €1.146 and posting a 2.05% one-day share price return and 9.35% over the past week. Its 1-year total shareholder return of 49.66% sits on top of an even stronger multi-year record, suggesting momentum has been building rather than fading.
Scan Banco Comercial Português alongside a hand-picked 202 high quality undervalued stocks that also show improving earnings trends and recent share price momentum.
The question now is whether Banco Comercial Português’s sharp run reflects a healthier earnings engine or a sentiment swing that has run ahead of itself, a distinction that the valuation now needs to clarify.
Most Popular Narrative: 4.5% Undervalued
At a last close of €1.146, Banco Comercial Português sits a touch below the analyst consensus Narrative fair value of €1.20. The analyst consensus Narrative on Simply Wall St builds this estimate from detailed revenue, earnings and discount rate assumptions rather than a single headline target.
The combination of capital ratios above regulatory minima and organic capital generation may provide room to finance balance sheet growth and potentially support higher shareholder distributions over time, contributing to book value per share growth and total shareholder returns.
See why 17 investors see Banco Comercial Português as 5% undervalued.
Result: Fair Value of €1.20 (UNDERVALUED)
Still, the bullish Banco Comercial Português story can be knocked off course if interest rates fall faster than expected or if SME and corporate credit losses rise above plans.
Find out about the key risks to this Banco Comercial Português narrative.
Another View on Banco Comercial Português Valuation
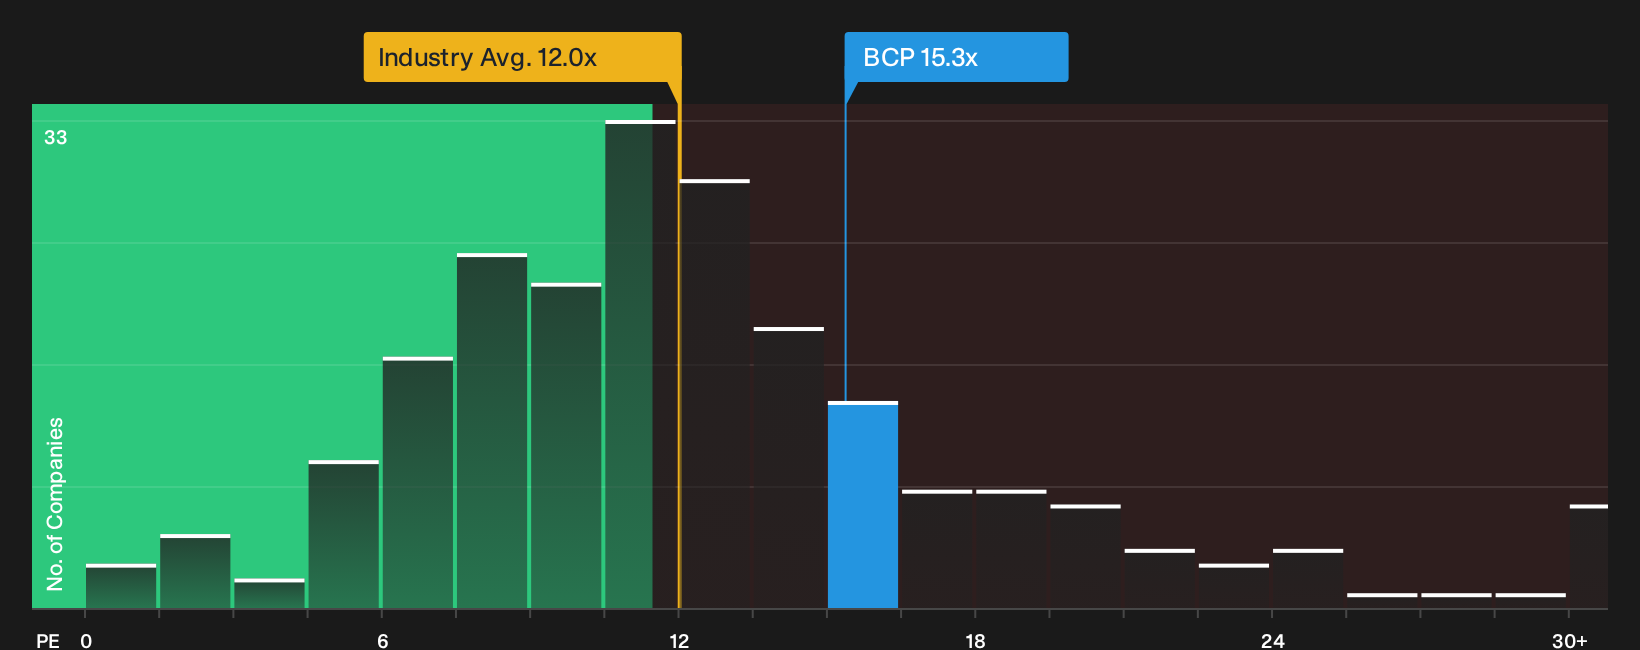
The analyst narrative points to Banco Comercial Português as modestly undervalued, yet the market is currently paying a P/E of 15.3x compared with 11.9x for the wider European Banks industry and 11.4x for peers. That richer multiple can signal optimism, but it also raises the bar for future delivery.
Investors who prefer to lean on earnings multiples rather than cash flow models may want to ask a simple question. Is paying a premium P/E for BCP a risk worth taking if sentiment cools or sector valuations drift back toward peer levels, or does the current earnings profile justify staying on the expensive side of the group?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Banco Comercial Português story so far feels balanced, with clear positives and clear risks, this is the moment to dig into the numbers yourself and move quickly to form your own stance based on the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Banco Comercial Português?
If Banco Comercial Português has sharpened your view on valuation and momentum, broaden your watchlist now so you are not late to the next opportunity.
- Target potential outperformance by hunting for quality companies trading below their estimated worth through the 202 high quality undervalued stocks.
- Strengthen your focus on financial resilience by scanning a list of solid balance sheet and fundamentals (195 results) that can better withstand shocks.
- Boost your income toolkit by reviewing 217 dividend fortresses that combine higher yields with disciplined payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com