
Coinbase Global (COIN) Could Be 47% Undervalued As Regulators Clear Two Key Hurdles
Coinbase Global (COIN) just cleared two big regulatory hurdles, with a full federal trust charter and New Jersey lifting its long staking ban. Both shifts are now shaping how investors reassess the stock.
The regulatory wins have arrived amid a tougher market backdrop for Coinbase Global, with the share price closing at US$132.13 and recording a 30-day share price return of negative 26.75% and a year-to-date share price return of negative 44.14%. Over a three-year period, the total shareholder return is up 34.62%, while the one-year total shareholder return is down 56.54%.
Scan how regulators and market volatility are reshaping crypto platforms like Coinbase Global, then size up a curated list of peers through the 21 cryptocurrency and blockchain stocks
After a sharp reset in Coinbase Global’s share price, fresh federal and state approvals have altered the risk profile. Is most of the rerating already in the rear-view mirror, or does the recent slide still leave meaningful upside on the table?
Most Popular Narrative: 47% Undervalued
Against Coinbase Global's last close at $132.13, the most followed narrative on Simply Wall St pegs fair value at $247.39, implying a large valuation gap that some investors are watching closely.
According to QuanD, an investor in the Simply Wall St Community who wrote the narrative, Coinbase Global is better treated as a leveraged expression of long term crypto adoption rather than a conventional financial stock with smooth, linear progress.
I think Coinbase is best understood as a leveraged bet on long-term crypto adoption, rather than a normal operating business with smooth, predictable growth.
What matters most is not whether next year looks clean, but whether crypto becomes a meaningfully larger asset class over time.
See why 29 investors see Coinbase Global as 47% undervalued.
The fair value in that narrative uses a discount rate of 8.07% and arrives at $247.39, which sits well above both the current market value and the analyst price target of $196.56. That framing puts more weight on where crypto as an asset class might end up over time than on the current loss of $701.62m on $5.44b of revenue.
Result: Fair Value of $247.39 (UNDERVALUED)
Still, the narrative leans heavily on crypto prices and trading volumes; prolonged weakness or tighter regulation around Coinbase Global’s core services could quickly challenge it.
Find out about the key risks to this Coinbase Global narrative.
Another View On Coinbase Global’s Valuation
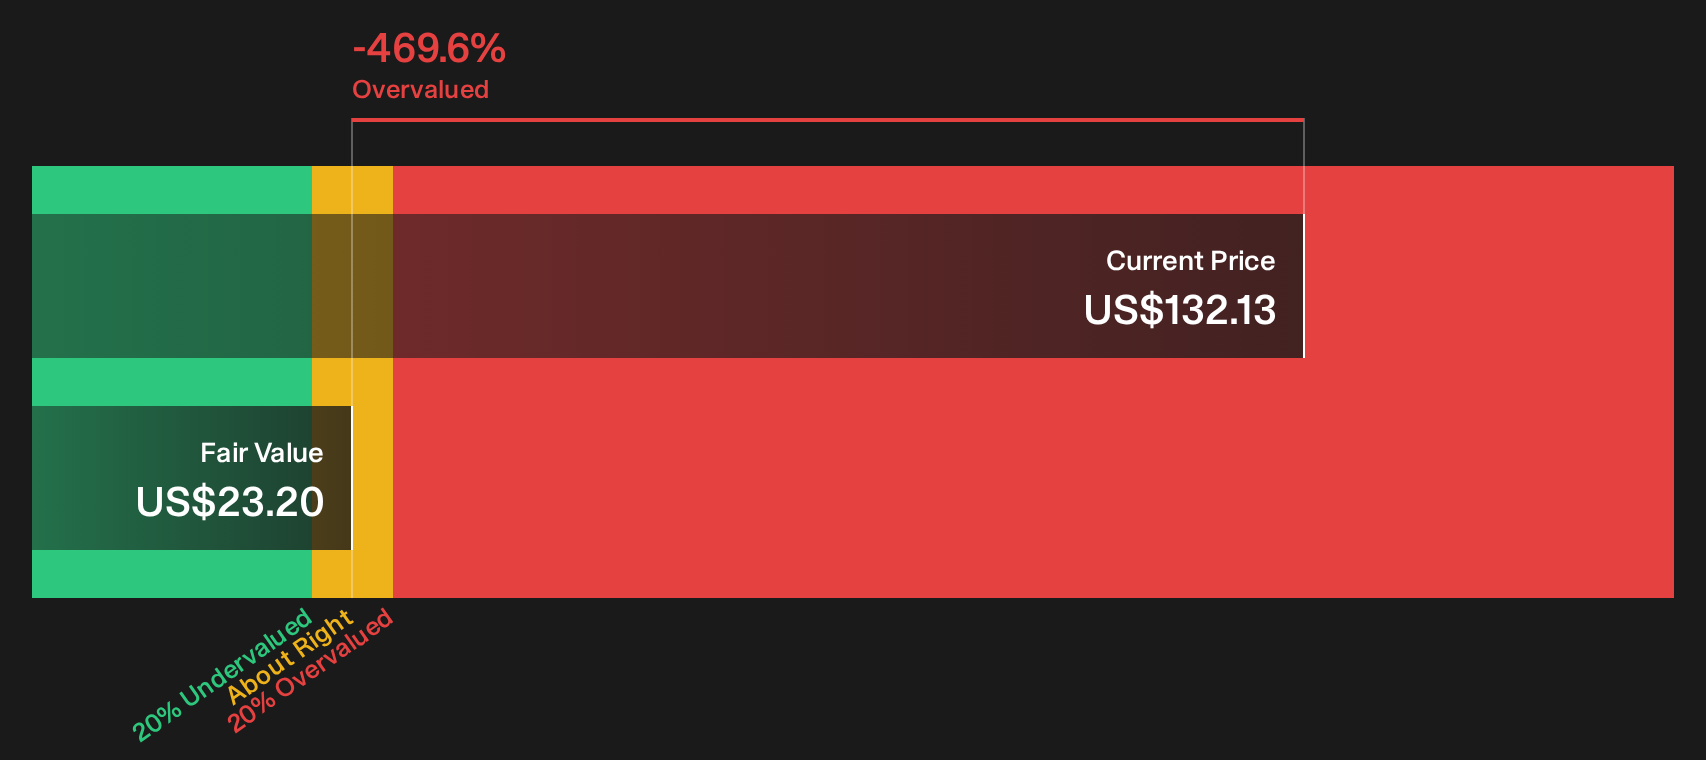
The community fair value narrative paints Coinbase Global as materially undervalued at $247.39. A different lens tells a cooler story. Our DCF model estimates the value of future cash flows at just $23.20 per share, which points to the current $132.13 price looking expensive instead.
That gulf between a community fair value above $200 and an internal cash flow estimate near $20 raises a practical question for investors. Which matters more for you: long term crypto adoption assumptions, or the harder math of discounted cash flows under more conservative scenarios?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Coinbase Global's value and risk profile leave plenty of room for debate, so move quickly, test the numbers for yourself, and weigh both sides through the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Coinbase Global?
If Coinbase Global has sharpened your thinking, do not stop here. Use the Simply Wall St Screener to widen your watchlist with fresh, data driven ideas.
- Target resilient cash generators and stress test your downside by scanning a 30 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier fundamentals.
- Hunt for mispriced quality and pressure test your value thesis with a curated 35 high quality undervalued stocks that pairs financial strength with attractive valuations.
- Spot early stage potential and sharpen your risk reward calls by reviewing a tightly screened 10 elite penny stocks with strong financials built around financial health, not hype.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com