
Natural Resource Partners (NRP) Stock Looks Fully Valued After Debt Repayment
Natural Resource Partners has delivered very strong long term gains, which naturally puts the focus on whether the current unit price lines up with the earnings behind it. With the stock now reflecting years of solid total returns, the key issue for you is what those earnings are really worth today.
- Over the past 5 years the stock has returned about 4.4x, which puts a lot of weight on whether current profits can support that kind of re-rating.
- The recent decision to fully repay debt and lift the quarterly distribution may support different assumptions about how much of Natural Resource Partners' future earnings can be shared with unitholders rather than reserved for the balance sheet.
- Would you pay the same price for Natural Resource Partners's peers? See how Natural Resource Partners's 16.2x P/E compares with its peers.
The issue now is whether the recent unit price fairly reflects Natural Resource Partners' earnings when set against the industry average.
If you want more context around Natural Resource Partners' 5 year return of about 4.4x and its higher Q3 2026 payout, it can help to compare it with other income focused partnerships via 5 dividend fortresses.
Is Natural Resource Partners Getting Expensive on Earnings?
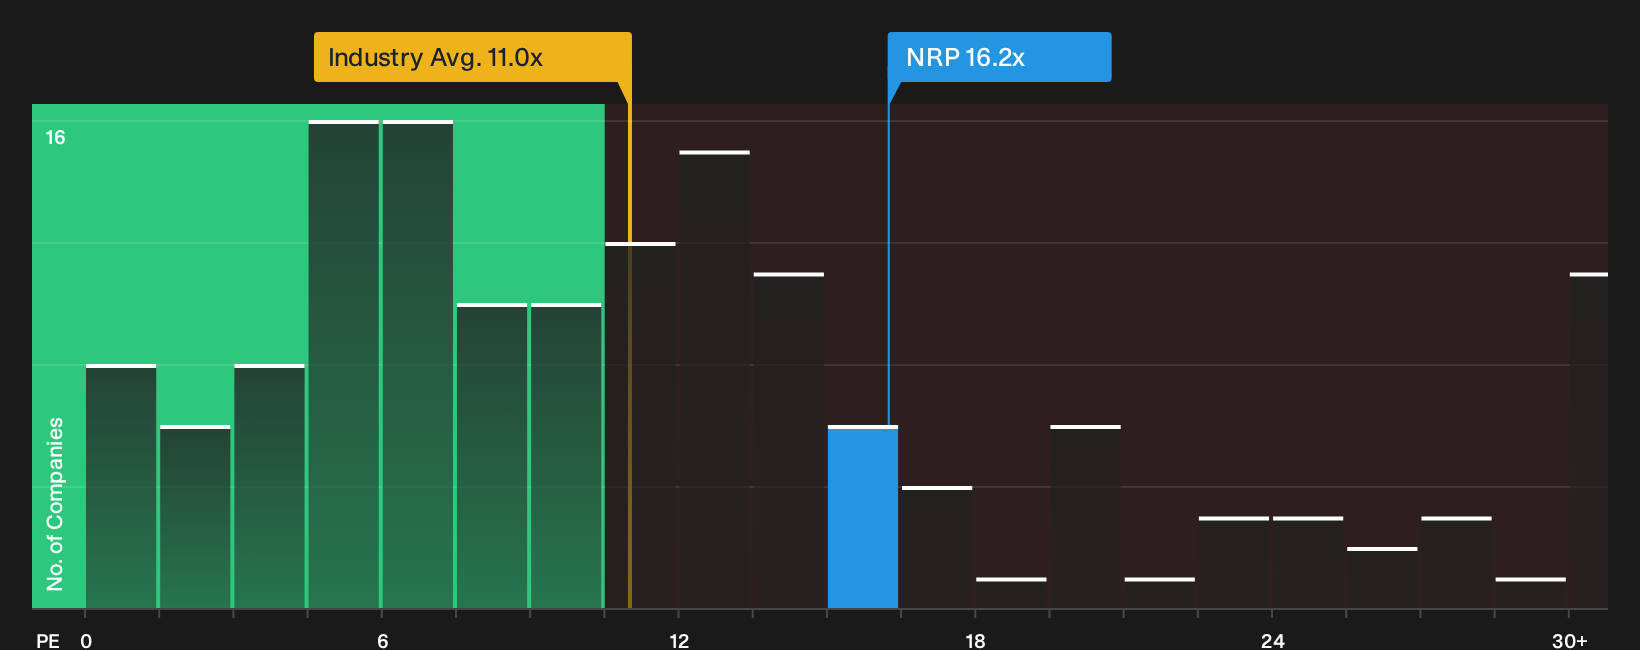
The P/E ratio suits Natural Resource Partners because earnings per unit are a core driver of what unitholders ultimately receive. On this metric, the stock trades on about 16.2x earnings, which is higher than the Oil and Gas industry average of roughly 11.0x. That premium suggests investors are paying more for each dollar of profit than they pay across the typical listed operator in the sector.
Despite the recent jump in the quarterly distribution after full debt repayment, Natural Resource Partners still trades at a discount to the broader peer set on roughly 27.5x. That mix of a premium to the sector but a lower tag than peers points to the market treating the partnership as relatively high quality versus the average producer, but not pricing it as aggressively as the most richly valued group. For you as a unitholder, the key judgement is whether the current earnings power and payout profile justify that above industry earnings multiple. Explore the numbers behind Natural Resource Partners's P/E valuation.
The Natural Resource Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Natural Resource Partners pick up where the P/E puzzle leaves off and explain the future growth, margin and earnings paths that would need to occur for the stock to be worth materially more or less than today’s price. These narratives sit on the Community page so you can see how other investors frame those trade offs. Rather than relying on a single multiple or model output, each narrative lays out its own fair value assumptions so you can later compare them with the partnership’s actual results as they are reported.
A written, numbers based Narrative on Natural Resource Partners lets you spell out the assumptions behind today’s earnings multiple and distribution profile so they can be checked against what the partnership actually delivers over time. With the recent move to repay debt, lift the quarterly payout to US$2.34 per unit and explore areas like renewable energy and carbon sequestration, a clear framework gives you a way to judge whether Natural Resource Partners' future cash generation and risk profile continue to support the current unit price.
Share your own Narrative for Natural Resource Partners and set out the assumptions behind your valuation.
Natural Resource Partners’ valuation is only part of the picture
Price, earnings and distributions tell an important story for Natural Resource Partners, but the checks behind the scenes raise separate business and financial concerns that deserve your attention before you rely on the headline multiples. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com