
What Are Wall Street Analysts' Target Price for Zoetis Stock?
Parsippany, New Jersey-based Zoetis Inc. (ZTS) is a leading global animal health company engaged in the discovery, development, manufacturing, and commercialization of medicines, vaccines, diagnostics, and other healthcare products for companion animals and livestock. Valued at $34 billion by market cap, the company also offers parasiticides, vaccines, dermatology, anti-infectives, pain and sedation, other pharmaceutical, and animal health diagnostics.
Shares of this world’s leading animal health company have notably underperformed the broader market over the past year. ZTS has declined 31.2% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. In 2026, ZTS stock is down 34.5%, compared to the SPX’s 9.9% rise on a YTD basis.
Narrowing the focus, ZTS has also trailed the ProShares Pet Care ETF (PAWZ). The exchange-traded fund has declined about 3.4% over the past year and 1.8% in this year.
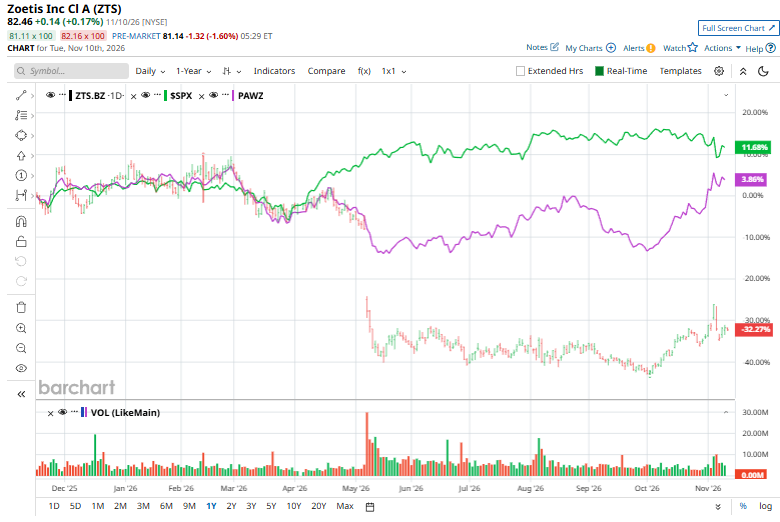
On Nov. 5, Zoetis released its FY2026 Q3 earnings, sending shares down 8% as investors remained concerned about persistent weakness in its companion animal business and a cautious outlook for 2027. Although adjusted EPS of $1.75 increased 2.9% year over year and beat analyst expectations of $1.51, revenue declined 1.3% year over year to $2.39 billion.
Although management raised its FY2026 adjusted EPS guidance to $6.25–$6.35 from $6.15–$6.25, investors were disappointed by its cautious 2027 outlook, which assumes no meaningful recovery in pet-owner spending or competitive conditions.
For the current fiscal year, ending in December, analysts expect ZTS’ EPS to fall 1.9% to $6.29 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in three of the last four quarters while missing the forecast on another occasion.
Among the 16 analysts covering ZTS stock, the consensus is a “Moderate Buy.” That’s based on four “Strong Buy” ratings, one “Moderate Buy,” and 11 “Holds.”
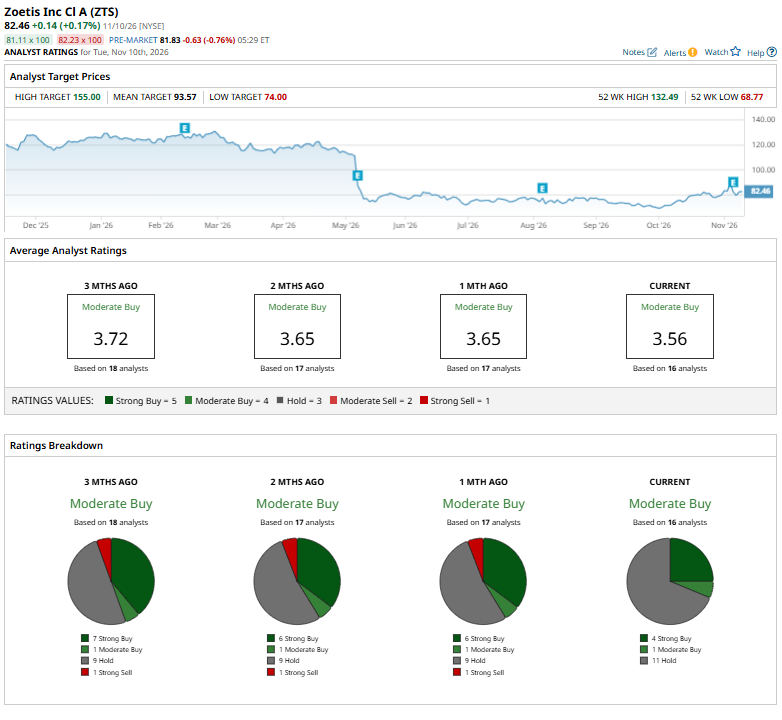
This configuration is bearish than a month ago, with six analysts suggesting a “Strong Buy.”
On October 20, Jefferies downgraded Zoetis to “Hold” from “Buy” and slashed its price target to $83 from $103, citing a softer pricing environment. Analyst Keith Devas noted that pricing accounted for 64% of the company's earnings growth between 2022 and 2025, leaving weaker sales volumes to constrain future profit growth. The firm also expressed concerns about limited earnings visibility and the potential for further margin resets, warranting a lower valuation multiple.
The mean price target of $93.57 represents a 13.5% premium to ZTS’ current price levels. The Street-high price target of $155 suggests an ambitious upside potential of 88%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.