
Five Below (FIVE) Stock Looks Fully Valued After Its 69% Run
Five Below has enjoyed a strong run, and the jump in the share price now puts the focus squarely on whether the retailer's cash flows can carry that valuation. With cash generation in the spotlight, investors are asking if the recent enthusiasm around the stock is fully backed by what the business can earn and reinvest over time.
- The stock is up 68.9% over the past year, which raises the stakes on whether the current market value lines up with the cash the business can realistically produce.
- Truist's optimism around process improvements and higher estimated earnings suggests the market may be baking in expectations of stronger future cash generation, as well as potentially smoother cash flow growth beyond the current product cycle in areas like 'squish' toys.
- What if you looked at Five Below through its earnings instead? See what Five Below's 22.5x P/E says about the price.
The issue now is whether the recent share price level for Five Below is fully supported by the cash flows implied by a Discounted Cash Flow (DCF) style intrinsic value estimate.
If you are considering whether Five Below's 68.9% one year return is fully supported by its cash flows, it can help to compare the company with those filtered through 35 high quality undervalued stocks
Has Five Below Run Too Far on Cash Flow?
The Discounted Cash Flow (DCF) model used here estimates what Five Below might be worth based on the cash it is expected to generate for shareholders. On the latest numbers, the retailer produced trailing twelve month free cash flow of about $471.7 million, and the model projects this moving into the mid $500 million range over the next decade, then flattening into relatively steady levels. That path looks more like a maturing cash engine than a hyper growth story.
Those cash flow assumptions still leave the DCF estimate substantially below the current share price of $253.51. Truist's raised expectations around process efficiencies and earnings add a supportive narrative, yet the stock price already reflects a richer outlook than the cash flow model supports on its own. That gap is what you are really weighing when you compare the recent share price with the estimated intrinsic worth from the cash flows. Find out what Five Below could be worth using our Discounted Cash Flow (DCF) estimate.
The Five Below Narrative: What Would Justify Today's Price?
Five Below's valuation puzzle only gets useful once you spell out the stories that could make the current price look either stretched or conservative, and that is where Simply Wall St Narratives come in on the Community page. Each one links its number to a clear view on where Five Below's growth, margins and key risks might head next. You can revisit these as fresh results and new information come through.
The two Five Below Narratives are pulling in different directions, which matters when the current cash flow model already looks tight against the share price.
Bull case: 18% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which focuses on store rollout and capital deployment as the key drivers.
"The main thing that has to go right is that Five Below continues to convert its store expansion runway, higher price point mix, and new store experience investments into healthy traffic…"
Discover why this Narrative puts Five Below at 18% undervalued.
Bear case: 12% overvalued
This angle is taken from the bearish analyst Narrative on Simply Wall St, which focuses more on legal, compliance and cost pressure.
"Sustained fuel and inland trucking inflation that is already estimated as a 20% to 25% of a percentage point drag on 2026 margin, combined with plans to keep investing about US$40,000 to US$45,000 per store within a US$250m to US$260m annual capex plan for store redesigns, increases the risk that freight headwinds and capital intensity outpace merchandise margin gains…"
Explore why this Narrative puts Five Below at 12% overvalued.
One more question for Five Below that valuation alone cannot answer
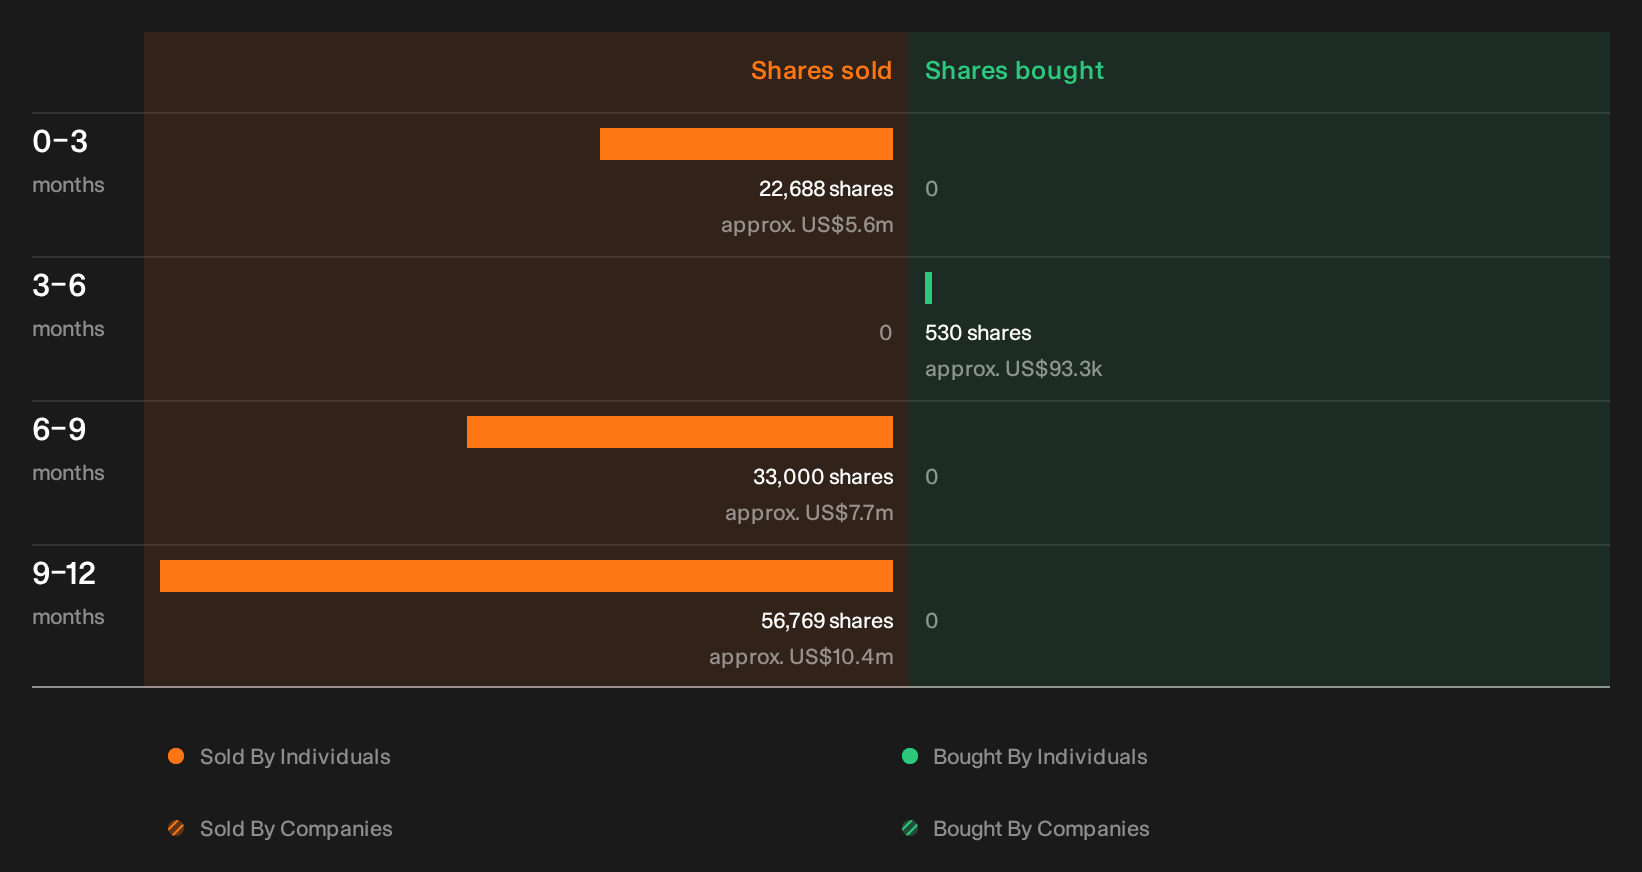
Price, cash flow and narratives tell only part of the story for Five Below, and recent trading activity by people inside the business adds another layer that readers often watch closely for signals. See the recent insider selling flagged for Five Below.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com