
Astronics (ATRO) Returned To Profit, Is The Valuation Upside Still There?
Astronics (ATRO) just posted third quarter 2026 results that sharply contrast with last year, moving from a net loss to US$52.2 million in profit on US$271.68 million in sales.
Astronics shares jumped 5.1% on the day of the release to US$62.00 as investors reacted to the swing back into profitability, although the 90 day share price return is still down 29.5% after a softer 30 day move. Over a longer stretch, momentum has been strong, with a 55.2% 1 year total shareholder return and a very large 5 year total shareholder return that points to buyers rewarding the turnaround and reassessing the risk profile.
Scan beyond Astronics and identify other aerospace and defense plays with strong momentum in earnings and backlogs using our curated 30 resilient stocks with low risk scores.
Astronics now trades well below analyst targets even after the post earnings pop. The real puzzle is whether that discount reflects lingering risk or a market that is too cautious on the turnaround.
Most Popular Narrative: 37% Undervalued
Astronics closed at $62.00 against an analyst consensus fair value of $98.00, and the analyst consensus Narrative on Simply Wall St ties that gap directly to earnings and margin forecasts using an 8.28% discount rate.
Analysts expect Astronics to convert record commercial aerospace demand, growing IFEC and passenger power adoption, stronger electrical power programs, and a healthier Test Systems business into continued revenue growth and higher profitability over time.
See why 15 investors see Astronics as 37% undervalued.
Result: Fair Value of $98 (UNDERVALUED)
Still, the Astronics story can change quickly if tariff costs stay elevated or if execution stumbles on the TS 4549/T radio test program.
Find out about the key risks to this Astronics narrative.
Another View: Astronics Through The P/E Lens
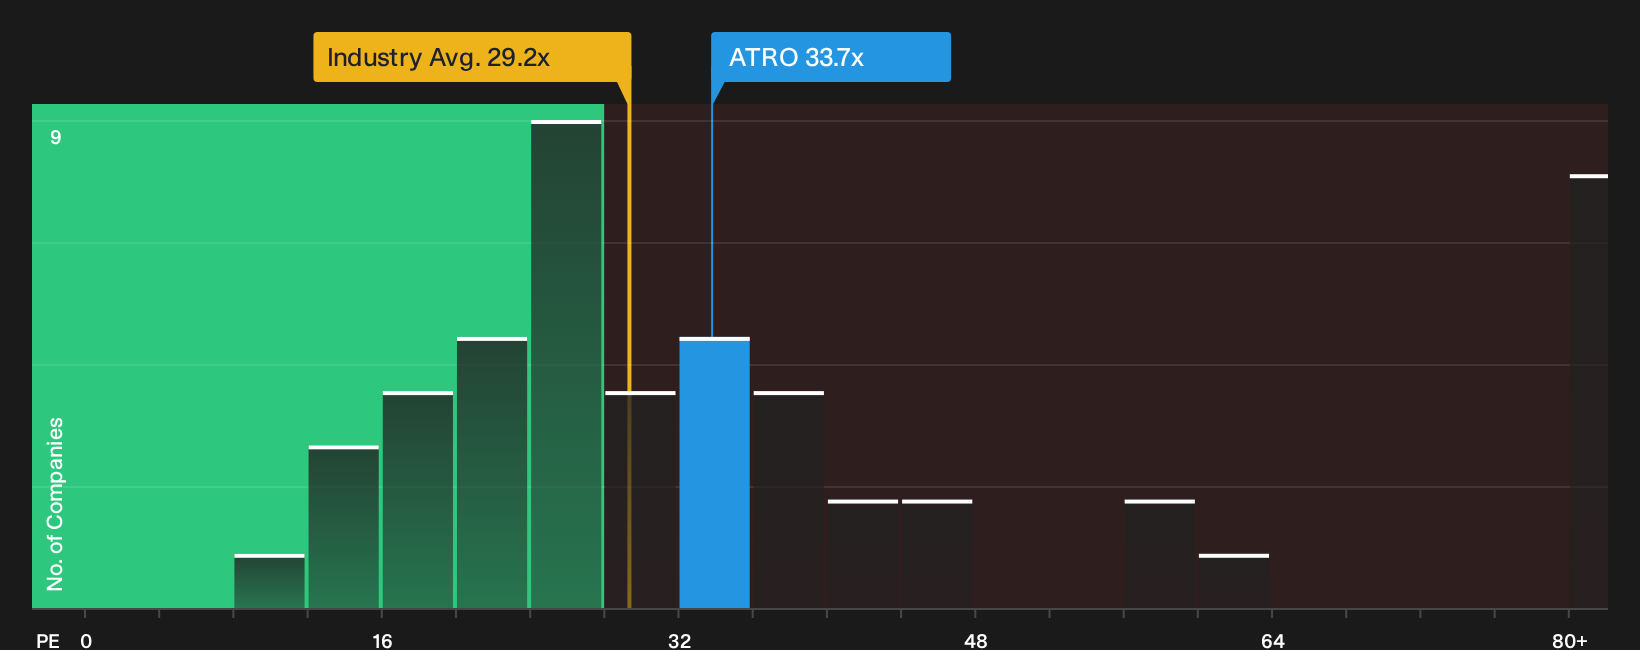
Step away from the analyst fair value and the picture shifts. Astronics trades on a P/E of 33.7x, above both the US Aerospace & Defense sector at 29.1x and a peer average of 31.6x. It also matches a fair ratio of 33.7x that the market could gravitate toward over time.
This combination points to a stock that already prices in plenty of earnings growth, with limited room for disappointment if forecasts slip or execution on key programs wobbles. The question for investors is whether the current multiple feels like a cushion or a tightrope.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Astronics presents mixed signals so far, with valuation, earnings quality and sentiment all pointing in different directions. Put the numbers in context and decide whether the risk reward trade off suits your style by weighing its 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Astronics?
Do not stop with Astronics. Apply the same discipline across the market to give yourself more ways to spread risk and identify opportunity early.
- Target resilient balance sheets and steady fundamentals with a focused list of solid balance sheet and fundamentals (24 results) that filters for financial strength before excitement.
- Hunt for mispriced quality by scanning our curated 35 high quality undervalued stocks that highlight companies the market may be treating with too much caution.
- Build a watchlist of potential future winners by reviewing a 20 high quality undiscovered gems that the crowd has not fully noticed yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com