
National Health Investors (NHI) Stock May Be Undervalued Despite Strong Q3 Results
National Health Investors has delivered a solid multi‑year share price gain while also reshaping its portfolio around senior housing, which puts fresh attention on a simple question for you as an investor: Is the current US$67.79 price tag adequately supported by what the trust earns today and what those earnings may look like over time?
- Over the past 5 years the stock has returned about 58.8%, so anyone buying now is effectively paying up for a business that has already rewarded patient holders and must decide whether its earnings can carry that track record forward.
- Recent asset sales and new senior housing investments have shifted the mix of properties, which can influence how stable National Health Investors' rental income looks and how much headroom there is for future earnings growth and dividends.
- The analysts covering National Health Investors have run their own numbers. See what analysts think National Health Investors's shares could be worth.
For investors, the debate is whether the current share price is fully justified by National Health Investors' earnings power once you set the recent performance and portfolio changes against what the income statement is actually delivering.
You can consider the same earnings question for other companies by scanning solid balance sheet and fundamentals stocks screener (24 results).
Is National Health Investors a Bargain on Earnings?
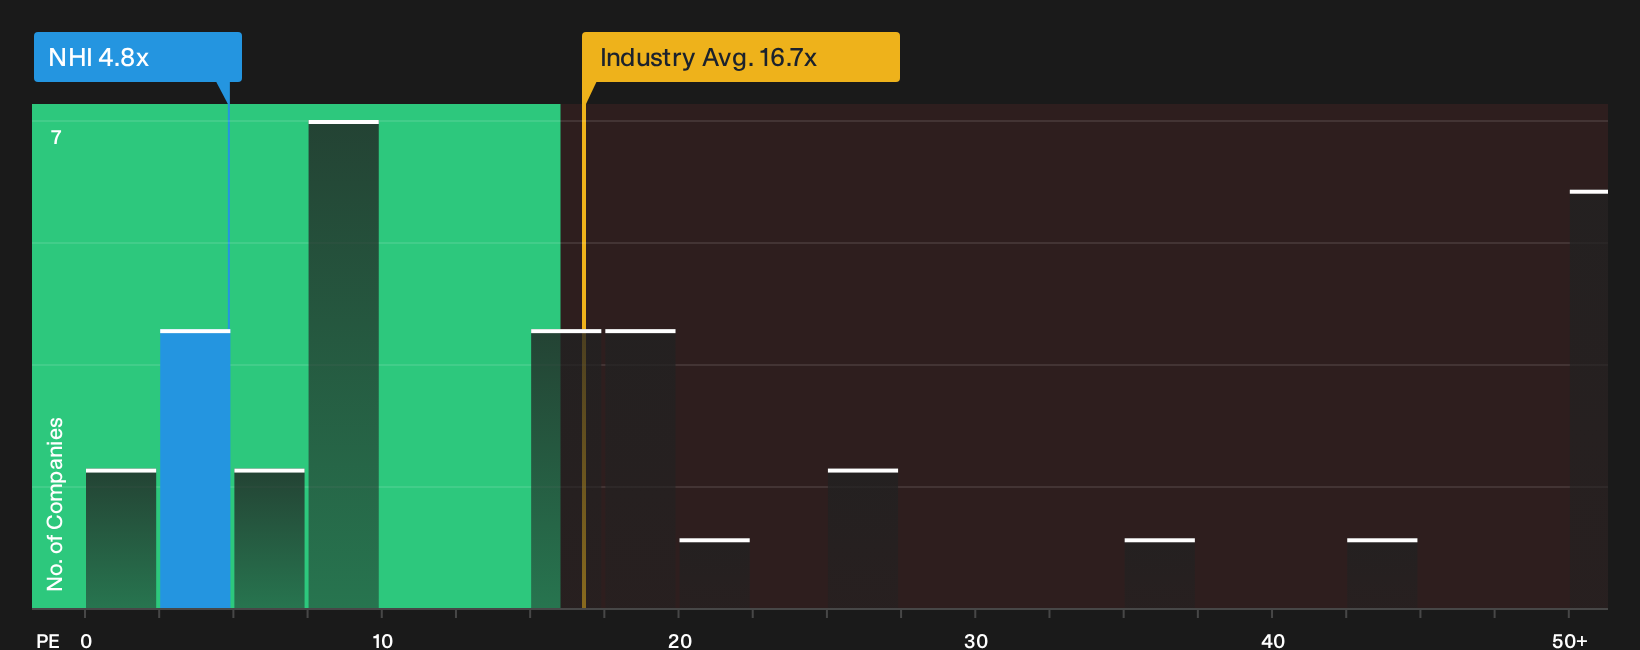
The P/E ratio suits National Health Investors because this is a real estate trust that investors often judge on recurring earnings like funds from operations and net income. On the headline numbers, the stock trades on roughly 4.8x earnings, which is far below the Health Care REITs sector average of about 16.7x and also well under the broader peer group at about 57.6x. That is a steep gap for a business still anchored in rental income from senior housing and medical properties.
Because the recent Q3 2026 report included strong net income and funds from operations guidance, such a low P/E suggests the market is still pricing in caution despite those figures. A model that looks at National Health Investors' own earnings profile, balance sheet and sector risk points to a higher multiple as a more typical level. The current 4.8x sits on the undervalued side of that tailored benchmark. For anyone weighing the story around senior housing, the key question is whether the earnings mix after recent disposals and acquisitions truly justifies that discount multiple. Explore the numbers behind National Health Investors's P/E valuation.
The National Health Investors Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for National Health Investors pick up where that P/E puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to play out for the trust to look meaningfully cheaper or more expensive than its current share price on the Community page. Each storyline links its number to a specific view on how National Health Investors' growth profile, profitability and risks could evolve, giving you something concrete to track as fresh results come through.
One of the top narratives on National Health Investors: 14% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main factor that has to go right is successful reinvestment of the $560 million NHC sale proceeds and sizeable liquidity into private pay senior housing and SHOP at returns that offset higher G&A and near term FFO pressure..."
Discover why this Narrative puts National Health Investors at 14% undervalued.
One more National Health Investors question before you move on
Before you decide what to do with National Health Investors based only on current earnings multiples, it helps to see where professional forecasts think this REIT could be a few years down the road. Explore where analysts expect National Health Investors to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com