
Is Knife River (KNF) Trading At A Discount On Starboard Value's Activist Push?
Knife River (KNF) is suddenly in the spotlight after activist fund Starboard Value publicly pressed the construction materials group to lift profitability, explore alternatives, and even weigh a full sale.
The activist push comes after a sharp 30-day share price return of 17.24% for Knife River, even though the year-to-date share price return is down 19.67% and the 1-year total shareholder return has slipped 18.09%. This suggests sentiment is only just starting to turn after a weaker stretch.
Scan how other construction and materials players are trading around similar catalysts by moving from Knife River to our curated list of solid balance sheet and fundamentals (24 results) in a single step.
Knife River now trades at a discount to both analyst targets and one intrinsic value estimate after that sharp rebound. Is the market still too cautious, or is it fairly pricing the profit questions Starboard has flagged?
Most Popular Narrative: 18% Undervalued
Knife River closed at $58.43, while the analyst consensus Narrative on Simply Wall St points to a fair value around $71.33, implying meaningful upside based on those cash flow and earnings assumptions.
Knife River’s aggregates-led vertical integration, with owned reserves feeding ready mix, asphalt and contracting work, continues to increase the share of internally sourced materials on projects. This can support higher net margins and more stable earnings across pricing and volume cycles.
See why 7 investors see Knife River as 18% undervalued.
Result: Fair Value of $71.33 (UNDERVALUED)
Still, the narrative can unravel if Oregon funding delays deepen or if higher diesel costs and lower margin contracting work continue to squeeze Knife River’s profitability.
Find out about the key risks to this Knife River narrative.
Another View: Knife River Looks Expensive On Earnings
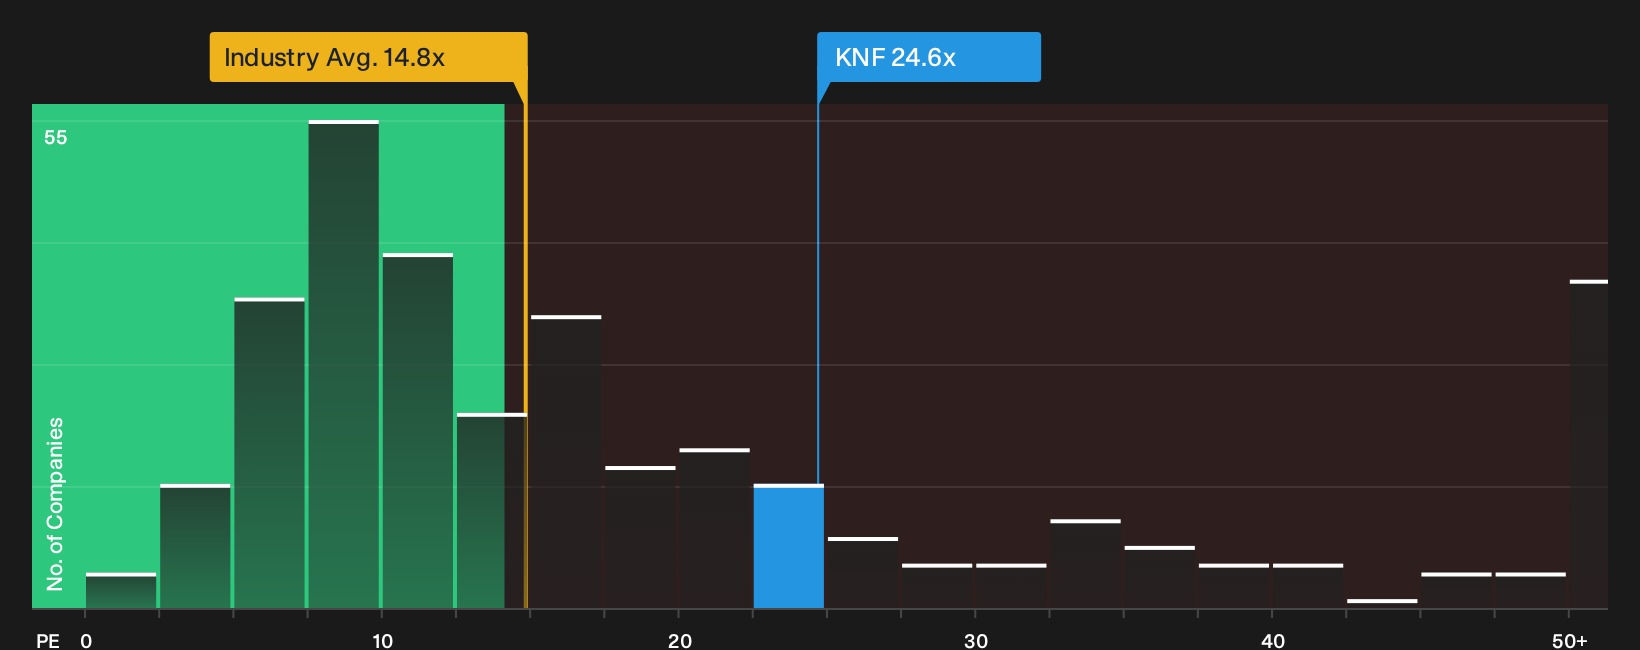
While one narrative treats Knife River as about 18% undervalued on fair value estimates, its current P/E of 24.6x tells a tougher story. That multiple sits above the Global Basic Materials average of 14.7x, the peer average of 19x, and even the 18.2x fair ratio the market could move toward. This points to valuation risk if sentiment cools.
If pricing power or margin recovery stumble, investors need to ask whether paying a richer P/E for Knife River still makes sense compared with both its sector and that lower fair ratio benchmark.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment split on Knife River’s valuation and profitability path, move quickly to test the numbers, weigh both sides, and judge the trade off yourself by reviewing the 2 key rewards and 1 important warning sign
Looking for more Knife River style investment ideas?
Do not stop at Knife River. Use the Simply Wall St Screener to quickly surface fresh candidates so you are not late to the next move.
- Target potential bargains by scanning companies that currently screen as quality yet out of favour through the 35 high quality undervalued stocks.
- Stack your portfolio toward resilience by filtering for businesses with strong finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities by checking the 20 high quality undiscovered gems before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com