
Navigator Holdings (NVGS) Could Be 19% Undervalued After Q3 Earnings And Dividend
Navigator Holdings (NVGS) just paired a strong third quarter earnings report with a fresh dividend declaration, a combination that is now drawing closer attention to the liquefied gas carrier operator’s stock.
Recent trading reflects that mix of strong Q3 results, a fresh dividend and November’s bond repurchase. The share price is up 1.6% over the last day and 2.8% over the past week but down about 13.1% over 30 days. The year to date share price return of 19.9% and 1 year total shareholder return of 20.8% sit alongside multi year total shareholder returns of 53.2% over 3 years and 141.7% over 5 years, suggesting longer term momentum has been positive even as near term sentiment has cooled.
Scan beyond Navigator Holdings and see which other shippers and energy plays are showing similar earnings momentum and capital return policies in our curated list of solid balance sheet and fundamentals (24 results).
After a sharp month long pullback and a fresh US$0.08 dividend, Navigator Holdings now trades well below a price target of US$26.08. Does that gap point to mispricing, or a fair discount on the recent move?
Most Popular Narrative: 19% Undervalued
On the analyst consensus Narrative on Simply Wall St, Navigator Holdings screens as undervalued, with a fair value of about $25.67 against the latest $20.80 close. That view leans heavily on how shipping performance, terminals and capital returns all connect.
The continued structural shift toward cleaner fuels such as LPG and ammonia, together with industrial growth and higher living standards in emerging markets, is still feeding into liquefied gas and petrochemical transport demand. Recent record average TCE of US$33,946 per day with 90.8% utilization suggests Navigator Holdings is already capturing some of this in revenue and earnings.
See why 11 investors see Navigator Holdings as 19% undervalued.
Result: Fair Value of $25.67 (UNDERVALUED)
Still, the narrative on Navigator Holdings can crack if TCE rates and terminal throughput normalize faster than expected, or if vessel operating costs keep climbing and squeeze cash flow.
Find out about the key risks to this Navigator Holdings narrative.
Another View: Our DCF Model Flags Overvaluation
The earlier fair value of $25.67 leans on analyst earnings and multiples. The SWS DCF model tells a very different story, with an estimated future cash flow value of $6.78 per share versus the current $20.80 price. That gap raises a simple question for Navigator Holdings investors: Which set of assumptions feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
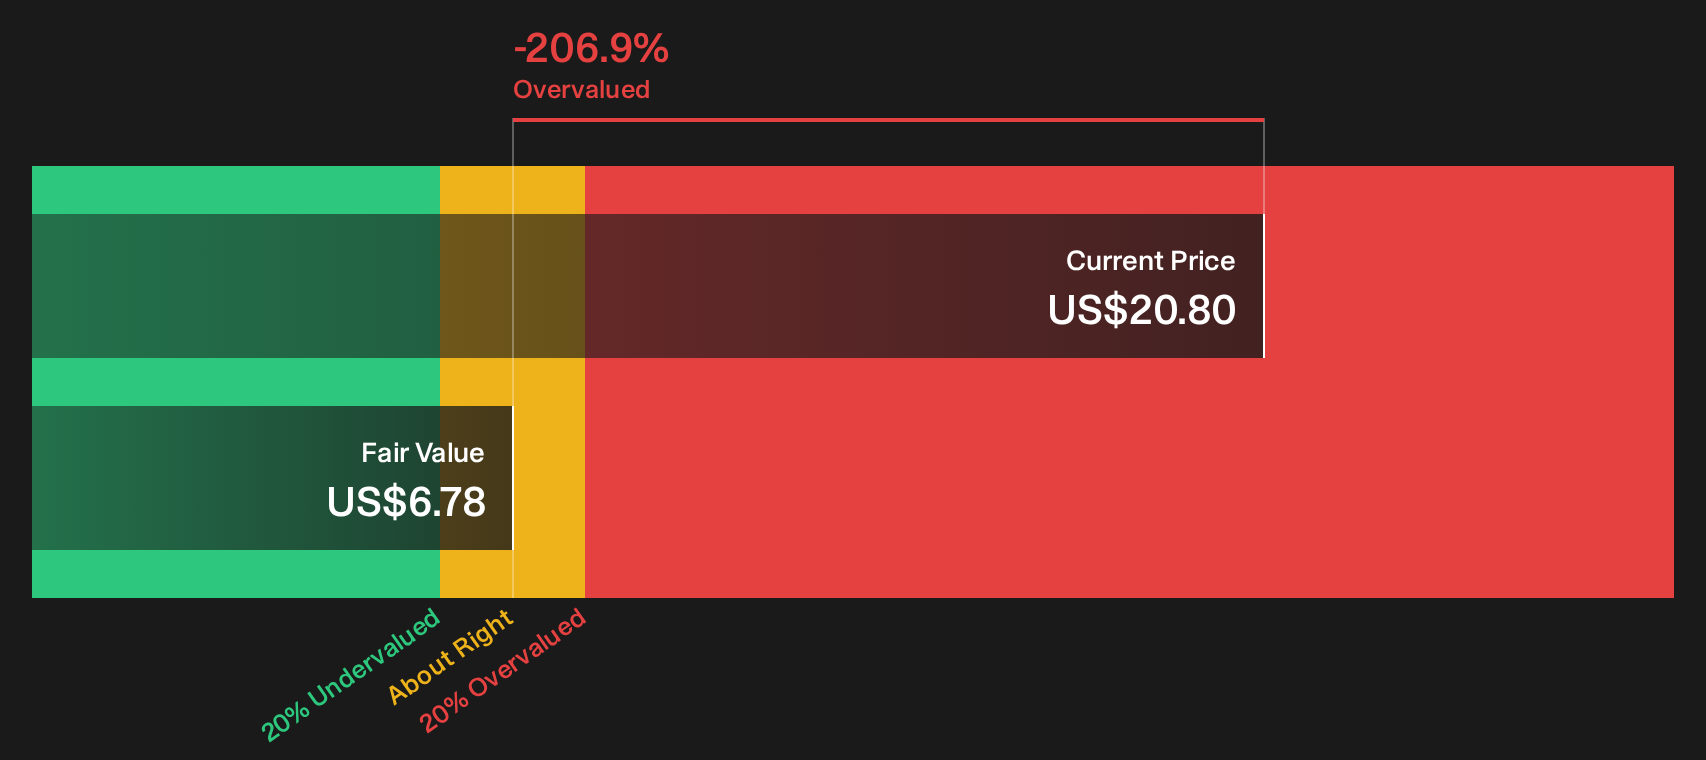
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Navigator Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals so far on Navigator Holdings, so do not sit on the sidelines and rely only on headlines when the data is available. Review the full picture of expectations, concerns and reasons for optimism in our breakdown of 3 key rewards and 4 important warning signs
Looking for more ideas beyond Navigator Holdings?
If Navigator Holdings has sharpened your focus on valuations and balance sheets, do not stop here. Use targeted screeners to uncover other opportunities that match your standards.
- Hunt for quality at a discount by scanning companies filtered for strong fundamentals and sensible pricing with the 35 high quality undervalued stocks.
- Lock in income potential by zeroing in on resilient payers using the 5 dividend fortresses.
- Reduce portfolio stress by focusing on financially robust businesses through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com