
Is USA Compression Partners (USAC) Undervalued Following Its Strong Third Quarter Results?
USA Compression Partners (USAC) just posted a fresh set of third quarter numbers that give investors new data on the business. The headline story is simple. Sales, revenue, net income and earnings per unit all moved higher versus a year earlier.
That earnings beat comes against a backdrop where USA Compression Partners’ share price has risen 7.27% year to date to US$25.52. The 1-year total shareholder return of 19.72% and 5-year total shareholder return of about 1.7x suggest longer term momentum has been stronger than the recent 90-day period, when the share price return slipped 2.07%.
Scan beyond USA Compression Partners and line up other income-oriented plays with resilient balance sheets by using our hand-picked 5 dividend fortresses as a starting point.
USA Compression Partners now appears to be a stronger operation based on recent results, yet the unit price is already higher compared with the past year. So are you paying a fair price for that quality, or a premium?
Most Popular Narrative: 15% Undervalued
USA Compression Partners is trading at $25.52, while the analyst consensus Narrative on Simply Wall St anchors fair value at $30. This implies a discount when that view aggregates revenue, earnings and risk assumptions through an 8.7% discount rate.
Ongoing tightness in large horsepower compression, reflected in engine lead times that have extended to about 200 weeks and customers contracting capacity several years ahead, gives USA Compression Partners multi year visibility on deployments and underpins revenue and cash flow.
See why 6 investors see USA Compression Partners as 15% undervalued.
Result: Fair Value of $30 (UNDERVALUED)
Still, the USA Compression Partners story can change quickly if higher interest costs pressure its leverage profile, or if rising lube oil and manufacturing expenses squeeze profitability more than expected.
Find out about the key risks to this USA Compression Partners narrative.
Another View: USA Compression Partners Through The P/E Lens
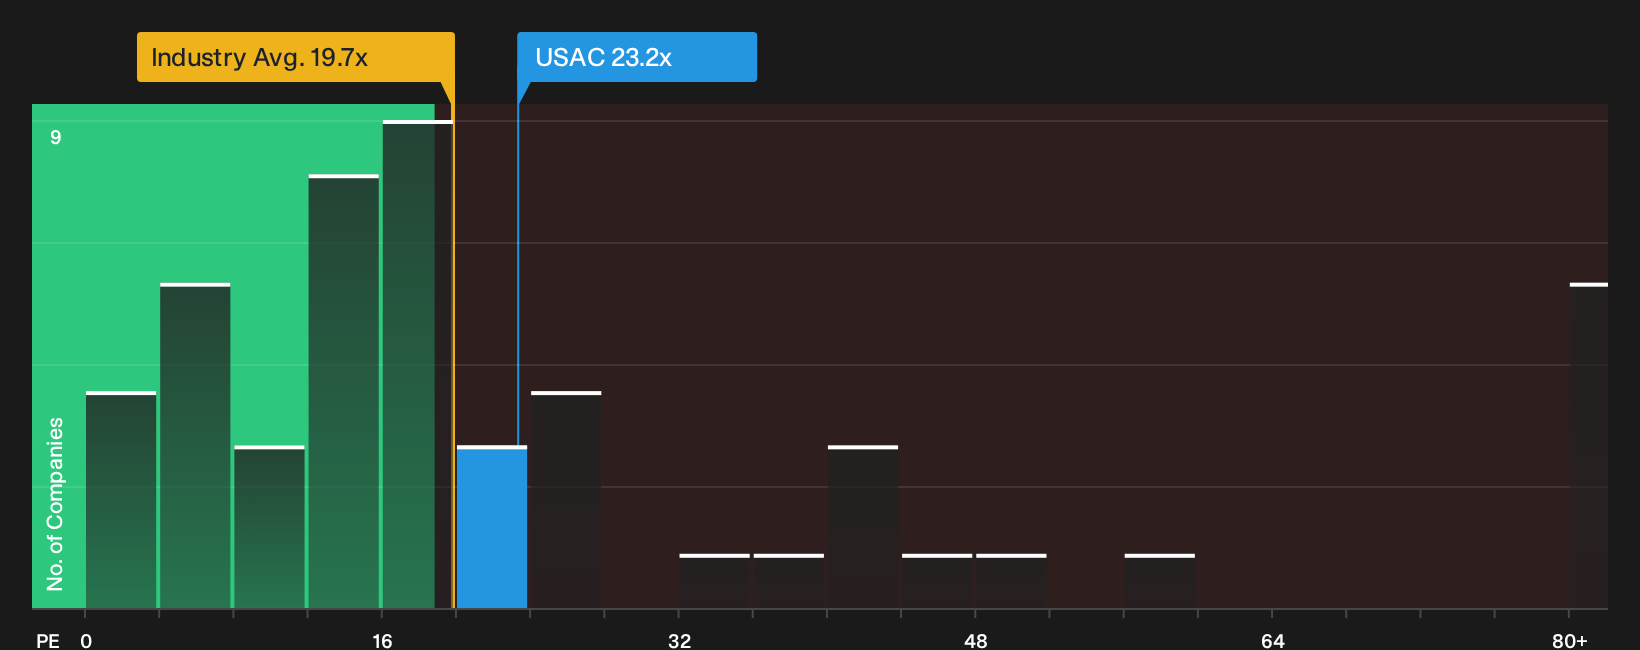
The first fair value story for USA Compression Partners leaned on analyst forecasts and discounted cash flows. A simple P/E check paints a tougher picture. The units trade on 23.2x earnings, compared with a fair ratio of 19.1x, the US Energy Services industry at 20.8x, and peers at 22.8x. That premium can signal confidence in the cash flow story, or it can just mean less room for error if anything goes wrong.
Before leaning too hard on that richer P/E, it helps to see how the full valuation breakdown treats this gap between price and earnings power, and what it implies for both upside and downside risk in USAC units. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the USA Compression Partners story so far. Act while the details are fresh and weigh both sides of the ledger for yourself with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond USA Compression Partners?
Do not stop with USA Compression Partners. Use this earnings update as a springboard and line up a few fresh watchlist candidates with stronger balance sheets or different risk profiles.
- Target reliable compounding by scanning companies that combine quality fundamentals with attractive pricing through the 35 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses with resilient payouts and higher yields using the 5 dividend fortresses.
- Reduce portfolio stress by focusing on companies with robust financial footing through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com