
How Investors May Respond To Teledyne Technologies (TDY) NGI Support Contract
- Teledyne Technologies, through its subsidiary Teledyne Brown Engineering, recently secured a subcontract from Lockheed Martin to supply mechanical ground support equipment, including transportation systems with structural weldments, rotation mechanisms, and hydraulic systems, for the Next Generation Interceptor missile defense mission.
- This NGI subcontract deepens Teledyne Technologies' role in complex U.S. defense programs and reinforces its position as a trusted supplier of specialized manufacturing and engineering capabilities for government related work.
- We will now explore how Teledyne Technologies' new NGI ground support work could influence the broader investment narrative around defense exposure.
Compare Teledyne Technologies' NGI win with other defense exposed engineering players by scanning our hand picked 41 power grid technology and infrastructure stocks, which sit at the crossroads of infrastructure and security.
Teledyne Technologies Investment Narrative Recap
To own Teledyne Technologies, you need to be comfortable with a diversified industrial and defense supplier that leans heavily on government contracts and a large funded backlog. The analyst consensus Narrative on Simply Wall St focuses on execution in high reliability sensing, imaging, and defense programs as the core driver, with roughly one quarter of revenue tied to the U.S. government. The NGI work supports that theme but does not radically change it.
The more immediate swing factor is whether Teledyne Technologies can keep translating its funded backlog into shipments without supply chain or input cost issues eating into margins. The biggest risk is that expanding defense work and the planned Varex Imaging acquisition dilute profitability instead of lifting it, if pricing and cost control do not keep pace.
The upcoming appearance at the Baird 2026 Global Industrial Conference looks closest to this NGI story because it gives management a platform to update how defense, industrial, and healthcare pieces fit together. Investors can listen for how Teledyne Technologies frames defense exposure, including NGI style programs, within its broader mix of Digital Imaging, Instrumentation, and Engineered Systems.
Conference commentary may also clarify how management thinks about margin quality, given earnings grew 25.5% over the past year and net profit margins are now 15.8%. Any detail on supply chain resilience, pricing discipline, and capital deployment could help you reassess both the upside case built on multiyear defense and healthcare demand and the risk that slower forecast growth and a relatively full P/E limit room for error.
Teledyne Technologies' narrative projects US$7.4b in revenue and US$1.2b in earnings by 2029. This assumes 5.2% yearly revenue growth and an earnings increase of about US$225.2 million from current earnings of US$974.8 million.
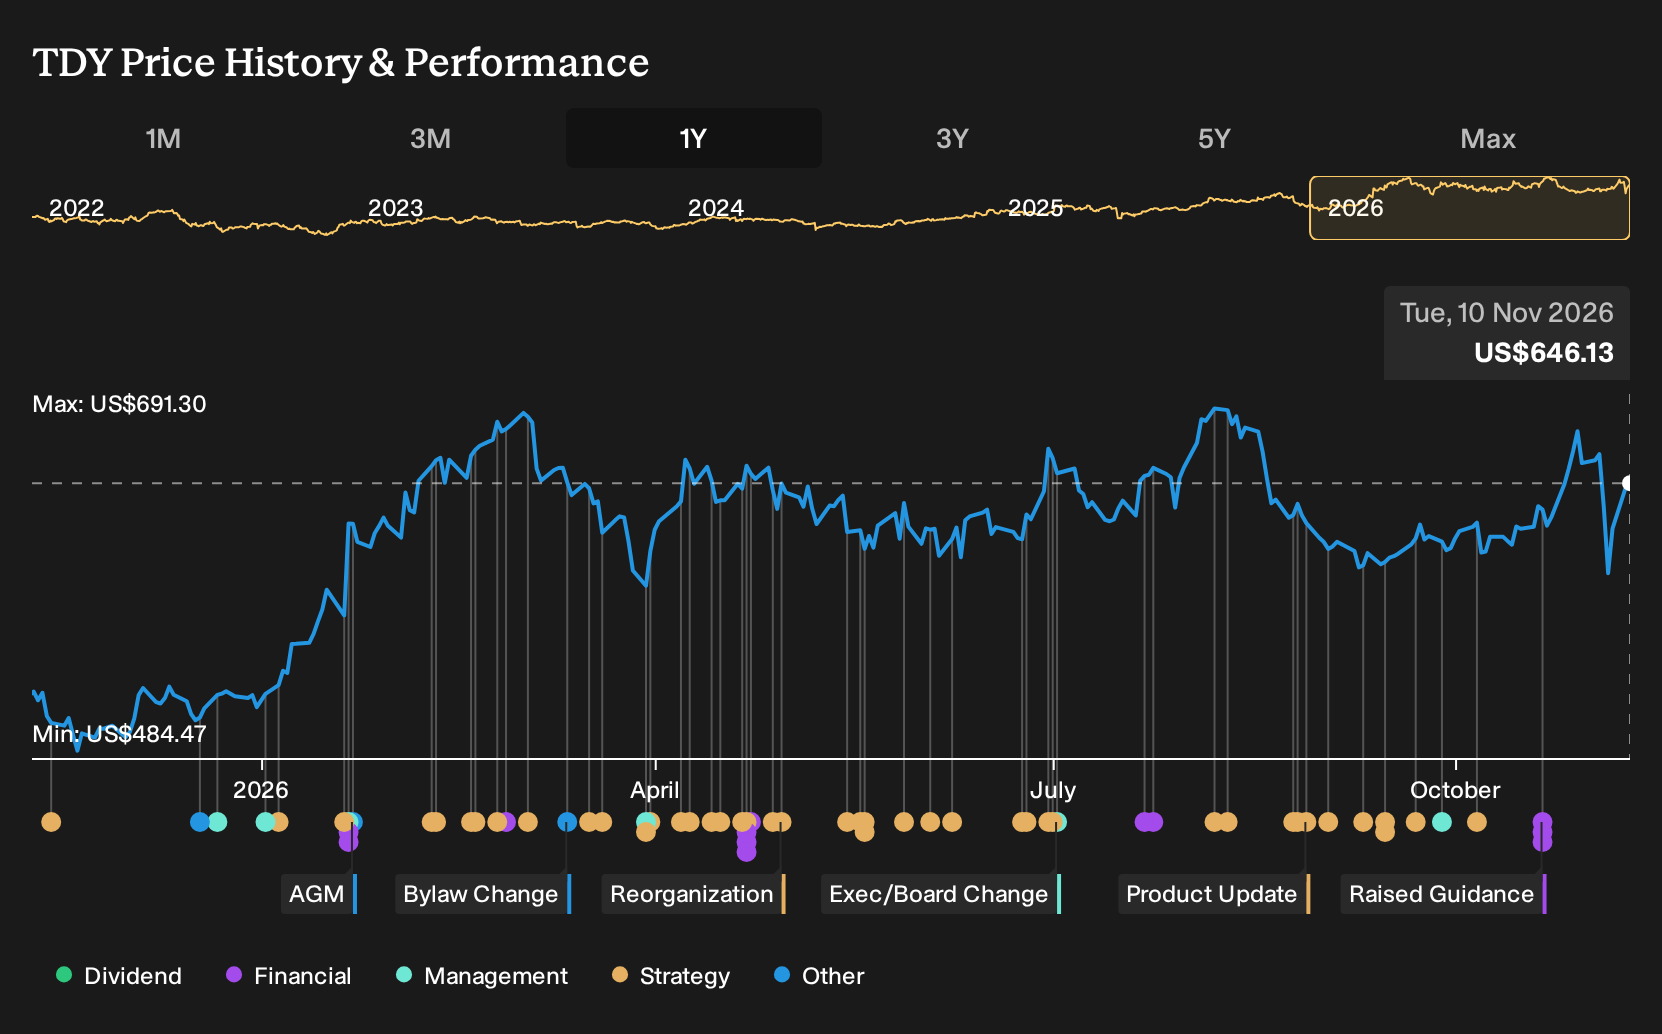
Discover why Teledyne Technologies' fair value points to a 17% potential upside compared with its current price, and why this gap could close quickly.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value views for Teledyne Technologies so far, ranging from about US$615 to US$758 per share. Those pre-NGI and conference estimates sit beside real execution questions around margin mix, supply chain costs, and defense exposure, so you may want to compare several sharply different viewpoints before deciding how this story fits your portfolio.
Explore another Teledyne Technologies fair value estimate, including one that suggests it could be worth just $614.82.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your Teledyne Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teledyne Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teledyne Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Teledyne Technologies?
If the Teledyne Technologies story has sharpened your thinking on risk, cash flow quality, and contract driven revenue, it can help to cross check those instincts on a broader watchlist. The Simply Wall St Screener lets you quickly filter for different profiles so you can line Teledyne Technologies up against peers with very different balance sheets, growth paths, and payout habits.
- If capital preservation sits high on your list, scan a basket of 30 resilient stocks with low risk scores that score well on resilience and risk controls.
- For investors hunting for quality at a sensible entry point, compare Teledyne Technologies with a curated 35 high quality undervalued stocks that pairs balance sheet strength with cash flow support.
- If you prefer to focus on businesses that can potentially fund themselves and still return cash to shareholders, filter by payout profile using a tailored 5 dividend fortresses that emphasises higher yield opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com