
SPS Commerce (SPSC) Issued Fresh Guidance, Is The Upside Already Priced In?
SPS Commerce earnings and guidance in focus
SPS Commerce (SPSC) just released third quarter results and fresh forecasts that give investors an updated picture of how this supply chain software provider is performing through 2026.
SPS Commerce shares have come under pressure in recent months, with the stock down 5.1% on a 7 day share price return and 4.3% on a 30 day share price return, while the 3 year total shareholder return has declined 56.6%. Recent quarterly results and fresh guidance now give investors more concrete data to judge whether that longer term weakness reflects a reset in expectations or an opportunity if growth and profitability trends hold up against the current valuation.
Scan beyond SPS Commerce and size up other hand picked software players with solid fundamentals and recurring revenue profiles using our 20 high quality undiscovered gems.
SPS Commerce shares have already undergone a prolonged decline followed by a modest recent rebound. The key question now is how much potential valuation upside remains ahead, rather than how much is already in the rear view mirror.
Most Popular Narrative: 4.6% Undervalued
On the analyst consensus Narrative on Simply Wall St, SPS Commerce carries a fair value estimate of $84.82 compared with a last close of $80.92, which points to a modest discount while still assuming disciplined execution on margins and cash flows.
The main factor that has to go right is that SPS Commerce successfully shifts growth toward higher value ARPU expansion on its existing network while integrating AI agents and the refocused 1P revenue recovery portfolio, without eroding customer retention.
Management’s framework that roughly two thirds of growth will come from ARPU and one third from customer count puts more pressure on SPS Commerce to keep deepening wallet share on a relatively mature network in order to drive revenue and EBITDA growth.
See why 4 investors see SPS Commerce as 5% undervalued.
The valuation work in that Narrative uses an 8.41% discount rate and a scenario in which SPS Commerce reaches $927.0 million of revenue and $172.5 million of earnings by 2029, then trades on an 18.4x P/E multiple at that point. Analysts treating the stock as roughly fairly priced at around $85 are effectively saying the current $80.92 level already reflects mid single digit top line expansion and a profit margin path toward 18.6%, with limited room for disappointment on either front.
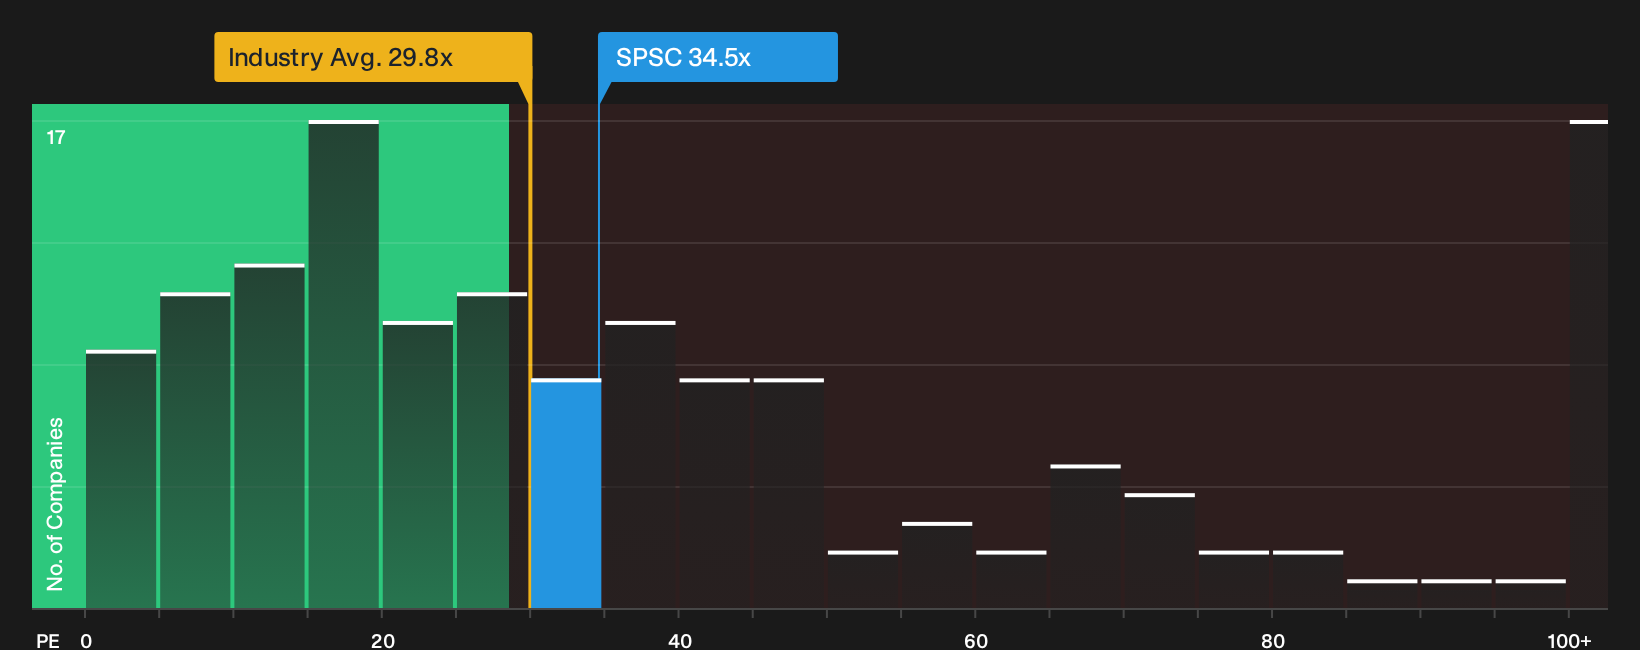
For you as a shareholder or watcher, the tension is clear. On one side, the SWS DCF style cash flow work embedded in the Narrative supports a fair value above where SPS Commerce trades today, and Statements data flag the shares as trading 47.5% below an internal future cash flow value estimate of $154.26. On the other side, simple market ratios still screen as demanding, with a 34.5x P/E above both the 30x fair P/E estimate and the 30.3x US Software average, which indicates the market is already assigning SPS Commerce a premium for its subscription model and earnings quality, as well as the expected 25.9% yearly profit growth.
Result: Fair Value of $84.82 (UNDERVALUED)
Still, two pressure points could upset that SPS Commerce story: prolonged spending cuts from suppliers and any stall in retail enablement programs feeding new projects.
Find out about the key risks to this SPS Commerce narrative.
Another view on SPS Commerce valuation
Market ratios tell a different story. SPS Commerce trades on a 34.5x P/E, while the fair ratio is 30x and the wider US Software group sits at 30.3x. That premium suggests investors are already paying up, so it is worth asking how much room is really left if expectations slip at all.
To see how that premium compares with the earnings profile and where the ratio could drift toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all feels finely balanced between risk and reward, that is the point. Move quickly through the data and pressure test your own thesis using the 2 key rewards.
Looking for more SPS Commerce investment ideas?
Do not stop at SPS Commerce. The strongest portfolios rarely rely on a single story, and broadening your watchlist now can matter more than timing any one entry.
- Target potential mispricings by scanning for resilient businesses trading below internal estimates of worth using the 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that pair higher yields with staying power through the 5 dividend fortresses.
- Protect the downside first by filtering for lower risk profiles and sturdier financials with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com