
Elite Australian Undervalued Stocks To Own In November 2026
Hotter than expected US inflation has pushed bond markets around and lifted global interest rate expectations, which keeps pressure on richly priced Australian shares. That kind of backdrop can reward patient buyers who focus on profitable, conservatively financed businesses that still trade at a discount. This article walks through three high quality Australian stocks our value screen flags as potentially mispriced and explains what makes each one worth a closer look.
The three stocks below are just a sample from our value shortlist, and the full screen surfaced one more business with an equally interesting story that is not covered here.
If you want to identify and analyze potential high quality undervalued opportunities in minutes, head straight to the High Quality Undervalued Stocks screener
Civmec (ASX:CVL)
Civmec is a diversified Australian contractor that fabricates steel structures and builds naval vessels, while also running a sizeable concrete fabrication and civil works arm that ties neatly into the High Quality Undervalued Stocks theme. In FY 2026 it booked about A$587 million from Resources, A$210 million from Infrastructure, Marine and Defence, A$106 million from Energy, and it is valued at roughly A$861 million.
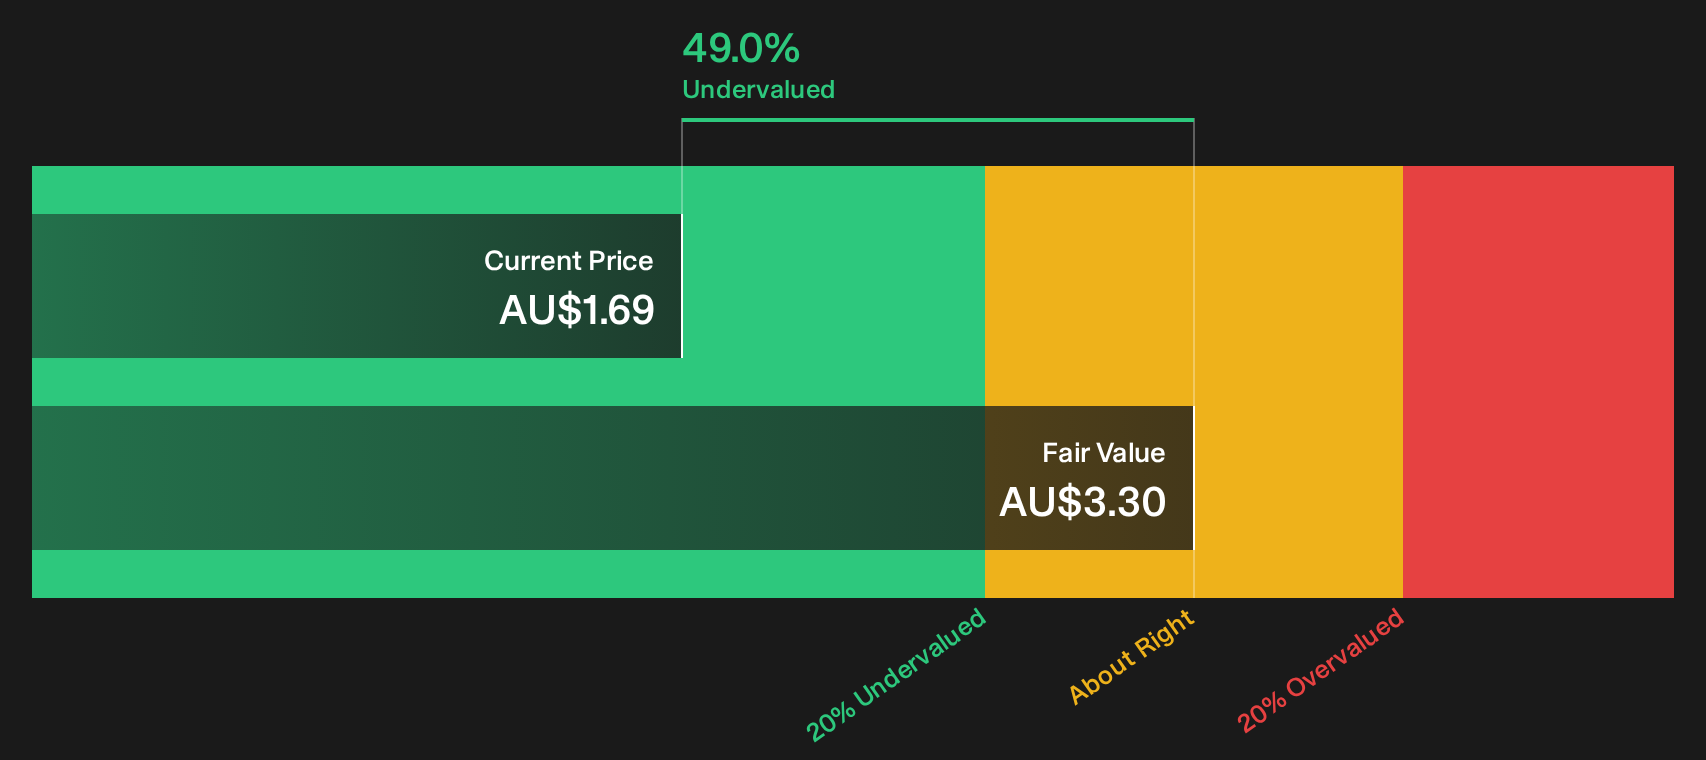
Civmec links into this screen through its reinforced concrete, modular and civil construction work. The share price still trades well below estimated future cash flow value on a P/E of about 16.5x, with profit margins near 5.8%. The A$1.5 billion order book and improving earnings profile could matter a lot depending on how one unseen pressure shapes future project economics.
To see how that pressure and the order book are already baked into expectations, pull up the 4 key rewards and 1 important warning sign and judge whether Civmec’s pricing gap is justified.
NRW Holdings (ASX:NWH)
NRW Holdings is another screen pick where the heavy lifting for the High Quality Undervalued Stocks theme comes from its civil and mining contracts. These contracts generate cash flows backed by agreements that can matter a lot when markets start rewarding visibility and balance sheet strength again, according to the bearish analyst Narrative on Simply Wall St.
NRW Holdings runs a broad contracting platform across resources and infrastructure, with about A$1.5b from Mining, A$1.3b from MET, A$862 million from Civil and A$684 million from EMIT, and the business is valued at roughly A$3.0b.
"Although NRW Holdings reports A$7.5 billion of work in hand and a large tender pipeline across mining, civil, MET and Fredon, the confirmation that the A$90 million OneSteel receivable will not be recovered highlights counterparty risk that could still surface on future projects and lead to further write offs that weigh on earnings and net margins."
What happens if a single weak link in that long chain of counterparties starts to shift the balance between strong cash generation and thinner margins?
If that balance is starting to shift, the full narrative for NRW Holdings explains how NRW Holdings could still convert counterparty risks into the potential for accelerating cash generation.

Life360 (ASX:360)
Life360 looks tightly aligned with the High Quality Undervalued Stocks theme because its freemium family safety app turns paying subscribers into recurring cash flows, with the business generating about $622 million from Software & Programming and carrying an equity value of roughly A$4.6 billion.
"The shift to an AI-native operating model, including proprietary engines that tailor paywall messages and are linked to higher free-to-paid conversion and ARPPC gains of 5 to 7% year on year across recent quarters, provides a structural catalyst for Life360 to increase monetization of its more than 100 million MAU and to improve operating leverage."
The real swing factor is how one cost heavy growth initiative ultimately feeds through to future margins once the subscriber flywheel settles.
Once that spend finally settles into a steady state, the full narrative for Life360 shows how Life360’s subscriber engine could decouple revenue growth from future cost intensity.

Seeking Fresh Alternatives Beyond These Three?
Fresh opportunities can move from under the radar to flying on momentum quickly, so scan the next wave of potential breakouts before the crowd catches up and act now.
- Track cash rich balance sheets before they get fully priced by institutions by scanning the curated list of solid balance sheet and fundamentals (12 results) that currently screens for financial strength.
- Spot early stage miners before metal prices reset expectations by reviewing the hand picked producers inside the 33 elite gold producer stocks that focuses on quality output.
- Ride the build out of future power demand by checking companies in the curated 41 power grid technology and infrastructure stocks that screens grid technology and infrastructure specialists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com