
What INFICON Buyers Were Betting On
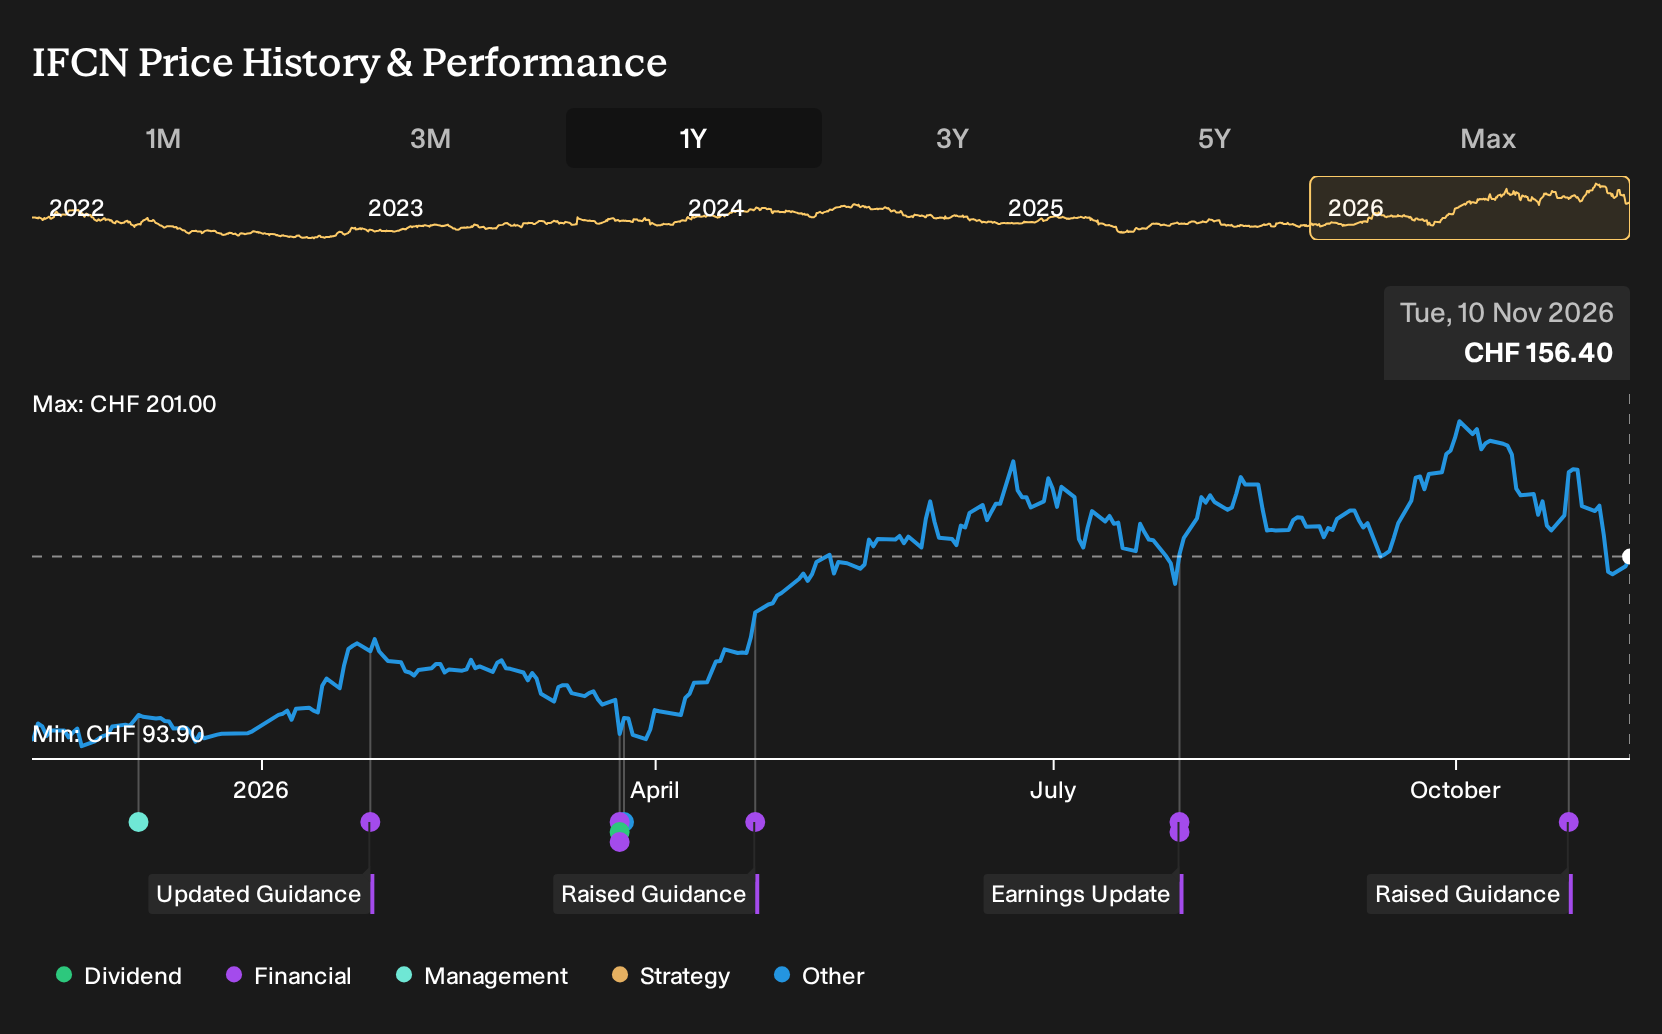
Investors who held INFICON over the past year are up 56.7%, including dividends. If you had bought on 10 November 2025, you were choosing between upbeat October research that framed expanded R&D and global manufacturing moves as a path to transformation and an August warning that US and Chinese friction could cap semiconductor margins. Knowing what you know now, which of those recorded arguments would you have trusted more on that day?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond INFICON. See which of 53 AI infrastructure stocks may still merit a closer look.
The Argument You Would Have Been Weighing On INFICON
The shares cost CHF96.3 at the start of the period, and INFICON sat between two sharply different but reasonable stories about where the business might head next.
On the bullish side, the October 2025 Narrative put Fair Value at CHF110, built on assumptions of 8.5% annual revenue growth and profit margins reaching 16.6% within about three years.
The August 2025 bearish case pointed to a Fair Value of CHF76.98, stressing geopolitical pressure on semiconductor orders and assuming a lower 5.0% annual revenue growth rate.
What The Results Put To The Test For INFICON
INFICON’s 2026 updates told a clear story. Management lifted full year sales guidance twice and pointed to operating income margins of 18% to 22%, with Q3 2026 at 25.5%. H1 2026 revenue and net income were both higher than H1 2025, and net margin moved from 13.3% to 14.6%. The data leaned toward the October growth case.
The hinge assumption was margin strength. When you judge another stock, compare any forecast margin path with later reported margins and guidance, not just top line targets.
What INFICON’s One Year Run Already Prices In
INFICON now trades at CHF156, after a 56.7% gain over the past year from CHF96.3. The analyst consensus Narrative on Simply Wall St sees Fair Value above that level, based on how current orders and margins might flow through the business.
The core debate is whether INFICON can keep scaling capacity without giving up its margin profile or supply resilience. A buyer today is really judging whether those higher margins can persist as production and regional manufacturing keep expanding.
"The main thing that has to go right is that INFICON Holding maintains its higher margin structure and supply chain resilience while scaling capacity, so that production reconfiguration benefits and Asian footprint shifts are not eroded by ongoing cost inflation and component bottlenecks."
One Narrative disagrees with today's price. → See where this Narrative says INFICON should trade
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 16% below our estimate - target chronic and specialty drug demand as infrastructure spending increases.
- Company 2 - 37% below our estimate - extend an IT reselling model into AI-focused, higher touch service projects.
- Company 3 - 38% below our estimate - ramp next generation NAND capacity toward higher margin enterprise SSD demand.
Three companies from the same screener. Open the full list of 202 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com