
Dell Technologies (DELL) Could Be 44% Below Fair Value After Texas Data Center Freeze
Texas data center moratorium becomes a key risk for Dell Technologies stock
The recent pullback in Dell Technologies (DELL) has been closely tied to the new Texas governor’s pledge to halt fresh data center approvals, a policy that investors read as a direct threat to AI focused infrastructure demand.
That Texas headline has hit a stock that was already cooling, with Dell Technologies’ share price down 3.44% on the day, 18.12% over the past week and 42.94% over the last month. Year to date the share price return is 161.64% and the 5 year total shareholder return is 550.09%, so long term holders are still sitting on very large gains while near term momentum is clearly fading as investors reassess AI infrastructure risk around the upcoming earnings update.
Spot fresh AI infrastructure opportunities beyond Dell Technologies by scanning a curated list of 53 AI infrastructure stocks.The question now is whether Dell Technologies is repricing because the business outlook has changed, or because sentiment around AI infrastructure just swung hard, and what that implies for current valuation.
Most Popular Narrative: 44% Undervalued
On Simply Wall St, the analyst consensus Narrative pegs Dell Technologies’ fair value at $594.16 compared with a last close of $334.38, which implies a wide discount based on analysts’ combined earnings, revenue and discount rate assumptions.
Dell Technologies is experiencing accelerating demand for AI servers and data center solutions as enterprises globally increase investments in AI and machine learning workloads and digital transformation, supported by more than US$130b of AI server orders in the past 12 months, a US$95b AI backlog and a pipeline that is multiples of backlog, which ties directly to future revenue and earnings.
See why 246 investors see Dell Technologies as 44% undervalued.
Result: Fair Value of $594.16 (UNDERVALUED)
Still, the narrative around Dell Technologies can crack if AI server margins remain stuck at mid single digits, or if tight component supply drags out that US$95b backlog.
Find out about the key risks to this Dell Technologies narrative.
Another View: What Dell Technologies’ P/E Is Telling You
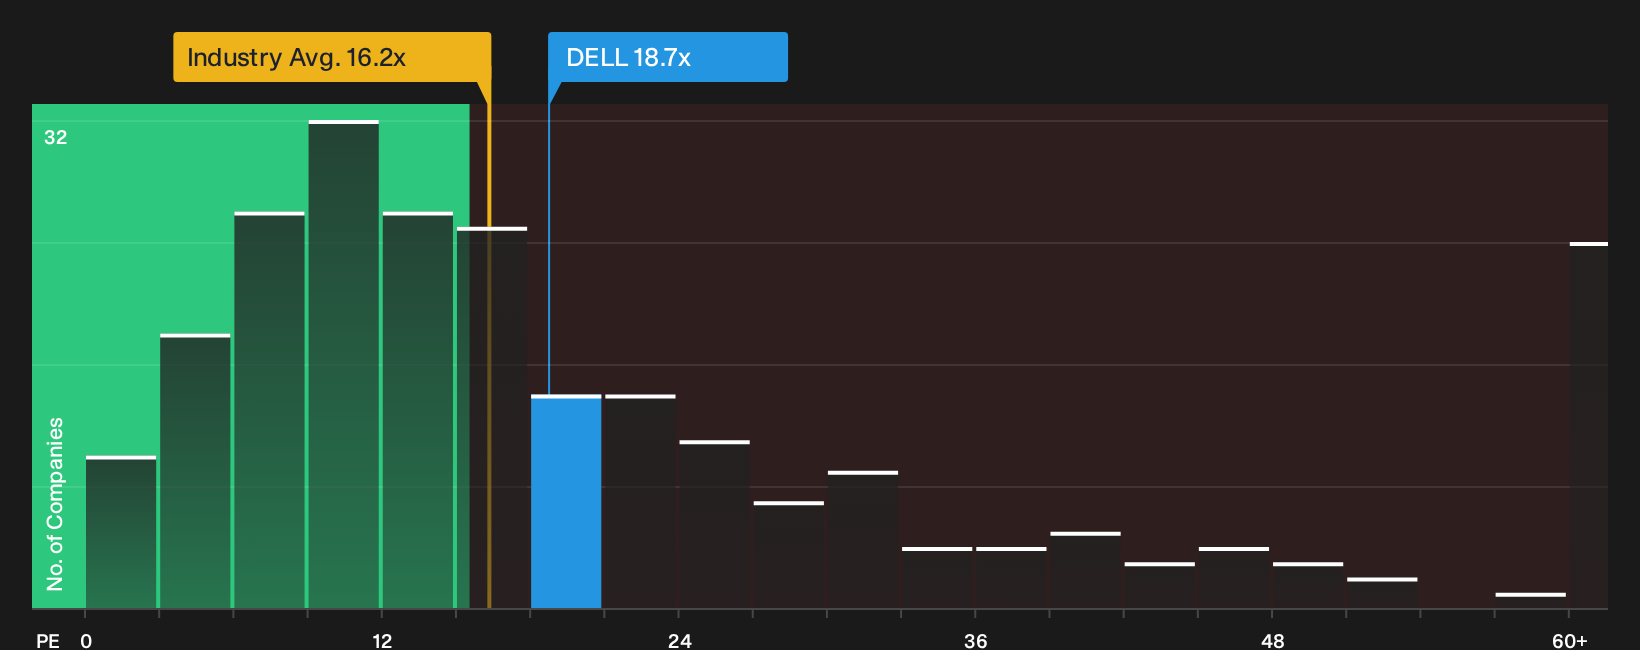
Analyst models and fair value estimates point to Dell Technologies trading below projected cash flow value. The simple P/E lens tells a different story. At 18.7x earnings, the stock is priced above both its peer group at 16.8x and the global tech sector at 16.2x.
That same P/E is well under a fair ratio of 36.1x, which is where regression analysis suggests the multiple could trend over time. For shareholders, that gap cuts both ways. It hints at upside if sentiment moves toward the fair ratio, and it also means any disappointment on AI or Texas related headlines could compress valuation faster than models imply.
To pressure test this multiples view against the cash flow based work, walk through the valuation breakdown in our detailed model, then compare it to your own expectations for Dell Technologies’ AI and data center earnings mix. See what the numbers say about this price — find out in our valuation breakdown.
For a quick visual on how today’s pricing stacks up, review the latest comparison of Dell Technologies’ earnings multiple versus the broader sector.
Next Steps
If this mix of AI optimism and policy risk leaves you on the fence, move quickly to inspect the underlying data and form your own judgment. To balance the concerns against the potential upsides, walk through the full breakdown of 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Dell Technologies?
Do not stop your research at Dell Technologies. Broaden your watchlist with a few targeted stock ideas that match different goals and risk levels.
- Target potential mispricing by scanning a focused set of companies that combine solid fundamentals with appealing valuations through 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that aim to deliver reliable, higher yielding payouts via the 5 dividend fortresses.
- Dial down portfolio risk by filtering for sturdier balance sheets and cleaner financial profiles using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com