
Viasat (VSAT) Wins NASA NEXUS Role, Is The Valuation Upside Still There?
Viasat (VSAT) just picked up a new contract from NASA, securing a phase 1 role in the agency's NEXUS program to develop commercial Ka-band space relay services.
Viasat’s new NASA work lands at a time when the share price has almost doubled year to date, with a 98.94% share price return and a 96.43% total shareholder return over 12 months, even though the 90 day share price return declined 14.18% and recent earnings still showed losses.
Spot opportunities in satellite and space communications beyond Viasat by scanning our hand picked 53 AI infrastructure stocks.Viasat shares have surged while losses have widened and the NASA contract remains in phase 1. Does that mix of momentum, guidance and ongoing red ink still offer a favourable entry on valuation grounds?
Most Popular Narrative: 28% Undervalued
Viasat last closed at $74.86, while the analyst consensus Narrative on Simply Wall St anchors fair value at $103.94 using a 10.52% discount rate and a detailed revenue and earnings path. That framework ties the recent share price surge to a longer term cash flow and balance sheet story rather than short term contract headlines.
The main thing that has to go right is that Viasat converts its expanded multi-orbit capacity, MSS spectrum position, and Equatys partnership into durable cash generation while managing competitive and regulatory pressures in aviation, maritime, and fixed broadband.
The current valuation implies the market is not fully pricing in the potential value of Viasat’s MSS spectrum, direct-to-device opportunities, and ongoing free cash flow and deleveraging progress.
See why 30 investors see Viasat as 28% undervalued.
Result: Fair Value of $103.94 (UNDERVALUED)
Still, the Viasat story can break if heavy capex keeps leverage and interest costs high, or if regulatory hurdles limit how fully ViaSat-3 capacity is used.
Find out about the key risks to this Viasat narrative.
Another View: SWS DCF Flags Overvaluation
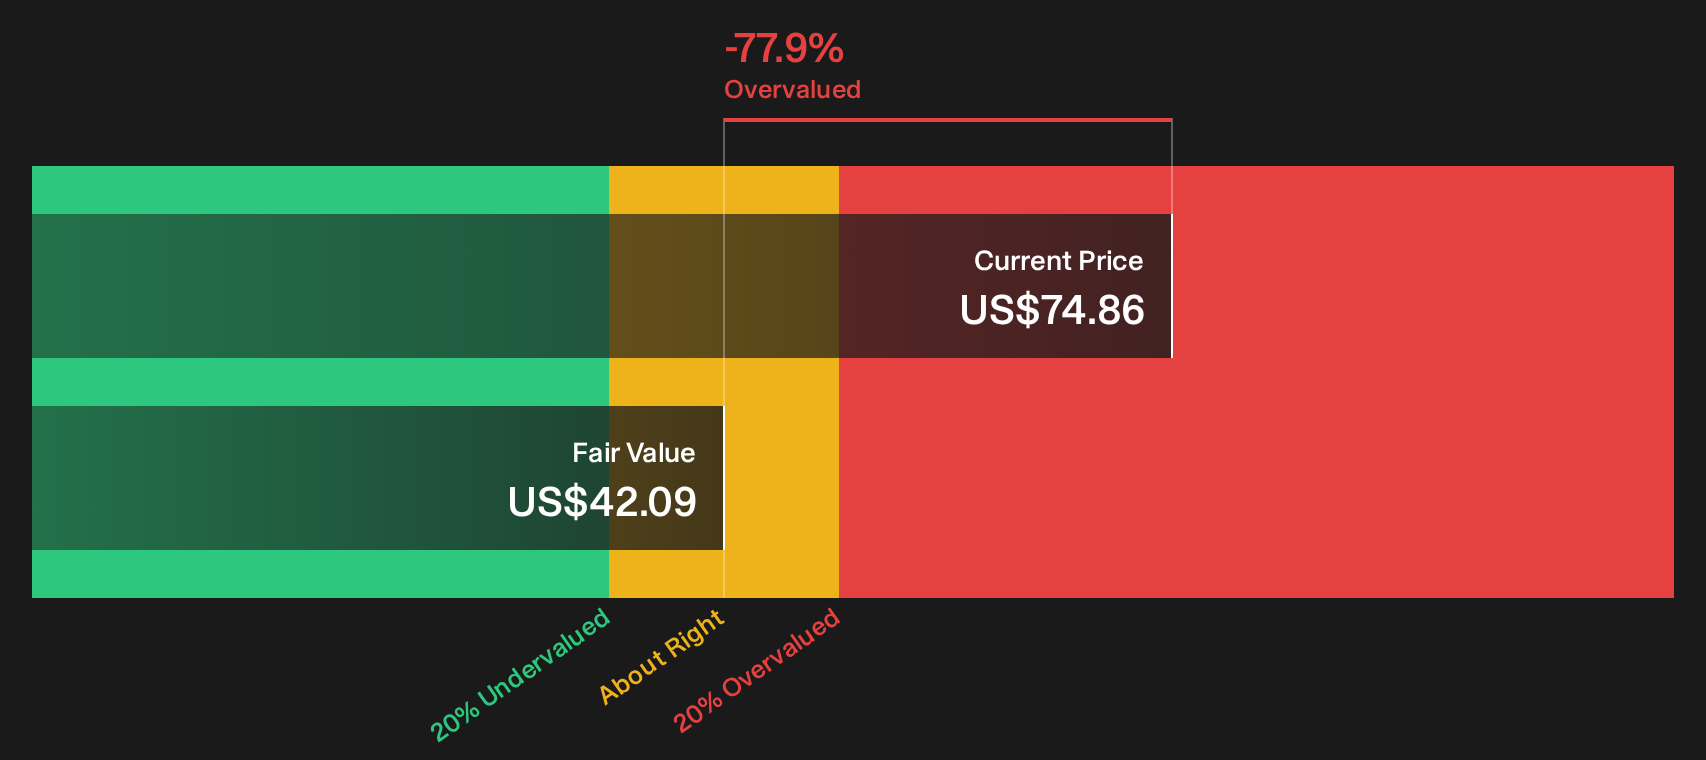
The analyst consensus on Simply Wall St points to Viasat trading about 28% below a fair value estimate of $103.94, yet the SWS DCF model tells a different story. On that cash flow view, VSAT at $74.86 sits above an estimated value of $42.09. This frames today’s price as expensive rather than cheap. Which lens do you trust more when cash generation and contract timing can swing so sharply?
To understand how those long term cash flow assumptions translate into that $42.09 figure, and where the biggest sensitivities lie, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Viasat for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Whether you are excited by the bullish narrative or cautious about the conflicting valuation signals, consider acting while the data is fresh and test the numbers yourself by reviewing the 3 important warning signs.
Looking for more ideas beyond Viasat?
If you stop with Viasat, you risk missing other opportunities that match your goals. Put the rest of the market to work for you too.
- Target potential mispricing by scanning a focused set of quality candidates through the 35 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by filtering for businesses with stronger financial foundations using the list of solid balance sheet and fundamentals (24 results).
- Hunt for under-followed potential by checking the 20 high quality undiscovered gems before the crowd turns its attention there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com