
What Camden Property Trust Stock's Lowered Earnings Outlook Means For Shareholders
- Camden Property Trust reported third quarter 2026 sales of US$381.06 million and net income of US$900.39 million, with basic EPS from continuing operations of US$8.79. The company also released nine month figures that showed sales of US$1.16 billion and net income of US$961.63 million.
- The REIT paired these results with a lower full year EPS outlook of US$9.42 to US$9.46 and a flat same property revenue growth range of -0.25% to 0.25%, highlighting pressure on underlying apartment operations despite very strong reported profits.
- This article examines how Camden Property Trust's trimmed full year EPS guidance reshapes the investment narrative built around its Sunbelt strategy.
Scan how Camden Property Trust's guidance cut compares with other income-focused real estate plays by reviewing a curated set of 5 dividend fortresses.
Camden Property Trust Investment Narrative Recap
To stay invested in Camden Property Trust, you need to be comfortable with a Sunbelt focused apartment owner that is currently reporting very high earnings per share while its underlying same property revenue is flat. The trimmed full year EPS outlook and softer revenue guidance point to a near term story driven more by one off gains than by broad based rent momentum.
The key near term catalyst is whether supply pressure in Camden Property Trust's markets eases enough to stabilize same store revenue and NOI, as described in the analyst consensus Narrative on Simply Wall St. The biggest current risk is that Sunbelt leasing stays sluggish while new units keep coming online, which would prolong weak same property growth and reinforce concerns about earnings volatility.
The most relevant update here is the lowered full year EPS guidance to US$9.42 to US$9.46, with flat same property revenue growth of between a 0.25% decline and a 0.25% gain. That sits uncomfortably alongside very strong reported EPS and underlines how much of the recent profit profile has been shaped by large one off items rather than day to day rent performance.
For you as a shareholder, this guidance reset goes straight to the core catalysts flagged in the analyst consensus Narrative on Simply Wall St. These catalysts lean on supply peaking in Camden Property Trust's markets and capital recycling into younger Sunbelt assets. Execution risk rises if same property revenues do not lift from this near zero range, since that would make it harder to convert operational levers and data tools into steadier NOI and earnings over time.
Camden Property Trust's current narrative points to revenue of US$1.7b and earnings of US$114.1 million by 2029, based on analyst assumptions of 1.7% yearly revenue growth and an earnings decline of about US$985.9 million from roughly US$1.1b today.
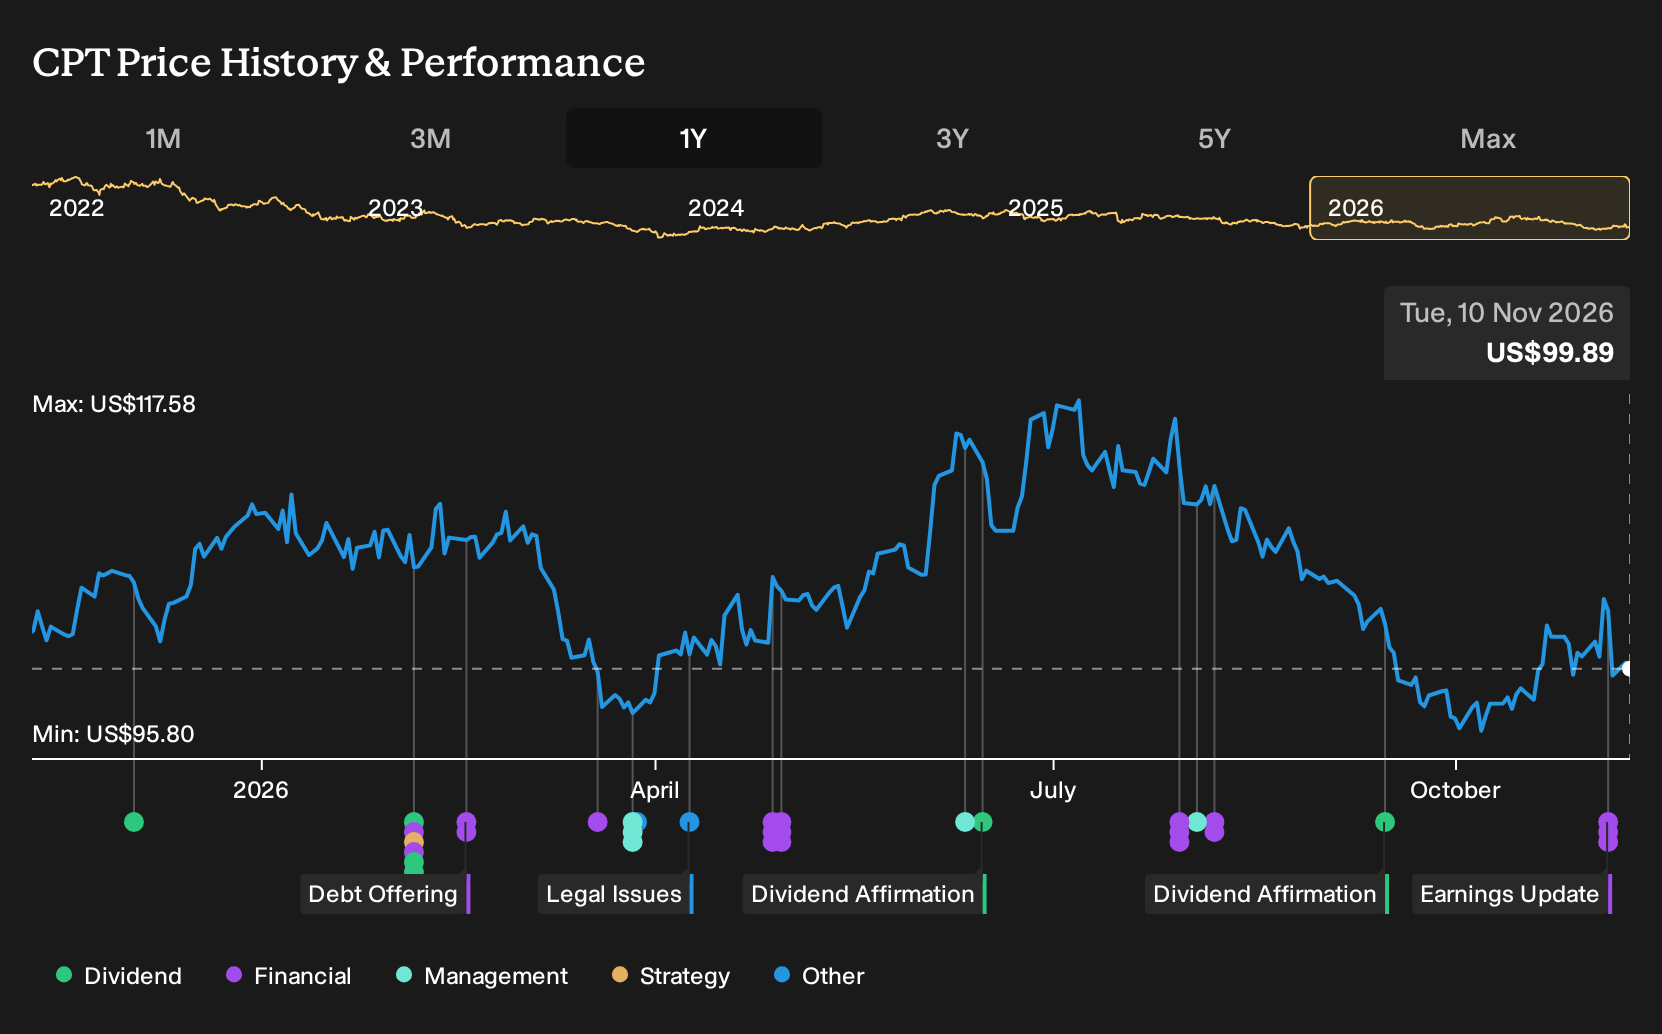
Uncover how Camden Property Trust's fair value indicates a 10% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$110 to US$145 per share, so private investors are already treating Camden Property Trust in very different ways. When you set that against the softer 2026 guidance and flat same property outlook, it is easy to see why opinions spread so widely. Explore those alternate views before deciding how this REIT fits your portfolio.
Explore 2 other Camden Property Trust fair value estimates, including one that suggests it could be worth just $109.97.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Camden Property Trust research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Camden Property Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Camden Property Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Camden Property Trust?
If this update on Camden Property Trust has sharpened your view on income real estate, it can help to line it up against other opportunities, from higher yield options to quieter balance sheet plays. The Simply Wall St Screener lets you filter for what matters to you so you can build a watchlist that fits your own return and risk preferences.
- If reliable cash generation is your priority, start with a 5 dividend fortresses that focus on income resilience rather than just headline yield.
- If you want potential value on your side, compare Camden Property Trust with a 35 high quality undervalued stocks that combine stronger balance sheets and healthier cash flows.
- If you are hunting for future leaders before they are widely followed, scan a 20 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com