
AngloGold Ashanti Stock In Focus After Earnings Beat And Production Guidance Hold
- AngloGold Ashanti reported Q3 2026 results on 5 November, with gold production of 696,000 oz and net income of US$787 million, alongside an interim dividend of US$0.71 per share payable on 11 December.
- Earnings per share from continuing operations rose year over year for both the quarter and nine month period, while full year 2026 production guidance of 2.8 million oz to 3.17 million oz was reaffirmed despite lower output so far.
- We will now consider how AngloGold Ashanti's cost sensitive gold producer investment narrative is affected by stronger earnings and reaffirmed output guidance.
Scan how AngloGold Ashanti stacks up against peers by reviewing a curated set of 33 elite gold producer stocks that may benefit from similar production and earnings catalysts this quarter.
AngloGold Ashanti Investment Narrative Recap
To own AngloGold Ashanti, an investor needs to be comfortable with a large, globally spread gold producer that runs at mid to high costs and is very sensitive to the gold price. According to kapirey, an investor in the Simply Wall St Community, the attraction is scale, reserves and diversification, but the trade off is margin sensitivity and geopolitical exposure.
The latest results keep the near term story focused on two levers. The reaffirmed 2026 production guidance sets volume delivery as the key catalyst. The biggest immediate risk is costs staying high while production tracks below the prior year, which could pressure profitability if gold prices soften.
The most relevant update for that thesis is the reaffirmed full year gold production guidance of 2.8m oz to 3.17m oz, alongside reported output of 696,000 oz for Q3 and 2,164,000 oz for the first nine months. That gap puts execution firmly in the spotlight, because hitting the range depends on mine performance and limited further disruption.
Stronger net income of US$787 million in the quarter and US$3,070 million for the nine months, together with higher earnings per share from continuing operations, gives AngloGold Ashanti more breathing room to fund sustaining capex and exploration while managing its moderate leverage. For a cost sensitive producer like AngloGold Ashanti, that earnings base is a key cushion against operational or jurisdictional shocks highlighted by kapirey.
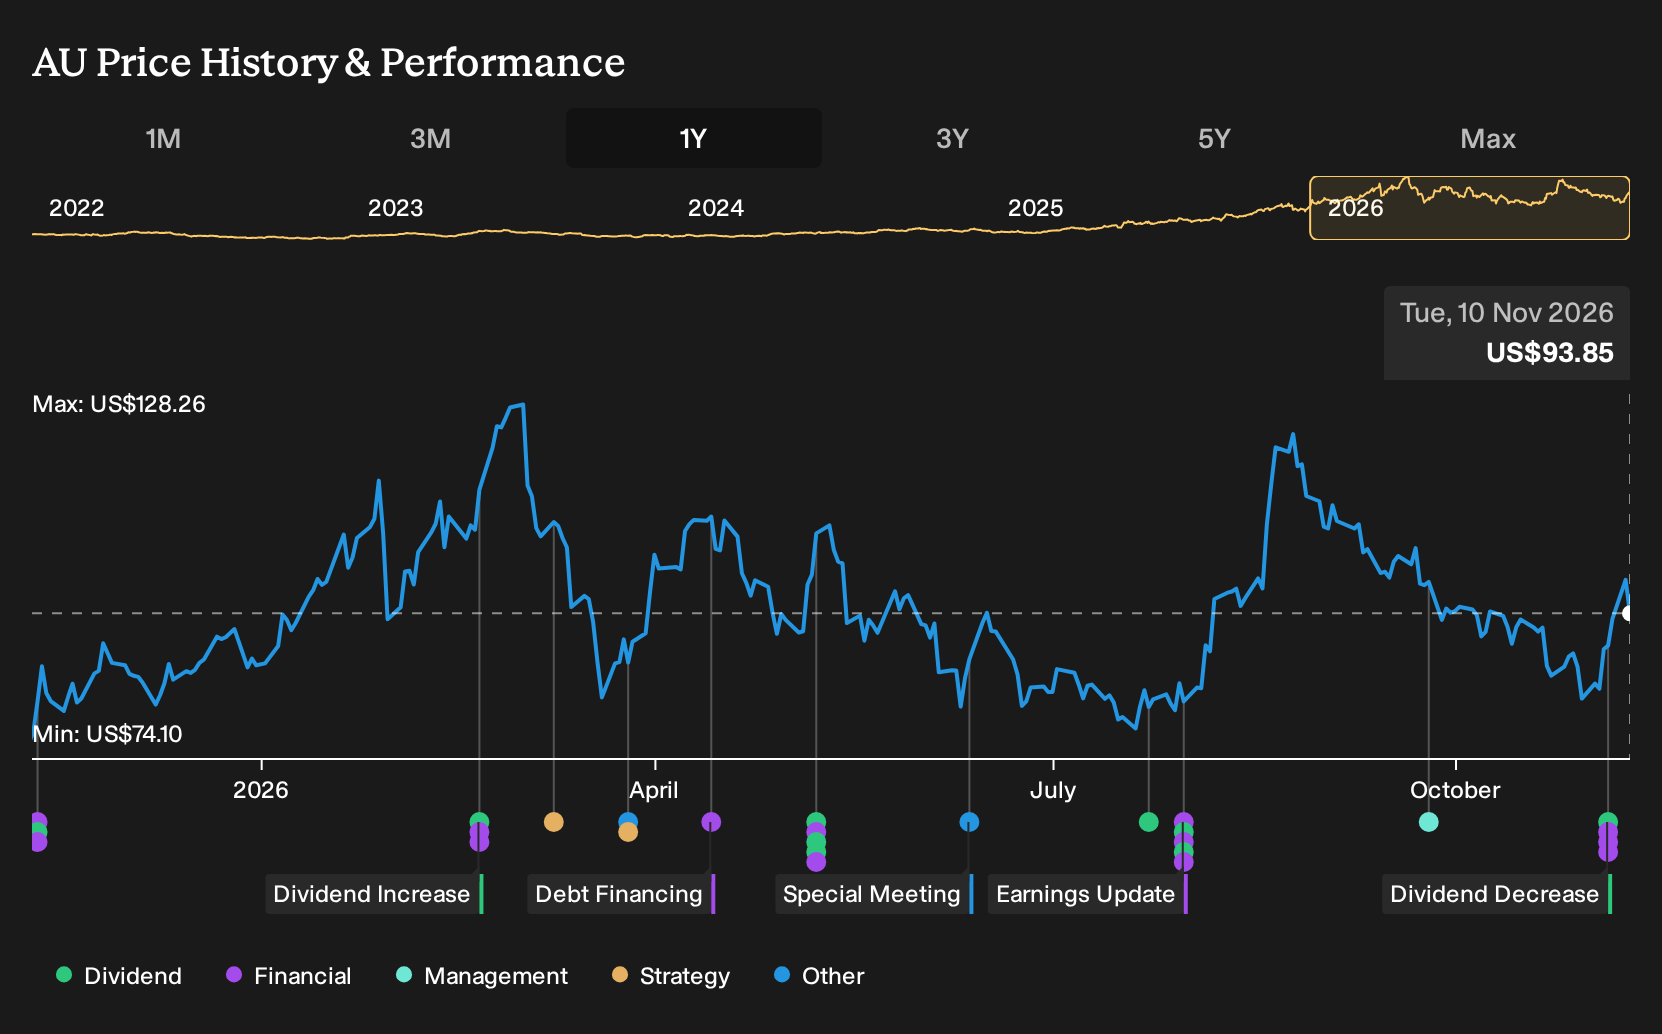
Kapirey assigns a fair value of US$119.72 per AngloGold Ashanti share based on a scenario where revenue compounds at 11.6% a year and the business eventually settles at a 28.0% profit margin. The firm argues that this combination better reflects the scale, reserves and diversification already in place.
Discover how AngloGold Ashanti's fair value indicates a 28% potential upside to its current price, which could close more quickly than many investors expect.
Exploring Other Perspectives
Not every analyst leans on AngloGold Ashanti’s cost sensitivity as the main story. The most optimistic voices focus on potential low cost Nevada growth instead, and were pencilling in about US$19.4b of revenue and US$6.3b of earnings by 2029. Those upbeat estimates, set before this Q3 update and dividend change, may shift once fresh information is absorbed.
Explore 4 other AngloGold Ashanti fair value estimates, including one that suggests potential upside of up to 48% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AngloGold Ashanti research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AngloGold Ashanti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AngloGold Ashanti's overall financial health at a glance.
Looking for more AngloGold Ashanti style ideas?
If this AngloGold Ashanti update has sharpened your thinking about producers, you can apply the same framework to a broader watchlist. The Simply Wall St Screener can help you find other companies with balance sheets, income profiles and risk levels that align with your own tolerance and goals.
- If capital preservation comes first for you, start with companies that score well on resilience by reviewing 30 resilient stocks with low risk scores that could help reduce portfolio volatility.
- If cash generation and financial strength are your priority, focus on sturdier operators through a list of solid balance sheet and fundamentals (24 results) that keeps weaker fundamentals out of the mix.
- If you want ideas that are off most investors' radar, widen your opportunity set with a 20 high quality undiscovered gems that filters for quality metrics many screens miss.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com