
What Bristol Myer Squibb Bulls Got Right
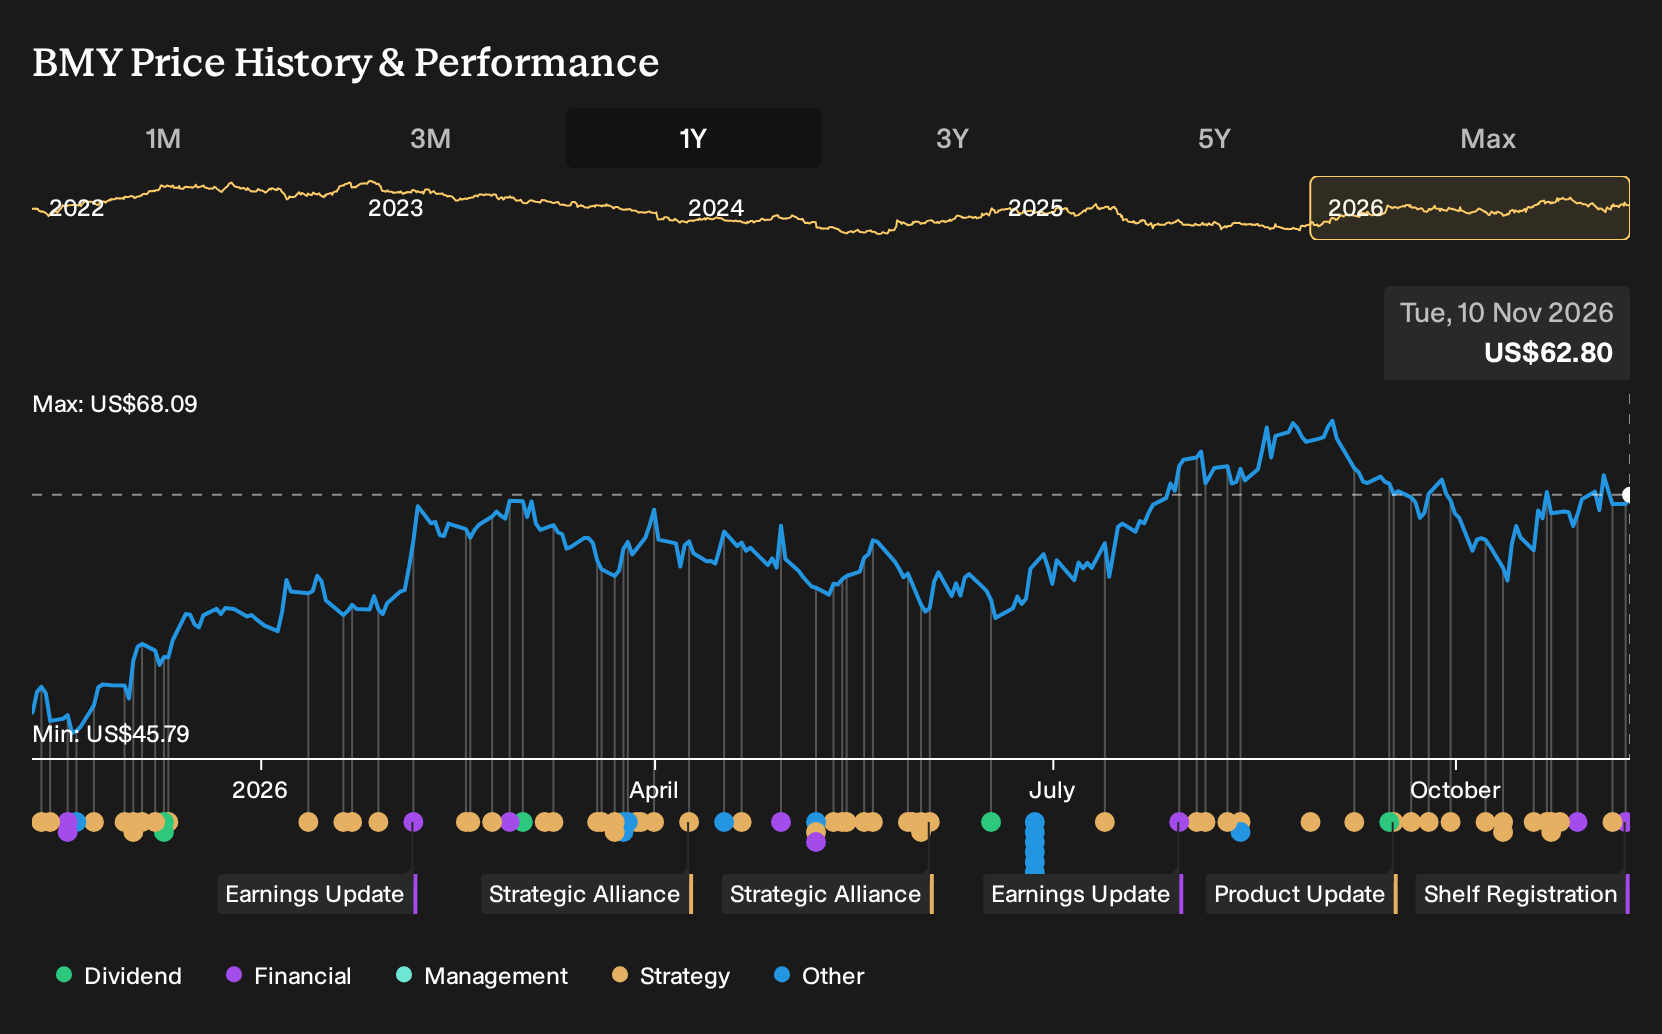
If Bristol-Myers Squibb was on your watchlist instead of in your portfolio, the past year probably feels like a missed shot. Investors who held Bristol-Myers Squibb over the past year are up 34.6%, including dividends. That result lands against a backdrop of split analyst views in late 2025, with some focused on patent-cliff worries and others on aging-demographic optimism. The real puzzle is simple: Which business assumption about future drug demand and pricing power would have helped you lean into this setup before the payoff showed up?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Bristol-Myers Squibb has already moved. Pinpoint other ways to investigate the theme among 36 healthcare AI stocks.
The Two Stories Investors Had To Choose Between On Bristol-Myers Squibb
The shares cost US$47.26 at the start of the period, so any call on Bristol-Myers Squibb began with the question of whether that price already reflected looming patent cliffs or future drug wins.
The bullish narrative saw aging demographics and genomics as a tailwind, put Fair Value at US$53, and leaned on an assumption that revenue would decline 4.7% a year while profit margin reached 22.4% on a 14.4x future P/E.
The bearish view marked Fair Value at US$34 and focused on loss of exclusivity and pricing pressure, with assumptions that revenue would fall 6.4% annually and profit margin would settle at 16.7% on a 13.7x future P/E.
What The Results Changed For The Bristol-Myers Squibb Debate
The clearest marker for Bristol-Myers Squibb was Q3 2026 revenue of US$13,069m against US$12,222m a year earlier, which leaned toward the bullish focus on demand resilience. Net income slipped from US$2,201m to US$2,162m and net margin moved from 18.0% to 16.5%, which challenged the margin uplift both cases were counting on. Overall, the period cut both ways.
The hinge assumption here was pricing power flowing through to profit quality. When you look at another pharma stock, check whether margin trends confirm the story on new drug launches or instead show higher sales without better economics.
What Bristol-Myers Squibb’s Price Already Assumes
Bristol-Myers Squibb now trades at US$62.8, so any fresh decision starts with what that figure already implies. The current Narrative’s Fair Value sits below the market level according to TradingClimbers, an investor in the Simply Wall St Community who wrote the Narrative.
TradingClimbers frames the story as a solid business where the entry tag matters. A buyer today effectively assumes pipeline progress and cash generation will justify this higher price. This raises the question of how the identified patent and pricing risks interact with that confidence.
"What holds me back is not quality but price: at current levels the stock trades above fair value and above my entry filters, so the buy signal stays Risky. I'm interested, but I want a better entry."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
One Step Beyond Bristol-Myers Squibb
Watching Bristol-Myers Squibb can highlight something simple. Chronic disease care keeps expanding.
Those same aging patients still need vaccines, immunology drugs and treatments for rare conditions. Another large drug producer focuses heavily on exactly that mix.
It develops new obesity therapies, antibody drug conjugates for cancer and broader vaccine programs. That work aims to keep future sales less tied to any single product cycle.
If that shift toward more recurring, non pandemic demand holds, your watchlist decision changes. Do you only study Bristol-Myers Squibb, or also the neighbour reshaping its portfolio?
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 26% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com