
Caledonia Mining Shares Slid Even Though Profit Rose
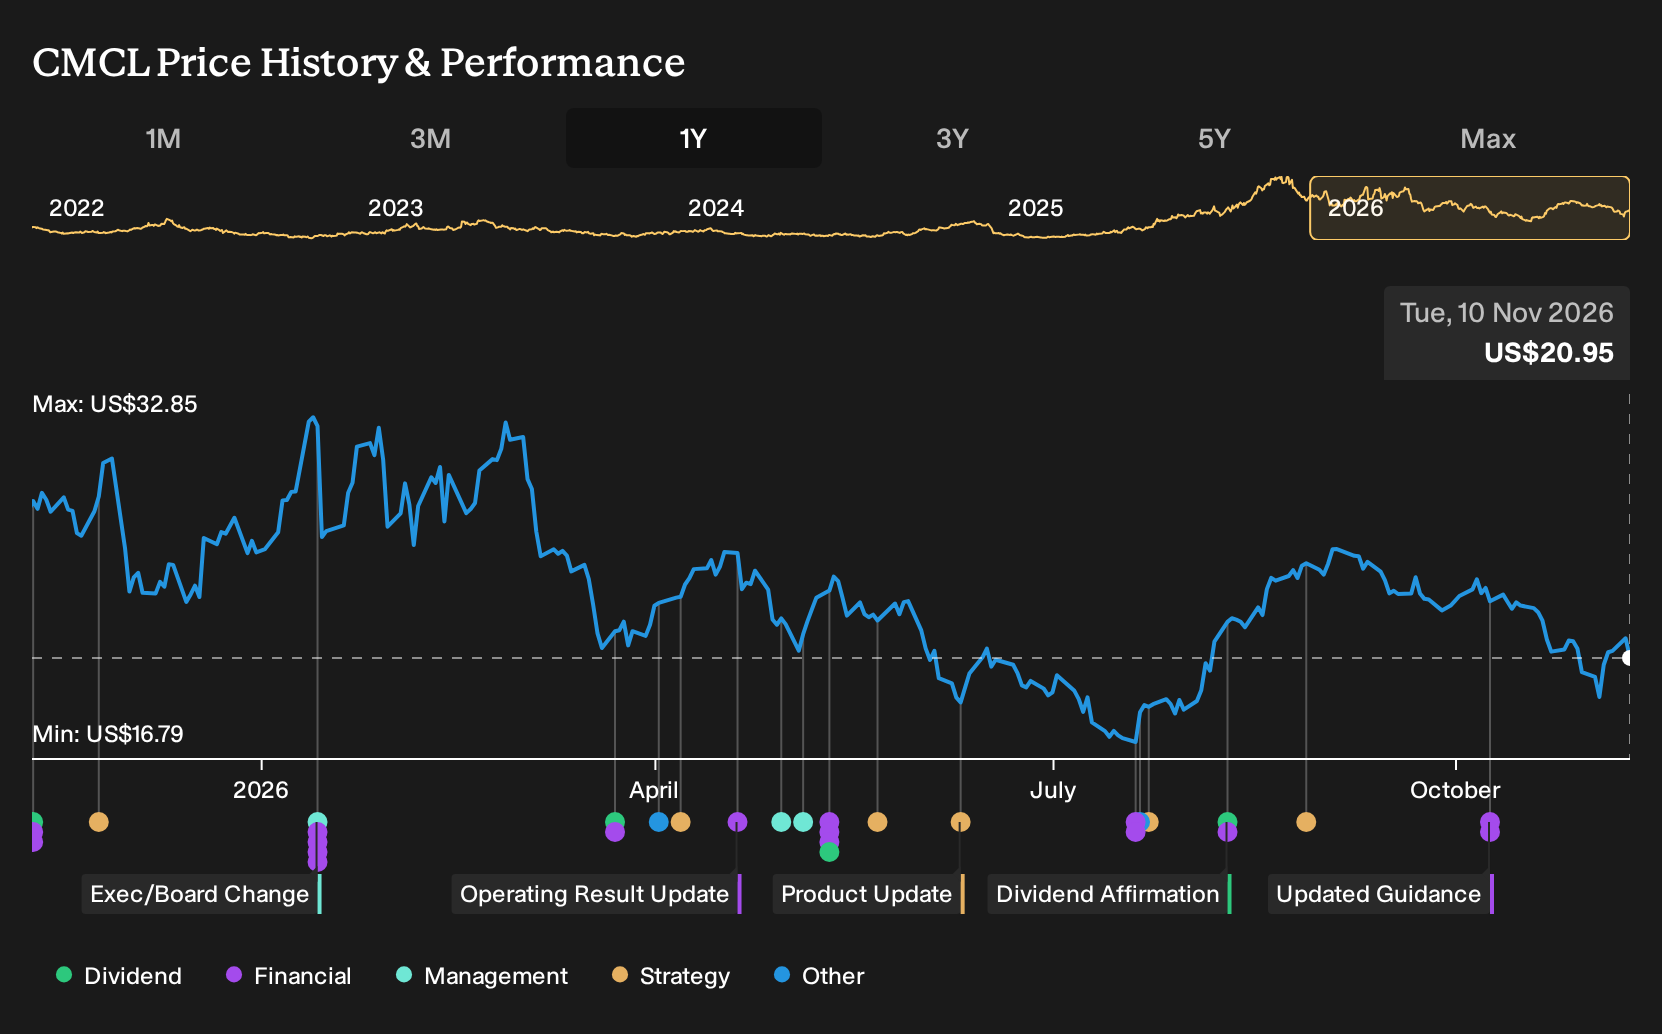
Caledonia Mining has just lined up a US$150 million interim financing package with a group of Zimbabwean banks to push the Bilboes project forward, a concrete step that many investors had been waiting to see. Investors who held Caledonia Mining over the past year are down 24.3%, including dividends. If you had made that call a year ago, how do you now weigh ambitious project funding against fresh questions about execution risk at Bilboes?
Caledonia Mining is not the only name tied to this theme. Zero in on 33 elite gold producer stocks and compare how each one is priced.
The Argument Caledonia Mining Investors Were Really Weighing
The shares cost US$28.71 at the start of the period, and you were essentially choosing between two very different stories about Caledonia Mining.
The bullish narrative saw Bilboes as the key, with a Fair Value of US$37.5, a price implied by assumptions such as revenue growth of 0.3% and a future P/E of 20.5x. That view leaned on strong gold demand, cost controls, and phased Bilboes development to support higher margins.
The bearish script put more weight on concentration risk, rising costs, and gold reliance, with a Fair Value of US$20.75 implied by falling revenue of 2.9% a year and higher ESG related pressure on profitability.
What The Evidence Did To The Caledonia Mining Argument
The interim US$150 million financing for Bilboes directly spoke to the bullish Caledonia Mining thesis that project funding would arrive without heavy equity use. Reported numbers also helped the cautious side. Revenue moved from US$61.802 million in Q2 2025 to US$72.015 million in Q2 2026 while profit rose and net margin stayed at 33.1%.
The episode turned on one testable claim, that Bilboes could be funded while keeping the core mine productive. When you assess another miner, track both project funding sources and how far operating earnings and margins actually cover that capital spend.
What The Fall In Caledonia Mining’s Share Price Now Asks You To Believe
Caledonia Mining changes hands at US$20.95 today, after a 24.3% loss over the past year. According to Genious_Trades, an investor in the Simply Wall St Community who wrote the Narrative, the Fair Value in that work sits above the current price and treats today’s level as too pessimistic.
The Narrative leans on strong reported cash generation, project economics at Bilboes, and a view that Zimbabwe risk already bakes in a heavy discount. Anyone buying after this slide would need to believe those cash flows and project values can offset the country risk that many investors still price in.
"Caledonia Mining Corporation (NYSE: CMCL) currently trades near $24.00 with a market capitalization of roughly $480 million, presenting a stark divergence between its robust cash generation and its politically discounted equity valuation. With FY 2025 revenue surging 46% to $267.7 million, EBITDA reaching $125.3 million, and a transition to a net cash position of $23.8 million, the fundamental baseline is mispriced relative to global peers."
The price and this Narrative do not agree. → Uncover what this Narrative says Caledonia Mining is actually worth
Before The Next Story Makes Headlines
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 39% below our estimate - targets heavier freight loads using AI tools and stricter carrier vetting to curb fraud.
- Company 2 - 25% below our estimate - expands manufacturing capacity to handle AI driven data center optics and higher value photonics programs.
- Company 3 - 30% below our estimate - builds a focused aviation aftermarket platform around engine repair, component services, and OEM backed distribution programs.
Three companies from the same screener. Open the full list of 35 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com