
3 Insurance Stocks To Watch As Nvidia Stock Lawsuit Risk Spreads
The Nvidia saga, now mixing an FBI probe into Jensen Huang, national security fears, and a fresh shareholder lawsuit, has pushed litigation risk from the footnotes to the front page. When governance shocks hit a market leader and wipe more than 4% off Nvidia stock, investor capital often shifts fast. This article examines three stocks exposed to the same news currents, outlining where legal pressure might quietly reshape future return potential.
The three stocks below are just a sample set, and the full screen surfaced 11 more companies with equally litigation focused stories that are not covered in this article. To identify and analyze potential high conviction ideas tied to securities litigation and legal insurance risk, head straight to the Specialized Securities-Litigation Finance and Insurance screener.
AXIS Capital Holdings (AXS)
AXIS Capital Holdings taps directly into the screener theme through its directors’ and officers’ liability and other litigation linked insurance lines. The analyst consensus Narrative on Simply Wall St argues that the real story now is how that specialty mix is being reshaped.
"Shifting focus toward higher margin specialty and short tail lines while deliberately reducing exposure to more volatile or underpriced long tail casualty, professional and cyber business is reshaping AXIS Capital Holdings’ book in ways that are intended to support more stable combined ratios and steadier earnings."
What happens to those steadier results depends heavily on how one unseen pressure plays out for pricing and demand in the coming years.
AXIS Capital Holdings runs a global specialty insurance and reinsurance franchise tied to corporate and securities litigation cover. It generates about US$4.8b from Insurance and US$1.4b from Reinsurance, along with investment income, and carries a market value near US$7.6b.
That unseen pressure is exactly where the story gets interesting, and the full narrative for AXIS Capital Holdings shows how AXIS Capital Holdings might turn litigation stress into a pricing power inflection.

Burford Capital (BUR)
Burford Capital is the pure-play legal finance stock in this screener, wiring investor exposure directly into big ticket corporate and securities disputes, which is exactly why the bearish analyst Narrative on Simply Wall St spends so much time on how its litigation portfolio converts into cash.
"Although Burford Capital reports modeled future realizations of more than US$5.2b at roughly 110% modeled ROIC, the recent requirement to expense US$27 to 31 million of case related costs that can no longer be capitalized means a growing share of portfolio spend may go straight through the income statement."
What happens if a single timing shift in those case outcomes changes how quickly that modeled legal-finance engine shows up in reported margins.
That timing risk is exactly why the full narrative for Burford Capital examines how case realizations, cash conversion, and recognition timing could be separating headline profit from the underlying engine.

Chubb (CB)
Chubb fits this litigation focused screen as one of the global heavyweights in commercial insurance and D&O cover, with the analyst consensus Narrative on Simply Wall St pointing to how its broad P&C, life and reinsurance footprint interacts with governance and shareholder risk at large corporations.
"Record adjusted net investment income of US$1.88b on a US$175b invested asset base, supported by a reported 5.1% portfolio yield and 5.5% reinvestment rate on largely investment grade securities, indicates that future reinvestment of maturing assets could remain an important driver of net investment income and overall earnings."
This raises the question of what could occur if an assumption about how long that investment and liability mix stays this favorable changes at the same time as litigation demand rises.
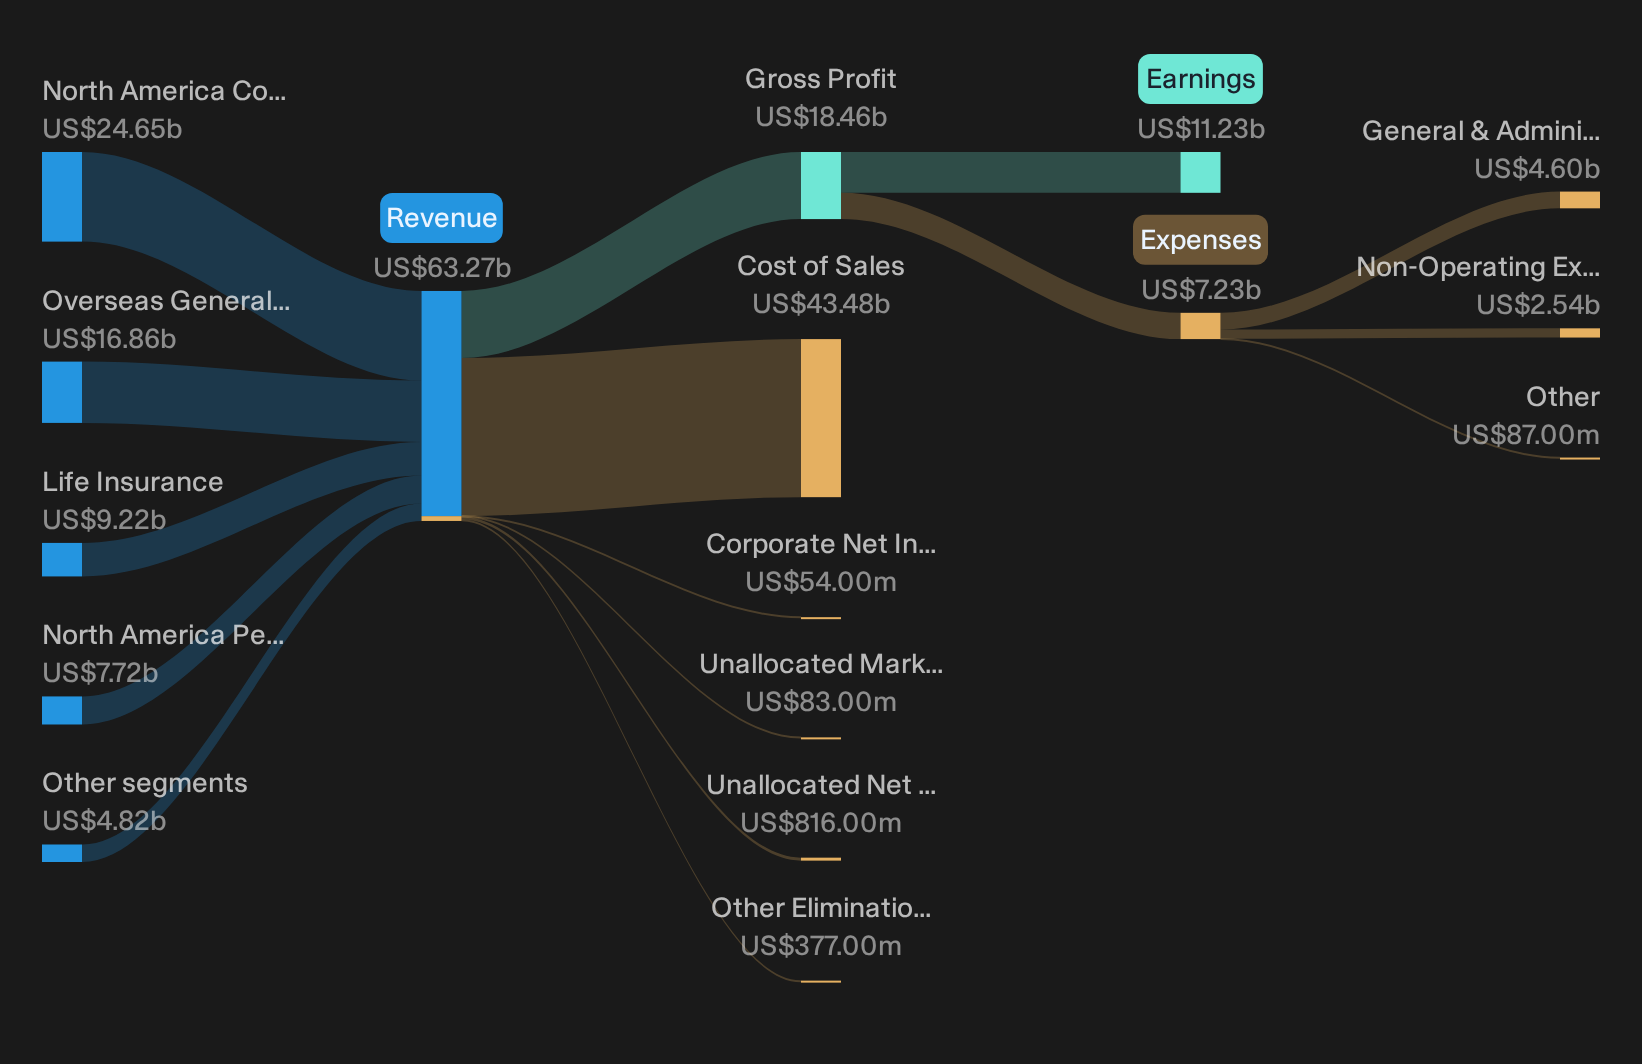
Chubb is a global insurer with a large commercial P&C and D&O footprint that fits the securities litigation theme, generating about US$24.7b from North America Commercial P&C, US$16.9b from Overseas General, US$7.7b from North America Personal P&C and US$9.2b from Life, and it carries a market value near US$138.9b.
That hinges on how you think this cycle evolves, and the full narrative for Chubb maps where Chubb’s litigation exposure and investment engine could be quietly decoupling.
Seeking Alternatives Before Everyone Else
Fresh ideas move first. Breakout trends, early momentum and stories still flying under the radar for now can get caught quickly once the crowd arrives, so act now.
- Spot high yielders that aim to keep paying through cycles by scanning a curated set of 5 dividend fortresses before income hunters crowd the same tickers.
- Track early movers in digital assets exposure by reviewing a focused group from the 21 cryptocurrency and blockchain stocks while the market debate on blockchain is still dropping fresh data.
- Lock in your watchlist around critical metals by checking the tightly filtered 32 best rare earth metal stocks while these suppliers remain under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com