
Is Semtech (SMTC) A Bargain Following Its New IoT ESIM Platform Launch?
Semtech (SMTC) just rolled out its SGP.32 Smart Connectivity Premium eSIM platform, targeting long standing pain points in global IoT deployments, such as single carrier reliance and permanent roaming restrictions.
Against this product launch backdrop, Semtech’s share price has been volatile, with the stock down 39.41% over the past 30 days but still showing a 50.80% year-to-date share price return, supported by a very large 3-year total shareholder return of 633.61%. This points to longer-term momentum rather than a short-term story alone.
Scan beyond Semtech and see how other IoT focused chipmakers are priced and positioned using our curated list of 53 AI infrastructure stocks.
Semtech looks like a robust IoT story after this eSIM launch, yet the share price just fell sharply after a very strong multi year run. Is the business strength already fully reflected in today’s valuation?
Most Popular Narrative: 48% Undervalued
Semtech’s analyst consensus Narrative on Simply Wall St sets a fair value of $217.07 per share, compared with the last close at $113.49. That view leans heavily on long range growth and margin ambitions that are tied to AI data center and IoT demand, discounted back using an 11.56% rate.
Expansion of Semtech's photonics capabilities through indium phosphide gain chips, high power CW lasers, semiconductor optical amplifiers, and planned photodiode arrays is intended to lift content in each optical transceiver from high single digit dollars at 800G to high double digit dollars at 3.2T. Management frames this as a path to a 5x increase in the served available market by FY30 and a very large uplift in data center revenue and gross profit dollars if customer qualifications convert to volume shipments.
See why 42 investors see Semtech as 48% undervalued.
Result: Fair Value of $217.07 (UNDERVALUED)
Still, Semtech’s plan leans heavily on hyperscale AI data center spending and higher R&D paying off, so any slowdown or weak project conversion could quickly challenge that view of the shares as 48% undervalued.
Find out about the key risks to this Semtech narrative.
Another View: Multiples Paint A Richer Picture For Semtech
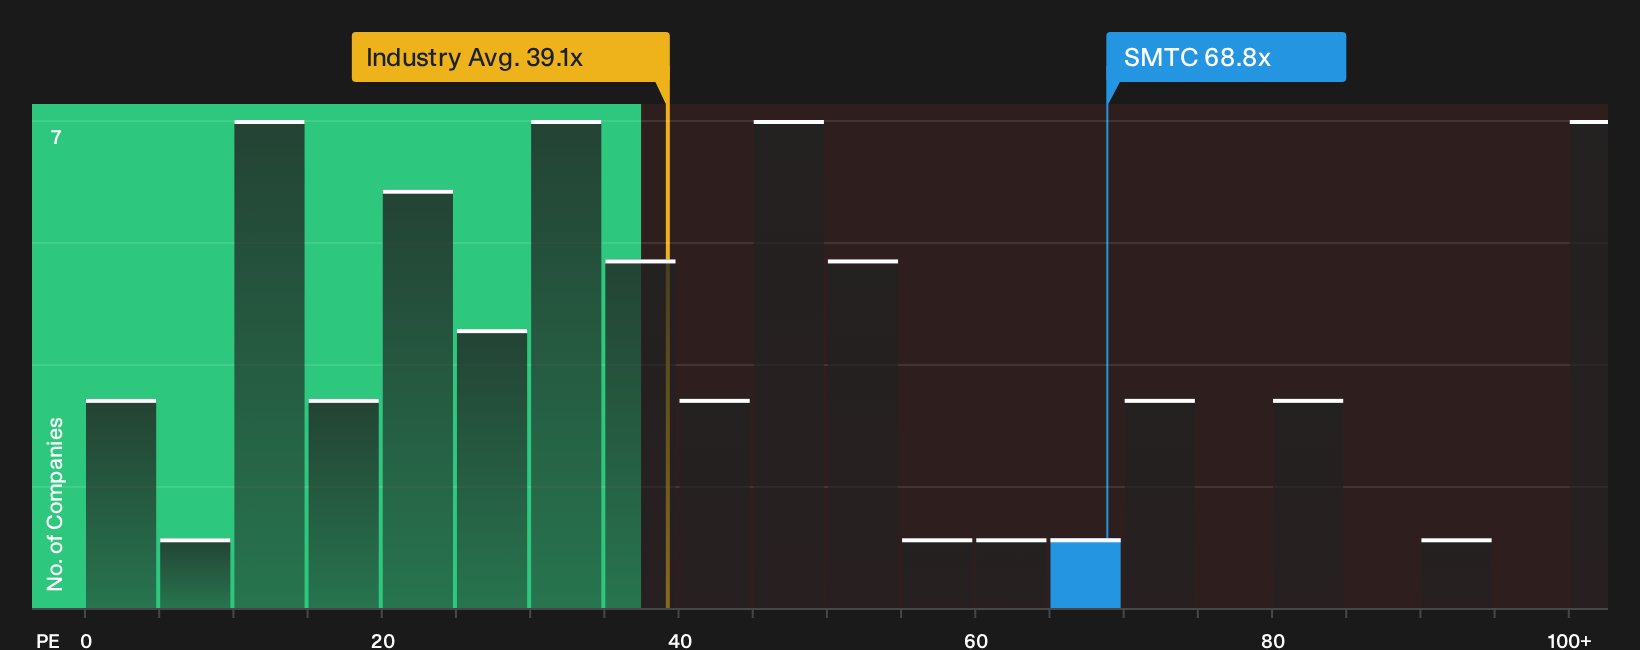
There is a catch. While the narrative and SWS fair value flag Semtech as undervalued on future cash flows, the P/E ratio of 68.8x is well above the US Semiconductor industry on 39.1x and peers on 41.6x, and even sits higher than the SWS fair ratio of 46.8x. That gap points to real valuation risk if execution slips or sentiment cools.
For a closer look at how this earnings multiple compares and where the fair ratio suggests the pricing could drift toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Semtech clearly splits opinion, with strong optimism on future potential and real concern on execution risk. If you want to move fast and base your stance on more than headlines, weigh both sides by checking the 4 key rewards and 3 important warning signs.
Looking for more Semtech sized ideas?
If Semtech has your attention, do not stop there. Use the Simply Wall St screener to quickly surface other clear, data backed opportunities before the crowd spots them.
- Target potential mispricing by focusing on solid businesses trading below fair value, starting with the 35 high quality undervalued stocks.
- Build staying power into your portfolio by concentrating on companies with strong finances using the list of solid balance sheet and fundamentals (24 results).
- Spot opportunities with attractive income today plus resilience potential through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com