
Can Camtek (CAMT) Justify Its Valuation As Earnings Swing Back To Profit?
Camtek (NasdaqGM:CAMT) moved into the spotlight after reporting third quarter 2026 earnings, with sales of US$161.29 million and net income of US$42.84 million, reversing a net loss a year earlier.
Recent trading tells a mixed story. Camtek's share price has fallen 30.8% over the past month and 40.9% over the past quarter. However, the 3 year total shareholder return of 67.1% and 5 year total shareholder return of 118.6% show the longer term trend remains materially positive.
Scan how Camtek compares to other chip-focused opportunities by running through the hand picked 53 AI infrastructure stocks that captures businesses tied to the semiconductor and AI build out story.
Camtek just flipped from a loss to solid profits while the share price has dropped sharply in a matter of months. That mix of stronger results and weaker price raises the key question of what the valuation now looks like.
Most Popular Narrative: 40% Undervalued
Camtek last closed at $102.19, while the analyst consensus Narrative on Simply Wall St anchors fair value at $170.20, implying a wide gap that the narrative treats as undervaluation based on its earnings and revenue assumptions.
Accelerating AI and high performance computing demand is feeding through to advanced packaging and HBM orders for Camtek. Roughly 80% of more than US$600 million of 2026 year to date orders is tied to these applications and scheduled for delivery through 2026 and into 2027, which can support multi year revenue growth. The product cycle shift toward Hawk and Eagle G5 systems, which already account for about 50% of systems revenue in Q2 2026 compared with roughly 30% of total revenue in 2025, is tilting Camtek’s mix toward higher priced platforms that management expects to support higher gross margin and operating income.
See why 34 investors see Camtek as 40% undervalued.
Result: Fair Value of $170.20 (UNDERVALUED)
Still, Camtek’s heavy reliance on AI linked advanced packaging and HBM orders, along with rising competition and pricing pressure from China, could quickly challenge that bullish narrative.
Find out about the key risks to this Camtek narrative.
Another View: What The SWS DCF Model Says About Camtek
While many investors focus on Camtek's P/E of 35.7x versus the US Semiconductor industry at 38.8x and peers at 44.9x, the SWS DCF model lands in a very different place. Based on projected cash flows, it points to a value of $68.61 per share, which is below the recent $102.19 price. That gap raises a simple question for you: Are current expectations closer to the P/E story or the cash flow story?
For readers who want to see how that cash flow view is built line by line, the explanation is in the Look into how the SWS DCF model arrives at its fair value.
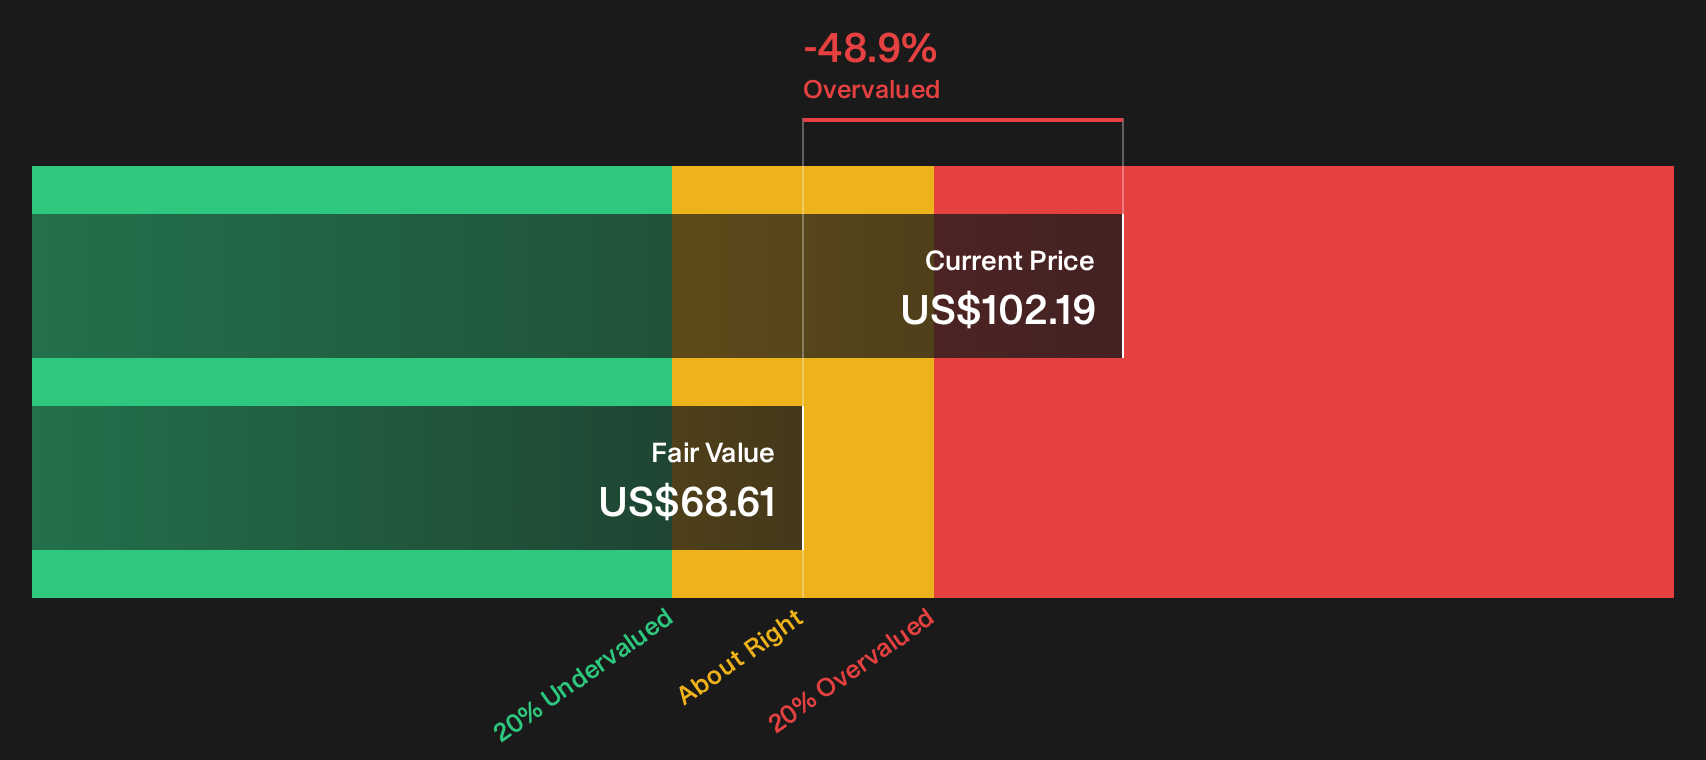
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Camtek for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Views on Camtek are clearly split, with strong recent earnings set against valuation questions and execution risks tied to AI related demand. Act quickly, review the underlying assumptions on both sides, and ground your own stance in the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Camtek?
You have seen how split views on Camtek can be. Use that momentum and widen your watchlist now with a few targeted ideas that fit your style.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (24 results) that pair steady fundamentals with lower financial risk profiles.
- Hunt for mispriced quality by reviewing the 35 high quality undervalued stocks that surfaces stocks with strong cash flows at prices that may not fully reflect them.
- Explore income-focused opportunities by checking the 5 dividend fortresses centered on higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com