
Is Regency Centers (REG) Undervalued After Higher Revenue And Lowered Guidance?
Regency Centers (REG) is in focus after third quarter results showed higher sales and revenue, alongside lower net income and diluted EPS, with management also trimming full year earnings guidance for 2026.
Regency Centers’ share price has climbed 6.23% over the past month and 12.63% year to date, while total shareholder return sits at 11.84% over one year and 37.99% across three years. This suggests recent momentum has been rebuilding as investors weigh the trimmed guidance against ongoing acquisitions and dividend updates.
Spot similar REIT stories by scanning our curated list of solid balance sheet and fundamentals (24 results), which, like Regency Centers, combines income potential with sizable property portfolios.Bulls point to Regency Centers’ recent share price gains, dividend step up and active acquisitions, while bears focus on softer earnings and trimmed guidance. Which story does the current valuation echo more closely for you?
Most Popular Narrative: 10% Undervalued
Regency Centers closed at $76.54 compared with the analyst consensus Narrative fair value of $84.83. This points to a modest valuation gap when set against a discount rate of about 7.86% in that model, according to the analyst consensus Narrative on Simply Wall St.
The main factor that needs to go well is continued execution on Regency Centers' higher-yielding development and redevelopment pipeline, while maintaining its current balance sheet strength and access to liquidity.
The current valuation implies that Regency Centers' share price does not fully reflect its raised 2026 earnings outlook, its growing free cash flow, and the returns targeted on its in-process projects.
See why 8 investors see Regency Centers as 10% undervalued.
Result: Fair Value of $84.83 (UNDERVALUED)
Still, the narrative can break if tenant bankruptcies rise, or if development projects face cost overruns and slower leasing that dilute projected returns.
Find out about the key risks to this Regency Centers narrative.
Another View: What Multiples Say About Regency Centers
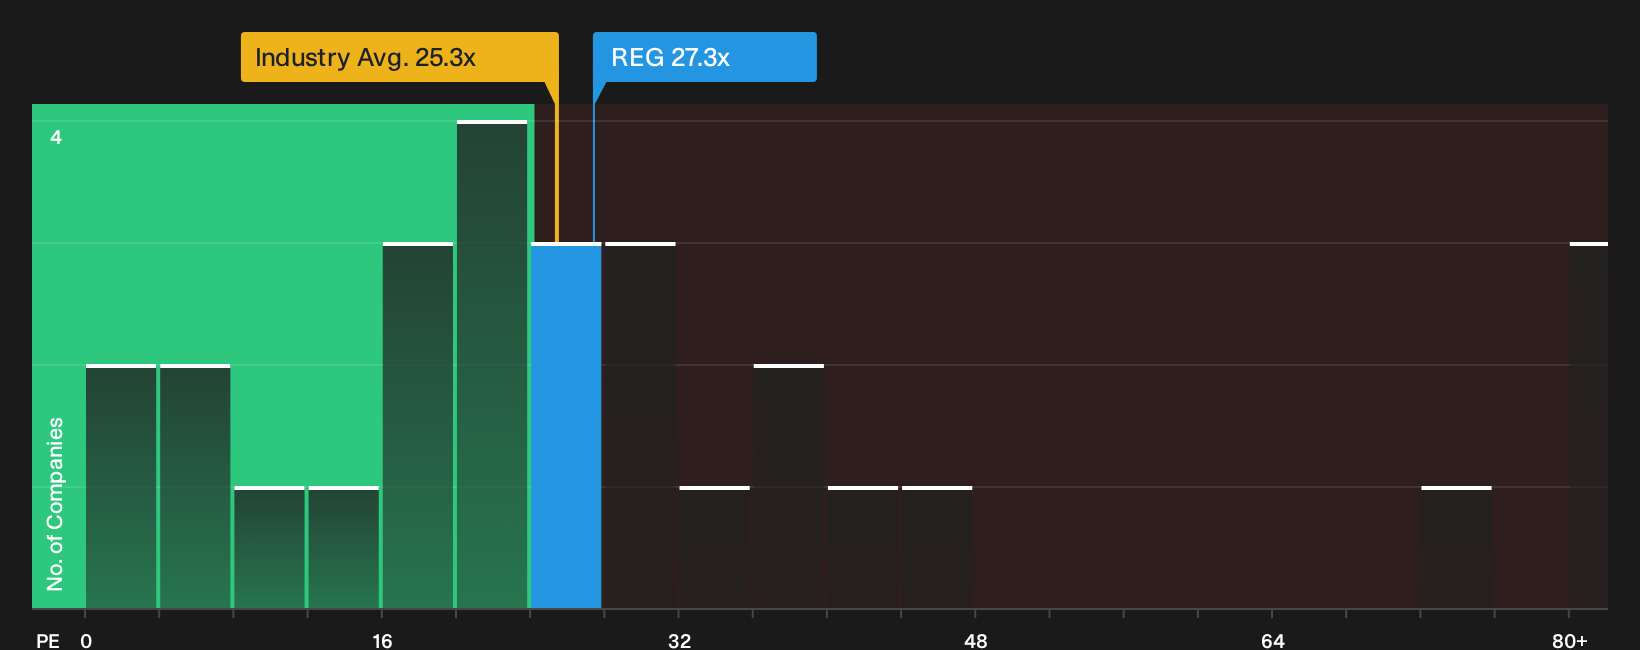
On price, Regency Centers looks less generous than the 10% undervalued narrative suggests. The shares trade on a P/E of 27.3x, slightly above both US Retail REITs peers at 25.0x and direct comparables at 26.8x, while the fair ratio sits higher at 31.9x. That mix hints at some valuation risk if sentiment cools, yet also leaves room if the market leans toward that fair ratio. Which side of that trade off feels more realistic to you?
Before leaning too heavily on headline multiples, it is worth pressure testing what the detailed earnings model is implying for future value and downside risk through our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Regency Centers' outlook and valuation can pull investors in opposite directions, so move quickly to test the numbers yourself and weigh both sides of the story. For a rounded view of what stands out on each side of the ledger, start with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Regency Centers?
If Regency Centers has sharpened your focus on quality, do not stop here. Broader idea hunting can help you spot risks earlier and opportunities sooner.
- Target resilient balance sheets and cash flows by scanning the list of solid balance sheet and fundamentals (24 results) that meet strict financial strength filters.
- Zero in on potential value gaps using the 35 high quality undervalued stocks that highlight quality fundamentals at prices that may not fully reflect them yet.
- Build a steadier income stream by reviewing the 5 dividend fortresses that combine higher yields with disciplined payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com