
Will CEO Appointment Change Expand Energy Stock Narrative
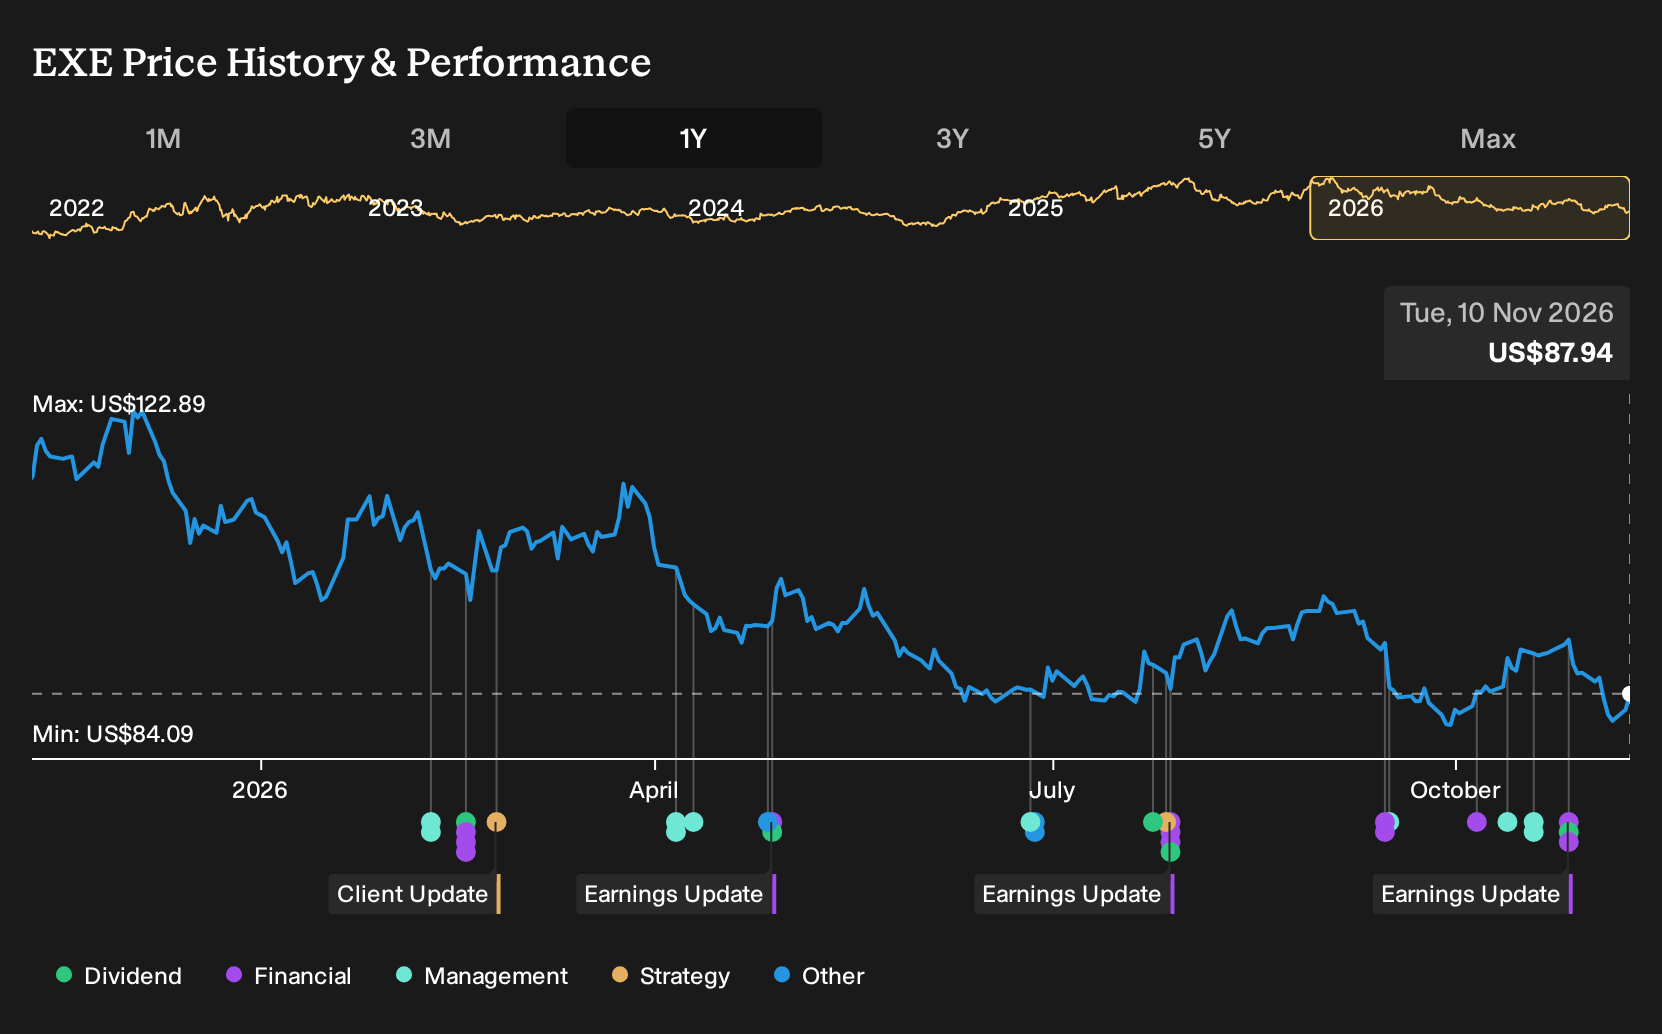
- Expand Energy recently confirmed Danny Brown as permanent CEO and advanced its Twin Eagle acquisition, with the company aiming to operate as an integrated producer and marketer.
- The Twin Eagle deal gives Expand Energy direct commercial access to end customers, with strict synergy hurdles intended to support tighter cost control and risk management across the portfolio.
- We will look at how Expand Energy's investment narrative is shaped by Danny Brown's appointment and the Twin Eagle integration focus.
Scan how other energy marketers are trying to capture value along the chain by reviewing our hand picked 41 power grid technology and infrastructure stocks alongside Expand Energy's latest move into integrated operations.
Expand Energy Investment Narrative Recap
To own Expand Energy, you need to be comfortable with a gas producer leaning hard into an integrated producer marketer model while operating in what management has called a modestly oversupplied market. The near term swing factor is whether execution on marketing and cost efficiencies can support earnings resilience when gas prices stay under pressure.
The biggest operational risk is that this oversupply limits pricing power at the same time as the integrated platform ramps. This could crimp the benefit from new marketing EBITDA and free cash flow targets. Danny Brown becoming permanent CEO and the Twin Eagle integration focus do not radically change this risk reward equation. They mostly sharpen the execution test already in place.
The analyst consensus Narrative on Simply Wall St already framed the Twin Eagle acquisition and related integrated gas buildout as a key catalyst, with a US$250m synergy plan and a goal to lift marketing EBITDA toward about US$350m. That story now sits more squarely on Brown's shoulders because he is charged with turning those targets into actual line items in the income statement and cash flow statement.
Management has also outlined ambitions to raise incremental marketing and commercial free cash flow to around US$750m per year and cut the corporate gas price breakeven by roughly US$0.30 per Mcf. For you as a shareholder, the relevant question is simple: Can Expand Energy integrate Twin Eagle cleanly enough, and control risk tightly enough, for those marketing gains to matter more than any drag from a soft gas tape or future estimate cuts?
What The Current Forecasts Assume For Expand Energy
Expand Energy's current analyst setup leans heavily on the idea that a mostly flat revenue line can still produce better profitability over time. Forecasts point to revenues of about US$12.9b and earnings of roughly US$3.2b by 2029, with margins expected to lift from 22.0% today to 24.8% over the next three years. The story therefore hinges on squeezing more profit out of each dollar of sales rather than chasing top line expansion.
On the earnings side, the move from about US$2.8b today to the US$3.2b consensus implies an increase of roughly US$0.4b by 2029, which is a material jump given that analysts are not baking in strong revenue growth. That gap between earnings today and forecast profit is where execution on Twin Eagle, tighter costs and the integrated marketing buildout has to show up in the actual numbers rather than just in PowerPoint decks.
Under these projections, the implied valuation bridge asks you to accept a P/E multiple of 10.0x on those 2029 earnings compared with around 7.6x today, with a discount rate in the 7.2% to 7.24% range used to pull future cash flows back to present value. Analysts are essentially arguing that if Expand Energy can deliver US$12.9b of revenue and US$3.2b of profit on that timetable, then a modestly higher multiple than today is enough to justify the current set of price targets.
Expand Energy's narrative projects roughly flat revenue trends but a shift toward higher profitability, with analysts expecting earnings of US$3.2b by 2029 compared with about US$2.8b today. This represents an earnings increase of around US$0.4b over that period.
Uncover how Expand Energy's fair value points to a 39% potential upside to its current price before the discount to that value narrows.
Exploring Other Perspectives
One optimistic twist in the alternate Expand Energy story is marketing growth. The most bullish analysts were already penciling in US$13.9b of revenue and US$2.9b of earnings by 2029, tied to a richer marketing and LNG mix. Those views came before Danny Brown’s appointment and the Twin Eagle update, so expect opinions to shift and spread further.
Explore 4 other Expand Energy fair value estimates, including one that suggests as much as 242% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Expand Energy research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Expand Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expand Energy's overall financial health at a glance.
Looking for more investment ideas beyond Expand Energy?
If you want to pressure test your thesis on Expand Energy, it helps to compare it with other stocks that match different risk, income, and quality profiles. The Simply Wall St Screener can help you quickly filter for companies that line up with the type of portfolio you are building.
- If capital preservation is a priority, start with a basket of companies that screen for resilient balance sheets and lower risk profiles using our 30 resilient stocks with low risk scores.
- For investors hunting for potential mispricing, contrast Expand Energy with a curated 35 high quality undervalued stocks that combine strong fundamentals with room for the market to reassess their price tags.
- Income focused readers who want cash returns today can zero in on a 5 dividend fortresses that aim to provide higher yields without ignoring financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com