
Jabil (JBL) Stock May Be A Bargain After Fresh AI Demand News
Jabil has delivered a very strong run for long term holders over the past few years, yet the recent pullback raises a fresh question about whether the current share price still lines up with the earnings behind it. With the stock now around US$249.82 after a weaker few weeks, the key issue is what that history of returns and the latest business trends really say about the valuation.
- Over the past 5 years, Jabil has returned about 292.2%, which puts a lot of accumulated optimism about its profit power under the microscope.
- Sales tied to AI infrastructure, particularly in the Intelligent Infrastructure segment where revenue rose 45.1% in fiscal 2026, can influence how investors think about future margins and the earnings base that supports today’s price.
- There is a second opinion on Jabil worth weighing. See what analysts think Jabil's shares could be worth.
The issue now is whether Jabil's current valuation is adequately supported by the earnings it is generating today and is expected to produce over time.
If you are weighing whether Jabil's AI infrastructure story justifies its past 292.2% return, it can help to compare it with other 53 AI infrastructure stocks.
Is Jabil a Bargain on Earnings?
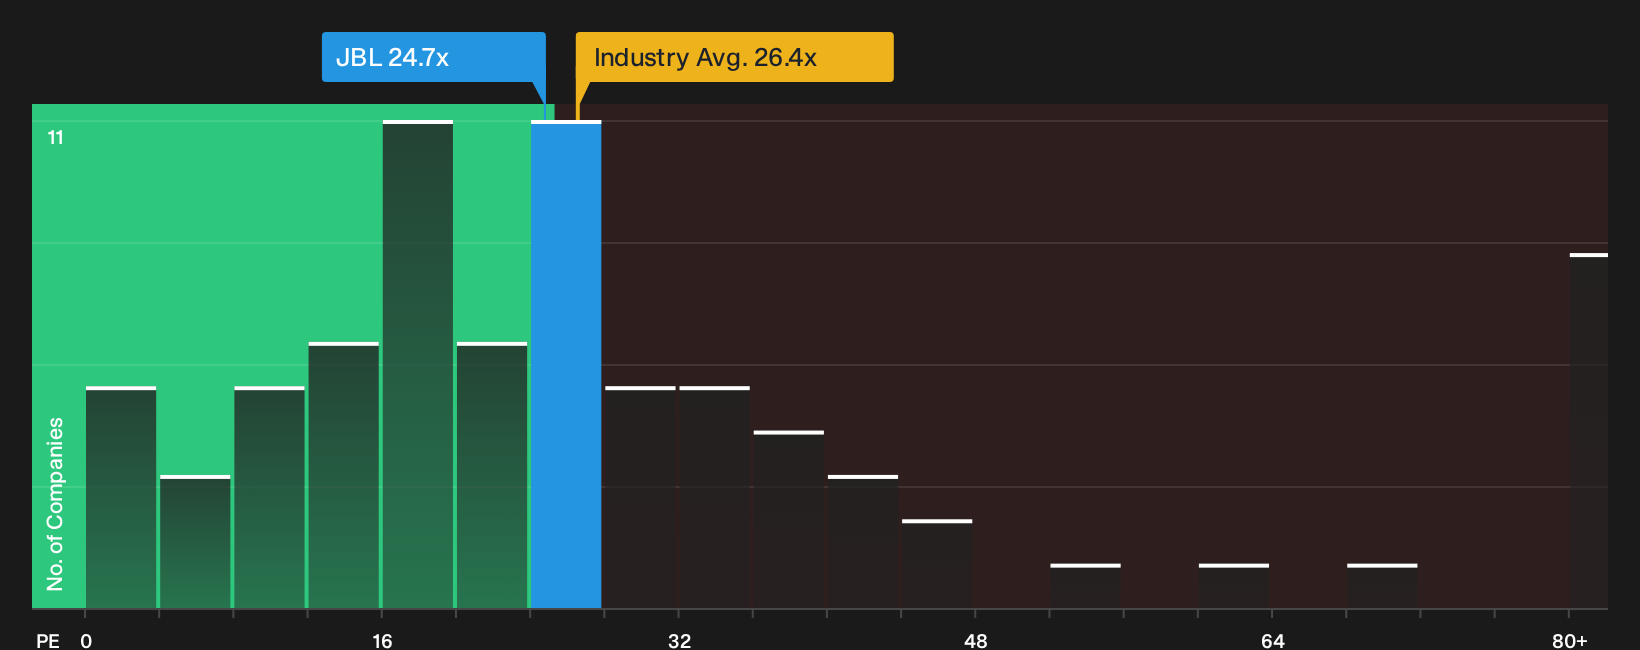
The P/E ratio suits Jabil because earnings are a key lens for a mature manufacturer with large AI infrastructure exposure. Jabil trades on a P/E of about 24.7x, which is slightly above the peer average of 23.6x and just under the wider electronic industry at 26.4x. Because the Fair Ratio model suggests a higher P/E would usually line up with Jabil's mix of growth, margins, size and risk, the current earnings multiple screens as undervalued on that framework.
Because demand for AI infrastructure has pushed Intelligent Infrastructure sales higher in recent years, the current 24.7x P/E reflects investors paying a moderate premium to peers for that earnings base. Despite that AI driven backdrop, the valuation still prices Jabil below what the tailored Fair Ratio implies. This leaves you weighing how durable those earnings and cash flows could be relative to other electronics manufacturers. Explore the numbers behind Jabil's P/E valuation.
The Jabil Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Jabil valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the share price to end up meaningfully higher or lower than it is today. Each storyline links a fair value estimate to a specific mix of potential catalysts and risks, so you can track over time which version of Jabil's journey is actually unfolding on the Community page.
One of the top narratives on Jabil: 41% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"AI related infrastructure programs, with AI revenue guided from about US$9b in fiscal 2025 to roughly US$14.4b in fiscal 2026 and US$22.1b in fiscal 2027 along with an expanded set of hyperscale customers above US$1b each, point to a growing mix of higher value Intelligent Infrastructure work that can lift revenue and core operating margins..."
Discover why this Narrative puts Jabil at 41% undervalued.
One more angle on Jabil that could change your view
There is one piece of the Jabil story that sits outside the valuation work, where Simply Wall St's broader checks have flagged specific concerns that deserve a closer look from you. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com