
Allstate (ALL) Stock Still Looks Reasonable After A 155% Run
Allstate has delivered a powerful run over the past few years, and the stock now sits at US$261.12 after a strong stretch of returns. With that share price move in the rear-view mirror and fresh earnings news on the table, the open question is whether today's valuation is still grounded in the insurer's profit engine.
- Over the past 5 years the stock has returned about 155%, which puts real pressure on the earnings story to carry that kind of performance.
- Recent earnings reports highlighted higher adjusted profit and growth in key insurance policies, which can support expectations for what Allstate's ongoing earnings power might justify.
- Your read on Allstate is one view; the desks covering it have another. See what analysts think Allstate's shares could be worth.
The stock's next move may depend on whether Allstate's current price is fully explained by its earnings profile or is asking investors to pay up for more.
If you want more context around Allstate's recent earnings run and valuation debate, it can help to compare it with other 36 high quality undervalued stocks.
Is Allstate Still Cheap on Earnings?
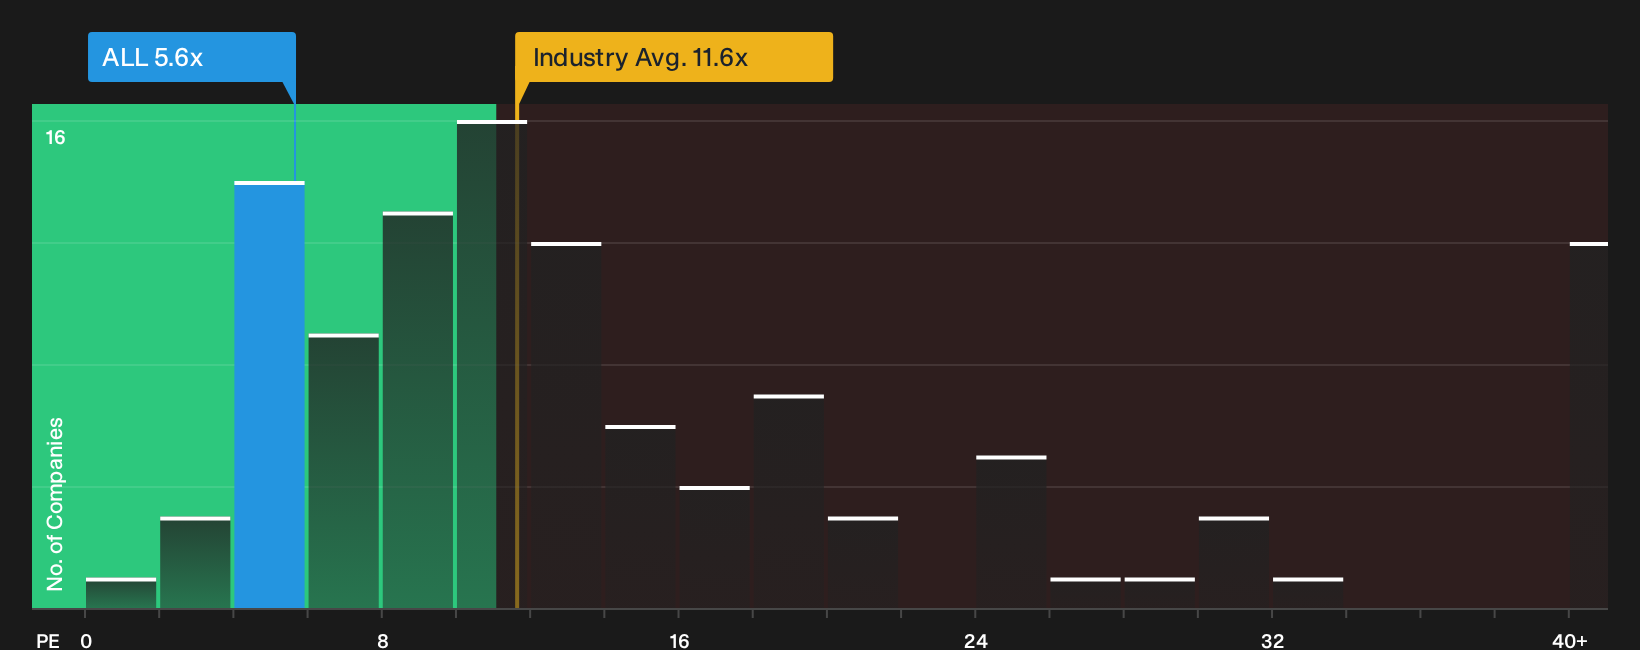
P/E tends to suit Allstate because earnings remain a key lens for insurance groups, where accounting profits capture underwriting and investment results together. On this lens, Allstate trades on roughly 5.6x earnings, which is well below the Insurance industry average of about 11.6x and also under the peer cohort near 9.9x. A tailored fair multiple that adjusts for Allstate's growth outlook, profitability profile, size and risk mix points to a higher level than the current P/E. This frames the stock as undervalued on this approach.
Because the latest Q3 2026 report showed Allstate posting solid adjusted earnings and higher policies in force, this lower P/E appears less like a simple reflection of weak profitability and more like a discount that investors need to interpret against their own expectations for how durable those earnings will be. The gap to that modelled fair P/E gives you a concrete sense of how much the market is currently shading Allstate's profit stream. Explore the numbers behind Allstate's P/E valuation.
The Allstate Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E comparison leaves off by explaining which paths for Allstate's future earnings, margins and policy growth would need to hold for the current share price to look meaningfully high or low, and they sit on Simply Wall St's Community page. Each narrative treats Allstate's implied fair value as a specific idea about the business that investors can revisit over time rather than a one-off snapshot.
One of the top narratives on Allstate: roughly fairly valued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main factor that has to go right is that Allstate continues to convert its underwriting discipline and AI-enabled pricing and claims systems into sustained profitability..."
Discover why this Narrative puts Allstate at roughly fairly valued.
For Allstate, who steers the ship matters as much as what it earns
The next question is who is actually running Allstate, how their incentives are wired, and whether that pay structure lines up with the results you care about as a shareholder. See who runs Allstate and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com